
Learn what credit score you need for an FHA loan in 2026. Discover minimum score requirements, down payment rules, approval tips, and how to qualify.
What Credit Score Do I Need for FHA Loan in 2026?
Buying a home is one of the biggest financial decisions you will ever make. If you are planning to purchase a home in 2026, an FHA loan may be one of the easiest ways to qualify for financing. One of the most common questions buyers ask is, what credit score do I need for an FHA loan in 2026?
The good news is that FHA loans are designed to help borrowers who may not have perfect credit. Compared to many conventional loan programs, FHA loans offer more flexible credit requirements, making homeownership possible for more people.
In this guide, you will learn the minimum FHA credit score requirements, how your credit score affects your loan, and practical ways to improve your chances of approval.
Minimum Credit Score for FHA Loan in 2026
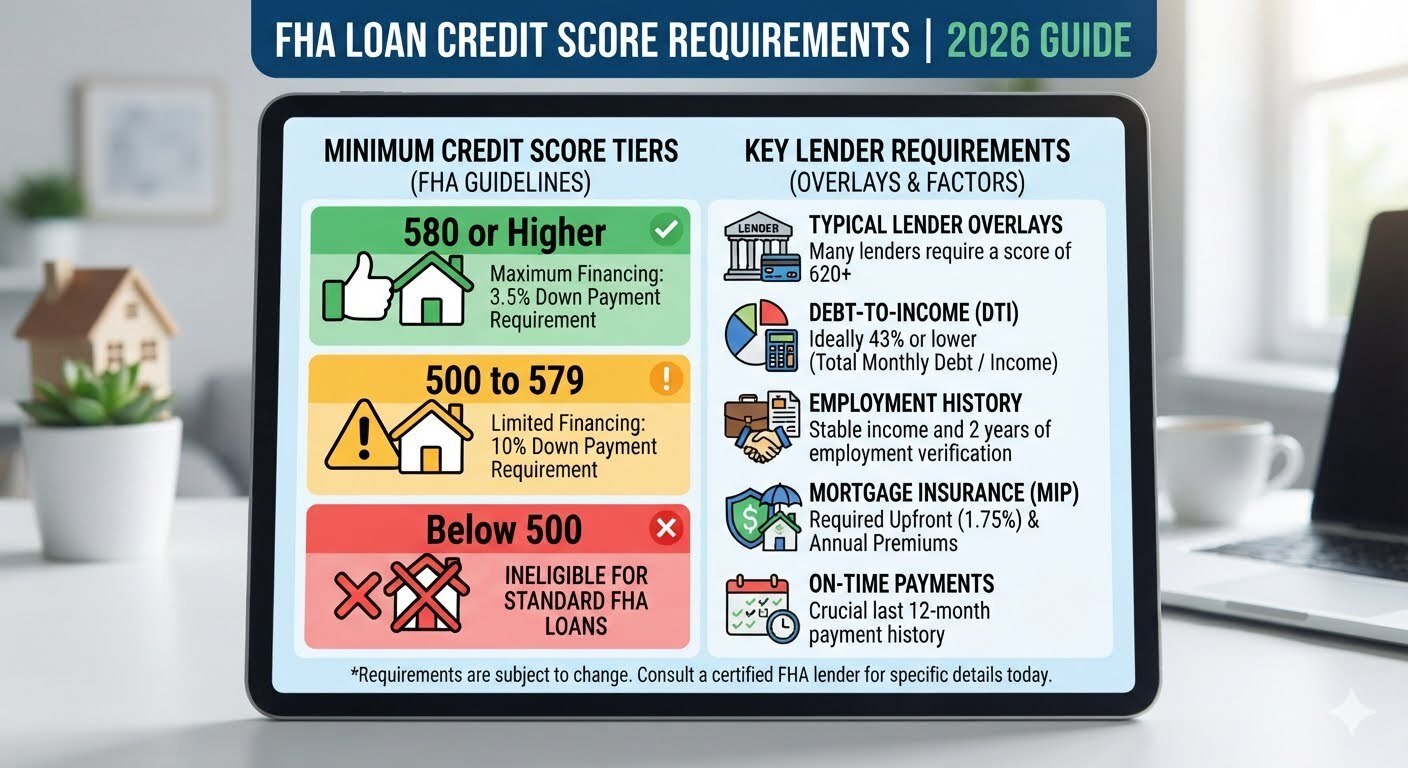
The minimum credit score for an FHA loan in 2026 depends on the amount of your down payment.
Credit Score of 580 or Higher
Most borrowers with a 580 credit score or higher may qualify for an FHA loan with a 3.5 percent down payment, provided they meet lender requirements.
Credit Score Between 500 and 579
Borrowers with a credit score between 500 and 579 may still qualify, but they generally need to make a 10 percent down payment.
Keep in mind that while the Federal Housing Administration allows these minimum scores, many lenders set their own credit requirements. Some lenders may require a score of 620 or higher for easier approval.
How Your Credit Score Affects Your FHA Loan
Your credit score does more than determine eligibility. It can also affect the overall cost of your mortgage.
A higher credit score may help you:
- Qualify with more lenders
- Receive better interest rates
- Improve your approval chances
- Show stronger financial responsibility
- Make the loan process smoother
Even though FHA loans are flexible, improving your credit score before applying can save you thousands of dollars over the life of your mortgage.
What Is Considered a Good Credit Score for an FHA Loan?
While you may qualify with the minimum score, many lenders prefer borrowers with stronger credit.
Here is a general guide:
| Credit Score | FHA Loan Outlook |
|---|---|
| 500 to 579 | Possible with 10 percent down payment |
| 580 to 619 | Eligible with 3.5 percent down payment through many lenders |
| 620 to 679 | Strong approval potential |
| 680 and above | Excellent approval chances and competitive mortgage rates |
Other FHA Loan Requirements in 2026
Your credit score is only one part of the approval process. Lenders also review several other factors.
Stable Income
You should have reliable income that demonstrates your ability to make monthly mortgage payments.
Employment History
Many lenders prefer borrowers with a consistent employment history over the past two years.
Debt to Income Ratio
Your debt to income ratio compares your monthly debt payments with your monthly income. Lower ratios generally improve your approval chances.
Down Payment
Most buyers need at least a 3.5 percent down payment with a qualifying credit score.
Primary Residence
FHA loans are intended for homes that will be your primary residence.
How to Improve Your Credit Score Before Applying
If your credit score is lower than you would like, there are several ways to improve it before applying for an FHA loan.
Pay Bills on Time
Your payment history has one of the biggest impacts on your credit score. Making every payment on time can gradually improve your credit.
Reduce Credit Card Balances
Lower balances can improve your credit utilization, which may increase your score.
Check Your Credit Report
Review your credit report for errors and dispute any inaccurate information.
Avoid Opening New Credit Accounts
Applying for multiple new credit accounts before buying a home can temporarily lower your score.
Keep Older Accounts Open
Long standing credit accounts can strengthen your credit history.
Can You Get an FHA Loan With Bad Credit?
Yes. One of the biggest advantages of an FHA loan is that it was created to help borrowers with less than perfect credit.
Even if your credit score is below 580, you may still qualify if you meet other lending requirements and can make a larger down payment.
Each lender has different guidelines, so it is worth comparing multiple lenders to find one that fits your financial situation.
FHA Loan Benefits in 2026
Many home buyers choose FHA loans because they offer several advantages.
Lower Credit Requirements
Borrowers with limited credit history may still qualify.
Smaller Down Payment
Qualified buyers may purchase a home with only 3.5 percent down.
Flexible Qualification Standards
FHA loans are often easier to qualify for than many conventional mortgages.
Competitive Interest Rates
Many borrowers receive attractive mortgage rates compared with other loan options.
Available for Many First Time Home Buyers
FHA loans continue to be one of the most popular choices for new home buyers.
Tips for Getting Approved for an FHA Loan
If you want to improve your approval chances in 2026, consider these tips.
Save for Your Down Payment
Having enough money saved demonstrates financial responsibility.
Lower Existing Debt
Paying down loans and credit cards can improve your debt to income ratio.
Maintain Stable Employment
Avoid changing jobs immediately before applying if possible.
Review Your Credit Before Applying
Know your credit score and address any issues early.
Compare Multiple FHA Lenders
Different lenders may have different credit score requirements and interest rates.
Frequently Asked Questions
What is the minimum credit score for an FHA loan in 2026?
Most borrowers need a 580 credit score to qualify for the minimum 3.5 percent down payment. Borrowers with scores between 500 and 579 may qualify with a larger down payment.
Can I get an FHA loan with a 600 credit score?
Yes. A 600 credit score generally meets the FHA minimum requirement and may qualify you for financing if you meet the lender’s other guidelines.
Is a 500 credit score enough for an FHA loan?
Possibly. FHA guidelines allow borrowers with scores between 500 and 579 to qualify with a 10 percent down payment, although many lenders require higher scores.
Does a higher credit score lower my mortgage rate?
In many cases, yes. Higher credit scores often help borrowers receive more competitive mortgage interest rates and better loan options.
Do all FHA lenders have the same credit score requirements?
No. Individual lenders may establish their own minimum credit score requirements that are higher than FHA guidelines.
Can first time home buyers use an FHA loan?
Yes. FHA loans remain one of the most popular mortgage options for first time home buyers because of their flexible qualification standards.
Does FHA require perfect credit?
No. FHA loans were created to help borrowers who may not have excellent credit, provided they meet other eligibility requirements.
Conclusion
If you are wondering what credit score you need for an FHA loan in 2026, the answer is encouraging. Most buyers can qualify with a 580 credit score and a 3.5 percent down payment, while some borrowers with scores as low as 500 may still qualify with a larger down payment. Your credit score is important, but lenders also consider your income, employment history, debt to income ratio, and overall financial profile.
Improving your credit before applying can increase your approval chances and may help you secure a lower mortgage rate. By understanding FHA loan requirements and preparing your finances, you can take a confident step toward homeownership in 2026.






