Buying a home is one of the biggest financial decisions many Americans make, and understanding FHA Loan Rates 2026: Current Rates & Expert Tips can help buyers plan their next move with confidence. FHA mortgage rates influence monthly payments, total interest costs, and the overall affordability of a home loan.
In simple terms, FHA loan rates are the interest rates lenders offer for Federal Housing Administration-backed mortgages. These rates can change based on economic conditions, credit scores, loan terms, lender policies, and market trends.
For 2026, borrowers are paying close attention to mortgage rate movements because even a small rate difference can significantly affect long-term costs. A buyer choosing between a slightly lower or higher FHA rate could save thousands of dollars over a 30-year mortgage.
This guide explains how FHA Loan Rates work, what affects them, how they compare with conventional mortgages, and practical ways to improve your chances of getting a better rate.
Quick answer: FHA loan rates in 2026 depend on market conditions, borrower qualifications, lender pricing, and economic factors. The best way to get competitive rates is to improve your credit profile, compare lenders, and understand all loan costs before signing.
What Are FHA Loan Rates in 2026?
FHA loan rates are the interest rates attached to FHA-insured home loans. The Federal Housing Administration does not directly set mortgage rates. Instead, private lenders determine rates based on financial markets, borrower risk, and loan details.
FHA loans are popular because they provide flexible qualification options compared with many conventional mortgages. They are especially helpful for first-time buyers, people with smaller down payments, and borrowers who may not have perfect credit histories.
In 2026, FHA mortgage rates continue to depend on several major factors:
- Economic conditions
- Inflation levels
- Federal Reserve policies
- Mortgage market demand
- Borrower credit profile
- Loan amount and location
A lower FHA interest rate means a smaller monthly payment and less interest paid throughout the loan term. However, borrowers should also consider other costs, including mortgage insurance premiums and closing expenses.
Understanding FHA Mortgage Rates
FHA mortgage rates work similarly to other home loan interest rates. When a borrower takes an FHA mortgage, they agree to repay the borrowed amount plus interest over a specific period.
Most FHA buyers choose a 30-year fixed-rate mortgage because it provides predictable monthly payments. Some borrowers may choose shorter loan terms to reduce total interest costs.
For example, a borrower purchasing a $300,000 home with an FHA loan may have a different monthly payment depending on whether their interest rate is slightly higher or lower. Even a small percentage difference can create a noticeable change over decades.
The final FHA rate offered by a lender may also depend on:
- Credit score
- Employment history
- Debt-to-income ratio
- Down payment amount
- Loan term
How FHA Loan Rates Compare With Conventional Mortgage Rates
Many home buyers compare FHA loans with conventional mortgages before making a decision.
FHA loans are backed by the government, which reduces risk for lenders. Because of this guarantee, lenders can often offer more flexible approval requirements.
However, FHA loans usually require mortgage insurance, which can increase the overall cost of borrowing.
| Feature | FHA Loan | Conventional Loan |
|---|---|---|
| Down Payment | Usually starts at 3.5% | Often higher depending on borrower |
| Credit Requirements | More flexible | Usually stricter |
| Mortgage Insurance | Required | Depends on equity |
| Best For | First-time buyers and flexible qualification | Strong credit borrowers |
The right choice depends on personal finances, long-term goals, and overall affordability.
FHA Loan Rates 2026: Current Trends and Predictions
Understanding current mortgage trends can help buyers decide when to apply for financing. FHA Loan Rates 2026 are influenced by the broader housing and economic environment.
Mortgage rates often move based on inflation expectations and changes in financial markets. When inflation decreases and economic conditions stabilize, mortgage rates may become more favorable. However, unexpected market changes can also impact borrowing costs.
According to mortgage industry data sources such as Freddie Mac’s Primary Mortgage Market Survey, mortgage rates change regularly based on market conditions and investor activity.
External resource:
Freddie Mac Mortgage Market Survey
What Is the Average FHA Loan Rate in 2026?
The exact FHA mortgage rate available to borrowers varies by lender and personal financial situation. There is no single FHA rate that applies to every buyer.
Two borrowers applying on the same day may receive different offers because lenders evaluate:
- Credit history
- Income stability
- Loan size
- Property type
- Debt obligations
A borrower with a stronger financial profile may receive better pricing compared with someone with higher risk factors.
Before choosing a lender, buyers should request multiple loan estimates and compare:
- Interest rate
- Annual percentage rate (APR)
- Closing costs
- Mortgage insurance expenses
- Monthly payment
Factors That Could Change FHA Mortgage Rates in 2026
Several economic factors can influence FHA mortgage rates throughout the year.
Inflation and Economic Conditions
Inflation plays an important role in mortgage pricing. When inflation remains high, lenders may increase rates to manage financial risk.
When inflation slows, mortgage markets may experience more stability.
Federal Reserve Decisions
The Federal Reserve does not directly set mortgage rates, but its monetary policies influence financial markets.
Changes in federal interest rates can affect borrowing conditions and investor expectations.
Housing Market Demand
The demand for homes can also affect mortgage activity. When more buyers enter the market, lenders may adjust pricing based on competition and market conditions.
Factors That Affect FHA Loan Rates
Many borrowers assume that FHA Loan Rates are the same for everyone, but lenders calculate rates based on several personal and market-related factors. Understanding these factors can help buyers prepare before applying and potentially secure better mortgage terms.
The FHA program creates flexible lending guidelines, but lenders still review each borrower’s financial profile. A stronger application usually gives buyers more options when comparing mortgage offers.
Credit Score and FHA Mortgage Rates
Your credit score is one of the most important factors affecting the FHA mortgage rate you receive. Although FHA guidelines allow borrowers with lower credit scores to qualify, lenders may offer better pricing to applicants with stronger credit histories.
For example, a borrower with a credit score above 700 may receive more competitive loan offers compared with someone who has a lower score and a history of missed payments.
Before applying for an FHA loan, consider these steps:
- Review your credit report for errors
- Pay down high credit card balances
- Avoid opening unnecessary new accounts
- Make payments on time consistently
Improving your credit score by even a few points may help you access better lending options.
Credit Score Guide for Mortgage Buyers
Down Payment Amount and Interest Rate
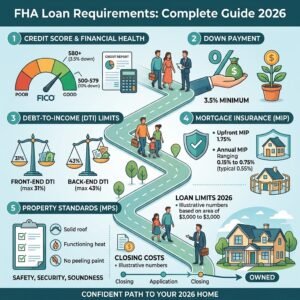
The FHA program is known for allowing lower down payments, with eligible borrowers able to put down as little as 3.5%.
However, your down payment can still affect your overall borrowing profile. A larger down payment may reduce your loan amount and improve your financial position.
For example:
A buyer purchasing a $300,000 home:
- 3.5% down payment: $10,500 upfront
- 10% down payment: $30,000 upfront
The second borrower may have a smaller loan balance, which can reduce monthly costs.
While FHA rates are not only determined by down payment size, reducing your loan amount can make your mortgage more affordable.
Loan Amount and Property Location
The size and location of your FHA loan can also influence available mortgage terms.
FHA loan limits vary by county because housing costs are different across the United States. A buyer in an expensive housing market may have different options compared with someone purchasing a home in a lower-cost area.
Factors lenders consider include:
- Loan amount
- Property value
- Local housing market
- County FHA limits
- Type of property being purchased
Understanding local FHA requirements before shopping for homes can prevent unexpected financing issues.
Debt-to-Income Ratio (DTI)
Your debt-to-income ratio shows how much of your monthly income goes toward paying debts.
Lenders use DTI to determine whether a borrower can comfortably manage mortgage payments.
A lower DTI generally creates a stronger application because it shows better financial flexibility.
Common debts included in DTI calculations:
- Car loans
- Student loans
- Credit card payments
- Personal loans
- Existing mortgages
Reducing unnecessary debt before applying may improve your overall mortgage profile.
How to Get the Best FHA Loan Rates in 2026
Getting the lowest possible FHA mortgage rate requires preparation. The advertised rate is not always the final rate every borrower receives.
Here are practical strategies buyers can use in 2026.
Improve Your Credit Profile Before Applying
A stronger credit profile can help you qualify for more competitive mortgage offers.
Start preparing several months before applying by:
- Paying bills on time
- Lowering credit utilization
- Avoiding large purchases
- Checking your credit reports
A borrower who prepares early often has more negotiating power with lenders.
Compare Multiple FHA Mortgage Lenders
One of the biggest mistakes buyers make is accepting the first mortgage offer they receive.
Different lenders may provide different FHA Loan Rates because each company has its own pricing models, fees, and risk assessments.
When comparing lenders, review:
- Interest rate
- APR
- Origination fees
- Closing costs
- Mortgage insurance expenses
- Estimated monthly payment
A difference of even 0.25% in interest rate may create meaningful savings over a long mortgage term.
External Resource:
Consumer Financial Protection Bureau Mortgage Guide
Consider Different Loan Terms
Most FHA borrowers choose a 30-year fixed mortgage because it offers predictable payments.
However, some buyers may consider shorter loan terms.
30-Year FHA Mortgage
Benefits:
- Lower monthly payments
- Easier budgeting
- More flexibility
15-Year FHA Mortgage
Benefits:
- Less total interest
- Faster loan payoff
- Builds home equity faster
The best option depends on your income, financial goals, and comfort level with monthly payments.
Understand FHA Mortgage Insurance Costs
FHA loans require mortgage insurance, which protects lenders if borrowers default.
There are two types:
Upfront Mortgage Insurance Premium (UFMIP)
This is an initial premium usually added to the loan balance.
Annual Mortgage Insurance Premium (MIP)
This cost is paid monthly as part of the mortgage payment.
Some borrowers focus only on the interest rate but ignore mortgage insurance costs. A lower rate does not always mean a cheaper loan if other expenses are higher.
FHA Loan Rates vs Conventional Mortgage Rates in 2026
Choosing between an FHA loan and a conventional mortgage depends on your financial situation.
FHA loans are designed to make homeownership accessible, especially for buyers who need flexible qualification requirements.
Conventional loans may be better for borrowers with strong credit scores and larger down payments.
| Category | FHA Loan | Conventional Loan |
|---|---|---|
| Government Backing | Yes | No |
| Minimum Down Payment | Around 3.5% for eligible borrowers | Can vary |
| Credit Flexibility | More flexible | Usually stricter |
| Mortgage Insurance | Required | May be removed after equity requirements |
| Ideal Borrower | First-time buyers | Strong financial profiles |
Neither option is automatically better. The right choice depends on your budget, credit history, and long-term plans.
Who Should Consider FHA Loans in 2026?
FHA loans remain popular among different types of home buyers because of their flexible requirements.
First-Time Home Buyers
Many first-time buyers choose FHA financing because they may not have large savings or perfect credit.
The lower down payment requirement can make entering the housing market easier.
Buyers With Limited Savings
Saving enough money for a home purchase can be challenging. FHA loans allow buyers to purchase homes without needing a very large upfront payment.
However, buyers should still maintain emergency savings after closing.
Borrowers Improving Their Credit Profile
FHA loans can provide an opportunity for borrowers who are rebuilding their financial profile.
A responsible payment history after purchasing a home may help improve future borrowing opportunities.
First Time Home Buyers Guide
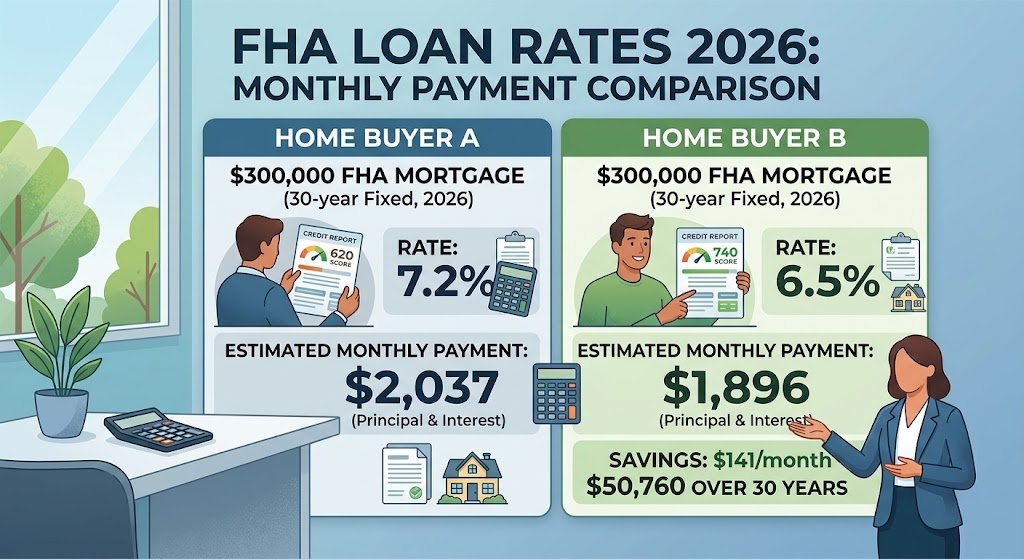
How Much Can FHA Loan Rates Affect Your Monthly Payment?
Many buyers focus only on qualifying for a mortgage, but the interest rate they receive can have a major impact on their monthly budget. Even a small difference in FHA Loan Rates can change the total amount paid over the life of the loan.
For example, consider a borrower purchasing a $300,000 home with a 30-year FHA mortgage. A rate difference of 0.50% may increase or decrease the monthly payment by a noticeable amount. Over 30 years, this small percentage change can add up to thousands of dollars in additional interest.
This is why buyers should not only ask, “Can I qualify for an FHA loan?” They should also ask:
- Is this the best rate available?
- Are the lender fees reasonable?
- Will this mortgage fit my long-term budget?
A lower monthly payment can provide more financial flexibility for homeowners, especially when combined with responsible budgeting.
Expert Tips to Save Money on FHA Loan Rates in 2026
Finding a competitive FHA mortgage rate requires more than waiting for market conditions to improve. Borrowers can take active steps to strengthen their applications and reduce borrowing costs.
Lock Your Mortgage Rate at the Right Time
Mortgage rates can change frequently because they are connected to financial markets.
Once you find a suitable FHA loan offer, ask your lender about a rate lock. A rate lock protects your agreed interest rate for a specific period while your loan moves through the approval process.
Before locking your rate, consider:
- How long the closing process may take
- Whether rates are expected to change
- Available lender options
Avoid Taking New Debt Before Applying
New debt can affect your mortgage approval and may change the rate you receive.
Before applying for an FHA loan, avoid major financial changes such as:
- Financing a new vehicle
- Opening multiple credit cards
- Taking personal loans
- Making large purchases
Lenders review your debt-to-income ratio during the application process, so keeping your finances stable is important.
Review Your Loan Estimate Carefully
Every mortgage lender provides a Loan Estimate that explains the expected costs of your loan.
Do not look only at the interest rate. Review:
- Loan amount
- Monthly payment
- Closing costs
- APR
- Mortgage insurance costs
- Prepaid expenses
Two lenders may advertise similar FHA Loan Rates but have different fees that affect the total cost.
Work With an Experienced Mortgage Professional
An experienced loan officer can help you understand available options and avoid unnecessary costs.
A good mortgage professional should explain:
- Different FHA programs
- Rate options
- Loan fees
- Closing requirements
- Long-term payment impact
Borrowers should feel comfortable asking questions before making a final decision.
Common Mistakes When Choosing FHA Loan Rates
Even eligible buyers can make costly mistakes when selecting a mortgage. Understanding these common problems can help you make a better decision.Focusing Only on the Interest Rate
A low interest rate looks attractive, but it is not the only factor that determines affordability.
A mortgage with a slightly lower rate but high fees may cost more than another option with reasonable closing costs.
Always compare the complete loan package.
Not Comparing Different Lenders
Many buyers apply with only one lender and accept the first offer.
This can limit their ability to find better terms.
Comparing at least three lenders can help buyers understand:
- Current market pricing
- Available loan options
- Different fee structures
Ignoring Mortgage Insurance Costs
FHA loans include mortgage insurance requirements. Some borrowers forget to include these costs when calculating their monthly budget.
A complete affordability calculation should include:
- Principal payment
- Interest payment
- Mortgage insurance
- Property taxes
- Home insurance
- Maintenance costs
Making Financial Changes Before Closing
After approval, some buyers make major financial decisions that create problems.
Examples include:
- Changing jobs without discussing it with the lender
- Taking new credit
- Moving large amounts of money without documentation
Keeping financial records stable helps avoid delays.
Frequently Asked Questions About FHA Loan Rates 2026
What are FHA Loan Rates expected to be in 2026?
FHA Loan Rates in 2026 will depend on economic conditions, inflation, mortgage market activity, and borrower qualifications. Rates can vary between lenders and individual applications.
Are FHA Loan Rates lower than conventional mortgage rates?
FHA mortgage rates can sometimes be competitive compared with conventional rates, especially for borrowers with lower credit scores or smaller down payments. However, buyers should compare the complete loan cost, including mortgage insurance and fees.
What credit score is needed for FHA Loan Rates?
Many FHA borrowers qualify with a credit score around 580 and a 3.5% down payment. Some lenders may have additional requirements depending on their lending policies.
Can FHA mortgage rates change before closing?
Yes. FHA rates can change before closing unless the borrower has locked the rate with the lender. A rate lock protects the agreed rate for a specific time period.
How can I get better FHA Loan Rates in 2026?
Borrowers can improve their chances by increasing their credit score, reducing debt, comparing multiple lenders, maintaining stable income, and reviewing all loan costs carefully.
Final Thoughts: Are FHA Loan Rates 2026 Right for You?
FHA Loan Rates 2026 will continue to play an important role for Americans planning to purchase homes. FHA financing remains a useful option for buyers who want flexible qualification requirements and lower down payment options.
However, choosing the right mortgage is about more than finding the lowest advertised rate. Buyers should compare lenders, understand mortgage insurance costs, review loan estimates, and consider their long-term financial goals.
A borrower who prepares early often has more opportunities to secure favorable terms. Improving credit, maintaining stable finances, and researching lenders can make the home buying process smoother.
Before choosing an FHA mortgage, take time to compare your options and understand the full cost of ownership.
FHA Loan Calculator