
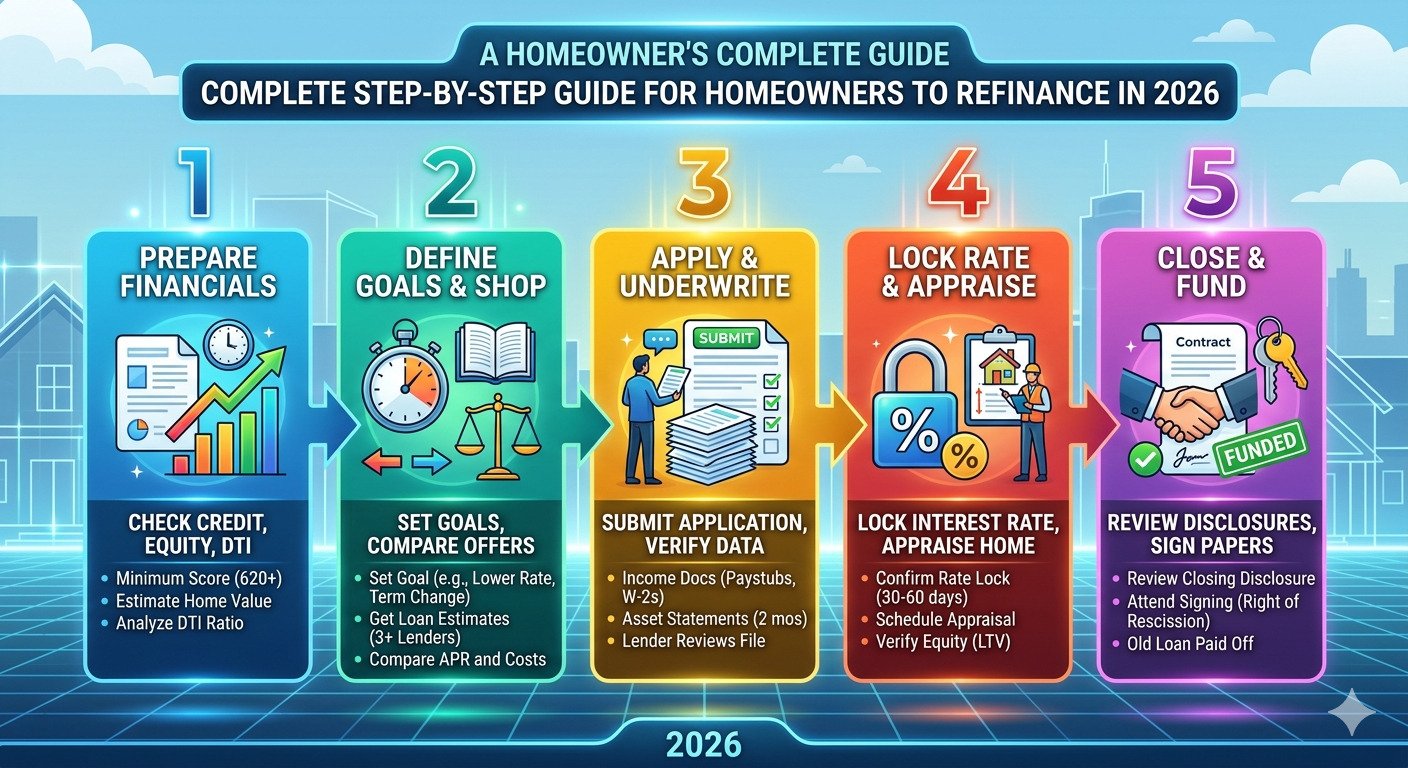
Refinancing your home in 2026 can be a powerful way to improve your financial situation. Many homeowners are exploring new loan options to reduce monthly payments, secure better interest rates, or unlock home equity for important needs.
This guide explains the full process in simple language so you can understand exactly how home refinancing works and how to do it the right way.
Introduction to Home Refinancing in 2026
Home refinancing means replacing your current mortgage with a new loan that has updated terms. The new loan may offer a lower interest rate, a different repayment period, or access to cash from your home value.
In 2026, lenders are focusing more on income stability, credit strength, and property value. This means preparation and planning are very important before applying.
Many homeowners refinance to reduce financial pressure and improve long term savings.
Why Homeowners Choose to Refinance Their Home
There are several reasons people choose home refinancing in 2026.
Lower monthly payments
Refinancing can reduce your monthly financial burden and help with budgeting.
Better interest rates
If market rates are lower than your current rate, refinancing may help you save money over time.
Change in loan term
Some homeowners choose a shorter loan term to pay off debt faster while others extend their term for easier payments.
Access to home equity
Refinancing can allow you to use the value built in your home for education, repairs, or personal needs.
Step by Step Guide to Refinance Your Home in 2026
Here is a clear and simple process to follow.
Step 1 Review your current mortgage
Start by understanding your existing loan. Check your interest rate, remaining balance, and monthly payment details. This helps you compare new offers.
Step 2 Check your credit situation
Your credit history plays an important role in refinancing approval. A stronger credit profile often leads to better loan offers and lower rates.
Step 3 Understand your home value
Lenders will evaluate your property value before approving refinancing. A higher home value may increase your chances of getting better terms.
Step 4 Compare different lenders
Do not accept the first offer you receive. Compare multiple lenders to find the best interest rate and repayment option for your situation.
Step 5 Prepare your documents
You will need important documents such as income proof, bank statements, employment details, and property records. Having everything ready speeds up the process.
Step 6 Submit your application
Once you choose a lender, fill out the application carefully. Make sure all information is accurate to avoid delays.
Step 7 Loan approval process
The lender will review your application, verify your details, and assess your financial profile. If approved, you will move to final steps.
Step 8 Closing the new loan
At closing, you will sign the final documents. Your new loan will replace your old mortgage guider hub and your refinancing process will be complete.
Types of Home Refinancing Options
Understanding different refinancing options helps you choose the right one.
Rate reduction refinance
This option helps you secure a lower interest rate and reduce monthly payments.
Term adjustment refinance
This allows you to change your repayment duration based on your financial goals.
Cash out refinance
This option lets you borrow against your home value and receive funds for personal or financial needs.
Requirements for Home Refinancing in 2026
Lenders usually review several important factors before approval.
• Credit history and score
• Stable monthly income
• Debt and income balance
• Property valuation report
• Employment stability
Meeting these requirements improves your chances of approval and better loan terms.
Benefits of Refinancing Your Home
Refinancing offers several financial advantages when done at the right time.
Improved monthly cash flow
Lower payments can help you manage your budget more comfortably.
Long term savings
A lower interest rate may save a large amount over the life of your loan.
Better financial flexibility
You can adjust your loan structure to match your current lifestyle.
Access to funds
You can use home equity for education, repairs, or other important expenses.
Common Mistakes to Avoid in Home Refinancing
Many homeowners lose money by making simple mistakes.
Not comparing lenders
Always review multiple offers before making a decision.
Ignoring closing costs
Refinancing can include fees that should be considered in your planning.
Choosing the wrong loan structure
Make sure the new loan fits your long term financial goals.
Not preparing credit early
Improving your credit before applying can help you get better rates.
Tips to Get the Best Refinancing Deal in 2026
Here are some useful tips to improve your chances of approval and savings.
Improve your credit profile before applying
Pay down existing debts to improve your financial standing
Keep all financial documents organized
Apply when interest rates are favorable
Avoid taking new large loans before refinancing
These steps can help you secure better loan terms and reduce overall costs.
Conclusion
Refinancing your home in 2026 is a smart financial move if done at the right time with proper planning. It can help you reduce monthly payments, improve interest rates, and gain better control over your finances.
The key is to compare options, understand your financial situation, and choose a lender that matches your needs. With the right approach, refinancing can bring long term financial benefits and stability.
Frequently Asked Questions
1 What is home refinancing
Home refinancing is the process of replacing your current fha mortgage brokers with a new loan that has improved terms.
2 Is refinancing a good idea in 2026
Yes, if interest rates are lower or your financial situation has improved, refinancing can be beneficial.
3 How long does refinancing take
The process usually takes a few weeks depending on lender checks and document verification.
4 Do I need good credit to refinance
A stronger credit profile improves your chances, but some lenders may still offer flexible options.
5 What costs are involved in refinancing
You may need to pay appraisal fees, processing fees, and closing costs depending on the lender.
6 Can I take cash from my home during refinancing
Yes, a cash out option allows you to access your home equity for personal or financial needs.
7 When is the right time to refinance
The best time is when interest rates are lower than your current mortgage rate or when your financial situation improves.






