
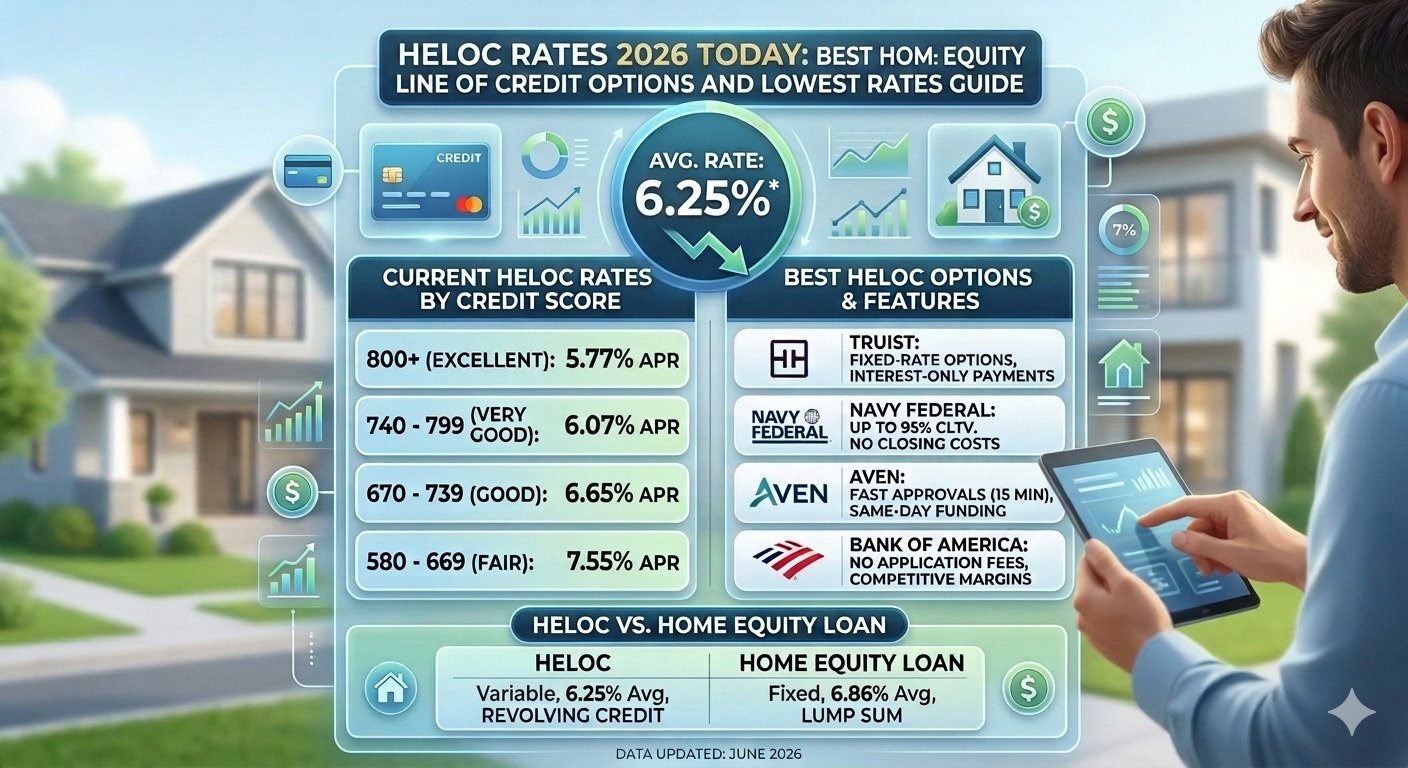
Compare HELOC rates 2026 today, learn how home equity lines of credit work, find the best lenders, and discover tips to secure lower rates.
HELOC Rates 2026: Best Home Equity Line of Credit Options

A Home Equity Line of Credit, commonly known as a HELOC, remains one of the most flexible borrowing options for homeowners in 2026. With rising home values and changing interest rates, many homeowners are exploring HELOC loans to fund home improvements, debt consolidation, education expenses, and other major financial goals.
Understanding current HELOC rates and choosing the right lender can help you save thousands of dollars over the life of your credit line. This guide explains everything you need to know about HELOC rates in 2026 and how to find the best home equity line of credit for your needs.
What Is a Home Equity Line of Credit?
A Home Equity Line of Credit is a revolving credit account secured by the equity in your home. Unlike a traditional home equity loan that provides a lump sum, a HELOC allows you to borrow funds as needed up to an approved credit limit.
Homeowners often use HELOC funds for:
- Home renovations
- Debt consolidation
- Emergency expenses
- College tuition
- Business investments
- Major purchases
The flexibility of a HELOC makes it a popular financial tool when used responsibly.
Understanding HELOC Rates in 2026
HELOC rates are typically variable, meaning they can change over time based on market conditions. Most lenders calculate rates using a benchmark index plus a margin determined by your financial profile.
Factors That Affect HELOC Rates
Several factors influence the interest rate you receive:
Credit Score
Borrowers with excellent credit generally qualify for lower HELOC rates.
Loan to Value Ratio
A lower loan to value ratio often results in better borrowing terms.
Home Equity Amount
The more equity you have in your property, the more favorable your rate may be.
Income and Debt
Lenders evaluate your debt to income ratio to determine your ability to repay.
Market Conditions
Changes in national interest rates can directly impact HELOC pricing.
Benefits of a HELOC
Many homeowners prefer a home equity line of credit because it offers unique advantages.
Flexible Access to Funds
Borrow only what you need when you need it.
Lower Interest Rates
HELOC rates are often lower than personal loans and credit cards.
Interest Only Payment Options
Some lenders allow interest only payments during the draw period.
Large Borrowing Limits
Depending on your home equity, you may qualify for substantial credit limits.
Best Uses for a HELOC in 2026
Home Improvement Projects
Renovations can increase property value while providing a comfortable living space.
Debt Consolidation
A HELOC may help combine high interest debt into a lower rate payment.
Education Expenses
Many families use home equity to cover college costs.
Emergency Financial Needs
A HELOC can serve as a financial safety net during unexpected situations.
How to Compare the Best HELOC Lenders
Choosing the right lender involves more than simply finding the lowest advertised rate.
Compare Interest Rates
Review both introductory and ongoing rates.
Check Fees
Pay attention to:
- Application fees
- Annual fees
- Closing costs
- Early closure fees
Review Borrowing Limits
Different lenders offer different credit limits based on property value and borrower qualifications.
Look at Customer Service
Reliable customer support can make managing your account easier.
Evaluate Repayment Terms
Understand the draw period and repayment period before committing.
How to Get the Lowest HELOC Rate
If you want the best home equity line of credit rates, consider these strategies.
Improve Your Credit Score
Pay bills on time and reduce outstanding balances.
Increase Home Equity
Making fha mortgage brokers payments and improving property value can strengthen your application.
Reduce Existing Debt
Lower debt levels improve your debt to income ratio.
Shop Multiple Lenders
Comparing offers can help you find better terms and lower rates.
Prepare Documentation
Having income, tax, and property documents ready can speed up approval.
HELOC vs Home Equity Loan
Many homeowners wonder whether a HELOC or a home equity loan is the better choice.
| Feature | HELOC | Home Equity Loan |
|---|---|---|
| Funds Access | As needed | Lump sum |
| Interest Rate | Usually variable | Often fixed |
| Flexibility | High | Moderate |
| Payment Structure | Flexible | Fixed |
| Best For | Ongoing expenses | One time projects |
A HELOC is often better for ongoing projects, while a home equity loan may work better for a single large expense.
Risks of Using a HELOC
Although HELOCs offer flexibility, there are risks to consider.
Variable Rates
Monthly payments can increase if interest rates rise.
Risk to Your Home
Your property serves as collateral, which means missed payments could lead to foreclosure.
Overspending
Easy access to funds may encourage unnecessary borrowing.
Understanding these risks can help you make responsible borrowing decisions.
Who Should Consider a HELOC?
A home equity line of credit may be a smart option if you:
- Have substantial home equity
- Need flexible access to cash
- Maintain a strong credit profile
- Plan to finance home improvements
- Want an alternative to high interest credit cards
Borrowers with stable income and responsible financial habits often benefit most from a HELOC.
Future Outlook for HELOC Rates in 2026
Many financial experts expect HELOC rates to remain an important borrowing option throughout 2026. While rates may fluctuate based on economic conditions, competition among lenders continues to create opportunities for qualified borrowers.
Monitoring market trends and comparing offers regularly can help homeowners secure favorable terms.
Frequently Asked Questions
What is the average HELOC rate in 2026?
Average HELOC rates vary by lender, credit score, and market conditions. Borrowers with strong financial profiles generally receive the lowest rates.
Is a HELOC better than a personal loan?
A HELOC often provides lower interest rates and higher borrowing limits, but it uses your home as collateral.
How much can I borrow with a HELOC?
Most lenders allow borrowing up to a percentage of your available home equity, depending on qualifications.
Do HELOC rates change over time?
Yes. Most HELOCs have variable interest rates that can rise or fall with market conditions.
Can I use a HELOC for home renovations?
Yes. Home improvement projects are among the most common uses for a HELOC.
What credit score is needed for a HELOC?
Many lenders prefer scores of 680 or higher, though stronger scores typically receive better rates.
Are there closing costs for a HELOC?
Some lenders charge closing costs, while others offer low fee or no fee options.
How long does HELOC approval take?
Approval timelines vary but often range from a few days to several weeks.
Conclusion
HELOC rates in 2026 continue to offer homeowners a flexible way to access the value built up in their properties. Whether you are planning renovations, consolidating debt, or preparing for major expenses, a Home Equity Line of Credit can provide convenient access to funds at competitive rates.
Before applying, compare multiple lenders, review fees carefully, and understand how variable rates may affect future payments. Taking time to research your options can help you secure the best HELOC rates and make the most of your home’s equity.






