
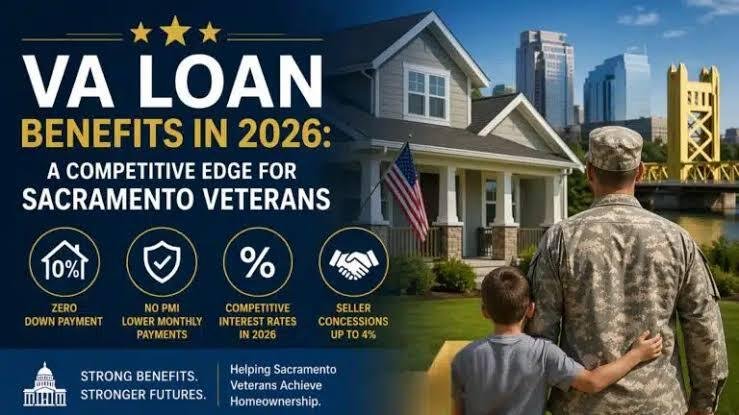
Discover VA Loan Requirements 2026, eligibility rules, benefits, credit score needs, and application steps to help veterans buy a home today.
VA Loan Requirements 2026: Eligibility & Benefits
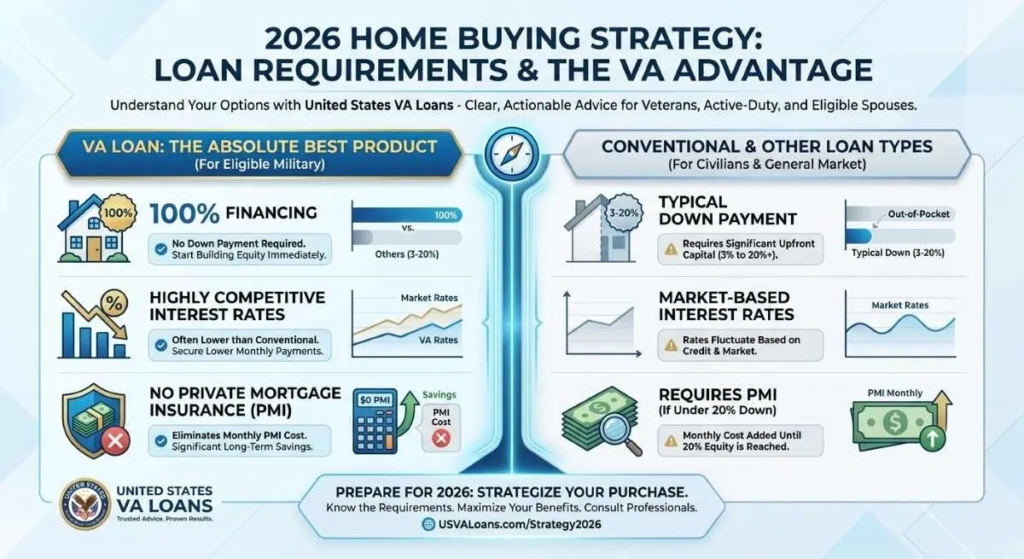
Buying a home is a major financial goal, and for veterans, active service members, and eligible surviving spouses, a VA loan can make homeownership easier and more affordable. The VA Loan Requirements 2026 help qualified borrowers access flexible mortgage options with valuable benefits such as no down payment, competitive interest rates, and no private mortgage insurance.
Understanding the latest VA home loan rules is important before starting your application. This guide explains who qualifies, what lenders look for, how the process works, and why VA loans remain one of the best mortgage choices available.
What Is a VA Loan?
A VA loan is a mortgage program supported by the Department of Veterans Affairs. It was created to help eligible military members and their families purchase homes with better financing opportunities.
Unlike many conventional home loans, VA loans are designed to reduce financial barriers for veterans. Qualified borrowers may not need a down payment, and they can often receive better loan terms compared to other mortgage programs.
VA loans can be used for:
- Buying a new home
- Building a home
- Improving a property
- Refinancing an existing mortgage
VA Loan Eligibility Requirements 2026
The first step in applying is making sure you meet the basic eligibility rules. The VA determines eligibility based on military service history and other factors.
Veterans
Veterans may qualify if they completed the required service period and received a qualifying discharge. The length of service needed can vary depending on when and how the service was completed.
Active Service Members
Current military members may qualify for VA home loan benefits if they meet service requirements. Many active service members use VA loans to purchase their first home while still serving.
National Guard and Reserve Members
Members of the National Guard and Reserve may also qualify. Eligibility depends on service time, duty status, and other VA guidelines.
Surviving Spouses
Some surviving spouses of veterans may qualify for VA loan benefits. The rules depend on specific circumstances related to the veteran’s service.
Certificate of Eligibility for VA Loans
A Certificate of Eligibility, commonly known as a COE, is one of the most important parts of the VA loan process.
The COE confirms that you have earned VA loan benefits through military service. Without this document, lenders cannot verify your eligibility.
You can request your COE through:
- A VA approved lender
- The VA online system
- A mailed application
Many lenders can help borrowers obtain the COE during the loan process.
VA Loan Credit Score Requirements 2026
One common question is whether VA loans require a specific credit score. The VA itself does not set a minimum credit score requirement.
However, lenders review your credit history to determine your ability to repay the loan. Many lenders prefer borrowers with credit scores around 580 to 620 or higher.
A stronger credit profile may help you receive:
- Lower interest rates
- Better loan terms
- Faster approval
Before applying, it is helpful to check your credit report and correct any errors.
Income and Employment Requirements
VA lenders want to make sure you can comfortably manage your monthly mortgage payments.
Stable Income
Applicants usually need proof of reliable income. This may include:
- Employment income
- Military pay
- Retirement income
- Other approved income sources
Debt to Income Ratio
Lenders review your debt compared to your monthly income. A lower debt to income ratio can improve your chances of approval.
Common debts reviewed include:
- Car payments
- Credit card balances
- Student loans
- Existing mortgages
Residual Income
VA loans also consider residual income. This means the money you have left after paying your major expenses.
This requirement helps ensure borrowers have enough money for daily living costs after buying a home.
VA Property Requirements 2026
The home you purchase must meet VA property standards. These rules protect borrowers by ensuring the home is safe and suitable.
A VA approved property must usually meet:
- Safety standards
- Structural requirements
- Basic living conditions
Eligible properties may include:
- Single family homes
- VA approved condominiums
- Certain multi unit properties
- New construction homes
The property must generally be used as your primary residence.
Major Benefits of VA Loans in 2026
VA loans offer several advantages that make them attractive for eligible borrowers.
No Down Payment Option
One of the biggest benefits is the ability to buy a home without a traditional down payment. This allows veterans to become homeowners without saving a large amount of money upfront.
No Private Mortgage Insurance
Most conventional loans require private mortgage insurance when the down payment is small. VA loans usually do not require this extra cost.
This can reduce monthly mortgage expenses.
Competitive Interest Rates
VA loans often provide competitive interest rates because they are backed by the federal government. Lower rates can help borrowers save money over the life of the loan.
Flexible Qualification Rules
VA loans may have more flexible requirements than traditional mortgages. This makes them helpful for borrowers who may not qualify for some other loan programs.
Lower Closing Costs
The VA limits certain fees that lenders can charge. This helps reduce the total cost of purchasing a home.
How to Apply for a VA Loan in 2026
Applying for a VA home loan involves several steps.
Step 1: Confirm Eligibility
Check your military service eligibility and request your Certificate of Eligibility.
Step 2: Review Your Finances
Look at your income, credit score, savings, and current debts.
Step 3: Compare VA Lenders
Different lenders may offer different interest rates and terms. Comparing options can help you find a better deal.
Step 4: Get Preapproved
Preapproval helps you understand how much home you can afford.
Step 5: Choose a Property
Find a home that fits your budget and meets VA requirements.
Step 6: Complete the Loan Process
Your lender will review documents, order an appraisal, and complete final approval.
Step 7: Close Your Loan
After approval, you will sign the paperwork and officially become a homeowner.
Tips to Improve VA Loan Approval Chances
Before applying, consider these helpful steps:
- Pay down unnecessary debt
- Keep credit card balances low
- Avoid major financial changes
- Prepare income documents
- Save money for possible closing expenses
Being financially prepared can make the process smoother.
Common VA Loan Mistakes to Avoid
Many borrowers make simple mistakes that slow down approval.
Not Checking Eligibility Early
Confirming eligibility before house hunting saves time.
Ignoring Credit Problems
Fixing credit issues before applying may improve your loan options.
Choosing the First Lender
Comparing lenders can help you find better rates and service.
Making Large Purchases
Avoid taking on new debt before closing your loan.
Conclusion
The VA Loan Requirements 2026 provide valuable opportunities for veterans, active service members, and eligible families looking to buy a home. With benefits like no down payment, no private mortgage insurance, and flexible qualification rules, VA loans continue to be a powerful home financing option.
If you qualify, take time to understand your benefits, compare lenders, and prepare your finances. A VA loan could help turn your homeownership goals into reality.
Frequently Asked Questions
What are the VA Loan Requirements 2026?
VA loan requirements include eligible military service, a Certificate of Eligibility, stable income, acceptable credit history, and an approved property.
Do VA loans require a down payment?
No. Many eligible borrowers can purchase a home with no down payment.
What credit score is needed for a VA loan?
The VA does not require a specific score, but many lenders prefer scores between 580 and 620 or higher.
Can I use a VA loan more than once?
Yes. Eligible borrowers may be able to reuse their VA loan benefits.
Do VA loans have closing costs?
Yes, but the VA limits certain fees to help reduce borrower expenses.
Can I refinance using a VA loan?
Yes. Eligible homeowners can use VA refinance programs.
Are VA loans only for first time buyers?
No. VA loans are available for eligible borrowers whether they are buying their first home or another property.
How long does VA loan approval take?
The timeline depends on the lender, documents, appraisal, and borrower situation.






