Most home buyers in 2026 face the same problem. Rates are much higher than they were a few years ago, and a new mortgage can add hundreds of dollars to the monthly payment. But there is another option many buyers never hear about. When you assume a mortgage, you take over the seller’s existing home loan, including its interest rate, its remaining balance, and its remaining term. If the seller locked in a 3 percent rate in 2021, you could keep paying that same low rate instead of borrowing at today’s rates.
Not every loan can be assumed, and you still need to qualify with the lender. But for the right buyer, an assumption can save tens of thousands of dollars. This guide explains which loans are assumable, how the process works, what it costs, and the mistakes to avoid.
What Does It Mean to Assume a Mortgage?
To assume a mortgage means the buyer steps into the seller’s place on an existing loan. The loan is not paid off at closing. Instead, the lender agrees to transfer it to the buyer, who continues making the same monthly payments under the same terms. The interest rate, the remaining balance, and the payoff date all stay the same.
This is very different from getting a new mortgage. With a new loan you apply from scratch at current market rates and start a brand new term. With an assumption you inherit the loan as it stands, and you only owe what is left. The key point is that the lender must approve the transfer. You cannot simply agree with the seller in private. The loan servicer has to review your credit, your income, and your debts, and then formally approve you as the new borrower.
Which Mortgages Are Assumable in 2026?
Whether you can assume a mortgage depends on the type of loan the seller has. FHA loans are assumable. This is one of the best known features of FHA financing. The lender must approve the buyer first, and the buyer has to meet FHA credit and income requirements. Our FHA loan guide explains the requirements in detail: https://mortgageguiderhub.com/fha-loan-guide/
VA loans are assumable too, with lender approval, and a VA loan can even be assumed by a buyer who is not a veteran. If the buyer is also an eligible veteran, they can substitute their own entitlement and free up the seller’s. USDA loans are assumable as well, subject to lender and USDA approval.
Conventional loans, on the other hand, are generally not assumable. Most contain a due-on-sale clause, which says the full loan balance becomes due the moment the home is sold. Fannie Mae and Freddie Mac loans almost always include this clause. A few older conventional loans and some adjustable rate mortgages can be assumed, but these are rare. The Consumer Financial Protection Bureau explains the basics of home loans and borrower rights: https://www.consumerfinance.gov/owning-a-home/
Why Assume a Mortgage? The Rate Advantage
The main reason to assume a mortgage is the interest rate. Consider a real example. A seller bought a home in 2021 with a $380,000 loan at 3.25 percent for 30 years. The monthly principal and interest payment is about $1,654. If you bought the same home today with a new loan at 7 percent, the same $380,000 balance would cost about $2,528 a month. That is a difference of roughly $874 every single month, or more than $10,000 a year. Over the remaining life of the loan, the savings can reach well over $100,000.
An assumption often comes with lower closing costs than a new mortgage, because there is no new loan origination and often no new appraisal. To see how rates shape your monthly payment, read our guide on how rates work: https://mortgageguiderhub.com/mortgage-interest-rates-explained/
The Downsides and Risks
An assumption is not free money. The biggest problem is the equity gap. When you assume a mortgage, you only take over the remaining loan balance, and you still have to pay the seller for the rest of the home’s value. Suppose the home is now worth $500,000 and the remaining balance is $350,000. You need to come up with $150,000 in cash, or find a second loan to cover the difference. A second mortgage is possible, but it adds a second monthly payment at a current market rate, which eats into your savings.
The process can also be slow. A standard purchase might close in 30 to 45 days, but an assumption can take 60 to 90 days. If the loan is an FHA loan, the monthly mortgage insurance premium continues and the buyer pays it. If it is a VA loan, the seller’s entitlement may stay tied up, which matters if the seller wants to use a VA loan on their next home.
How to Assume a Mortgage: Step by Step
First, confirm the loan is assumable. Ask the seller or the listing agent for the loan type and the loan documents. FHA, VA, and USDA loans are generally assumable, while most conventional loans are not. The loan agreement itself is what matters, and the servicer can confirm it.
Second, talk to the loan servicer early. The servicer is the company the seller sends payments to, and it handles the assumption. Ask for their assumption packet and requirements. Each servicer has its own forms and timeline, so getting this information early saves weeks later.
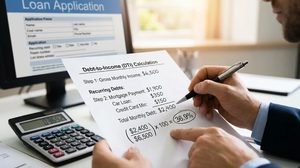
Third, apply as the new borrower. You will provide pay stubs, tax returns, bank statements, and permission for a credit check, just like a normal mortgage application. The lender will check your credit score, your income, and your debt to income ratio.
Fourth, get approved and review the terms. The lender will confirm the remaining balance, the interest rate, the monthly payment, and the remaining term. Make sure you understand whether mortgage insurance applies and what the monthly payment will actually be.
Fifth, arrange the money for the equity gap. Work out exactly how much cash you need beyond the loan balance, and where it will come from. If you need a second mortgage, apply for it at the same time, because the first lender will want to see the full picture of your debts.
Sixth, close the transaction. The assumption closes much like a normal home purchase. You will sign documents, pay the assumption fee and other closing costs, and the loan will be transferred into your name. For a realistic picture of what closing can cost, see our guide: https://mortgageguiderhub.com/closing-costs-when-buying-a-home/
Seventh, confirm the transfer is complete. After closing, check that the servicer has your name on the account and that the seller has been released from liability if that was part of the deal. Get this confirmation in writing and keep it with your loan documents.
What Does It Cost to Assume a Mortgage?
An assumption is usually cheaper than a brand new mortgage, but it is not free. The main cost is the assumption fee, which the lender charges for processing the transfer. This is often around 0.5 percent to 1 percent of the remaining loan balance, though some lenders charge a flat fee of a few hundred dollars. On a $350,000 balance, a 1 percent fee would be $3,500.
You will also pay many of the normal closing costs of a home purchase: title search, title insurance, and recording fees. If you take out a second mortgage to cover the equity gap, that loan has its own fees too. The Department of Housing and Urban Development publishes information about FHA loans and buying a home: https://www.hud.gov/buying/loans
One cost buyers sometimes forget is the funding fee or mortgage insurance. On a VA assumption, the VA charges a funding fee of usually 0.5 percent of the loan balance. On an FHA assumption, the monthly mortgage insurance premium keeps running.
What Sellers Need to Know
Sellers need to protect themselves too, and the most important protection is a release of liability. When a loan is assumed, the original borrower can still be legally responsible for the debt unless the lender formally releases them. If the buyer stops paying a year later, the lender could come after the seller. Always ask the servicer for a written release of liability as part of the assumption.
Sellers should also think about their VA entitlement. A veteran who lets a civilian assume their VA loan may find their entitlement tied up until that loan is paid off, which can block them from using a VA loan on their next home. If the buyer is another eligible veteran who substitutes their own entitlement, the problem goes away. On the positive side, an assumable low rate loan can make a home much easier to sell. The Department of Veterans Affairs explains VA loan assumption rules: https://www.va.gov/housing-assistance/
Assumption vs a New Mortgage: Which Is Better?
The right choice depends on the numbers in your specific deal. An assumption wins when the rate gap is large and the equity gap is small. If the seller’s rate is 3 percent, current rates are 7 percent, and you only need $40,000 in cash beyond the loan, the assumption is almost certainly the better deal.
A new mortgage wins when the equity gap is huge, or when you need cash for repairs, or when the old loan has a short remaining term with payments you cannot afford. A new loan also gives you a fresh choice of loan type, term, and lender. Do the math both ways before you decide.
Tips to Make an Assumption Work
Start the process early, because servicers move slowly and you do not want to lose the home over a missed deadline. Put a longer closing timeline in your purchase contract, 60 to 90 days if the seller will agree, and include a financing contingency that protects your deposit if the assumption is denied.
Get prequalified before you make an offer, so you know you can pass the lender’s review. Keep your finances steady while the assumption is being processed. Do not open new credit cards, change jobs, or make large purchases, because the lender may check your credit again before closing.
Conclusion
To assume a mortgage in 2026 is one of the smartest ways to buy a home when rates are high, but only when the numbers work. A low rate inherited from the seller can save you hundreds of dollars a month and tens of thousands over the life of the loan. The catch is the equity gap, the slow process, and the need to qualify with the lender on your own merits. If you find a home with an assumable FHA, VA, or USDA loan, and you have the cash to cover the difference, it is well worth pursuing.
FAQs
Can you assume a mortgage in 2026?
Yes, if the loan is an FHA, VA, or USDA loan and the lender approves you as the new borrower. Most conventional loans cannot be assumed because of the due-on-sale clause.
Which loans are assumable?
FHA, VA, and USDA loans are generally assumable with lender approval. Most conventional loans are not, though a few older loans and some adjustable rate mortgages may be.
Do I need good credit to assume a mortgage?
Yes. The lender checks your credit, income, and debts just like a new mortgage application. You must qualify on your own.
How much does it cost to assume a mortgage?
Expect an assumption fee of about 0.5 to 1 percent of the loan balance, plus normal closing costs such as title and recording fees.
How long does a mortgage assumption take?
Usually 60 to 90 days, which is longer than a standard purchase. Delays are common, so plan for extra time.
What is the equity gap in a mortgage assumption?
It is the difference between the home’s price and the remaining loan balance. You must pay it in cash or with a second loan.
Can a civilian assume a VA loan?
Yes, with lender approval. But the seller’s VA entitlement usually stays tied to the loan until it is paid off, unless the buyer is a veteran who substitutes their own entitlement.
Does the seller stay liable after an assumption?
They can, unless the lender gives a written release of liability. Sellers should always ask for this release before closing.
Is mortgage insurance still charged on an assumed FHA loan?
Yes. The monthly mortgage insurance premium continues, and the new borrower pays it.
Can you assume a mortgage with a low credit score?
It is harder. FHA assumptions are more flexible than most, but you still need to meet the lender’s minimum credit and income standards.
Do I need a down payment to assume a mortgage?
There is no traditional down payment, but you need cash for the equity gap plus closing costs, which often adds up to a large amount.
Can I get a second mortgage to cover the equity gap?
Yes, many buyers do. But the second loan has a current market rate and its own monthly payment, which reduces your savings.
Is an assumable mortgage better than a new mortgage?
It usually is when the old rate is much lower than current rates and the equity gap is small. Run the numbers both ways before deciding.
What happens if the lender denies my assumption?
The deal falls through unless you can get a new mortgage instead. A financing contingency in your contract protects your deposit in that case.
Do I need an appraisal to assume a mortgage?
Sometimes. Some lenders require one and some do not. Ask the servicer early so you know what to expect.