If you run your own business, you already know the tax return problem: your accountant writes off what the law allows, your taxable income shrinks, and a lender looks at that smaller number and says you cannot afford the house you clearly can afford. That is the exact gap bank statement loans self-employed borrowers turn to.
It does not ask for W-2s or two years of tax returns. It asks for your bank statements, usually 12 or 24 months of them, and qualifies you on the money that actually landed in your accounts.
What Is a Bank Statement Loan?
A bank statement loan is a type of non-QM mortgage, outside the federal qualified mortgage rules. It is still a real mortgage with full underwriting, a credit check, an appraisal, and a legal duty on the lender to check that you can repay it. The only difference is how income is proven: the lender reviews your bank deposits, not your tax returns.
A borrower might bring in $180,000 a year in client payments, then deduct business costs and end up with a taxable income of $70,000. A conventional lender works from that $70,000 and approves a far smaller loan than needed, while a bank statement lender sees the $180,000 flowing in.
These are not the old stated income loans from before the 2008 housing crisis, which verified nothing. A bank statement loan verifies everything, just from different documents, and the ability-to-repay rule still applies. Loan amounts commonly run up to $3 million.
Bank Statement Loans Self-Employed: How They Work
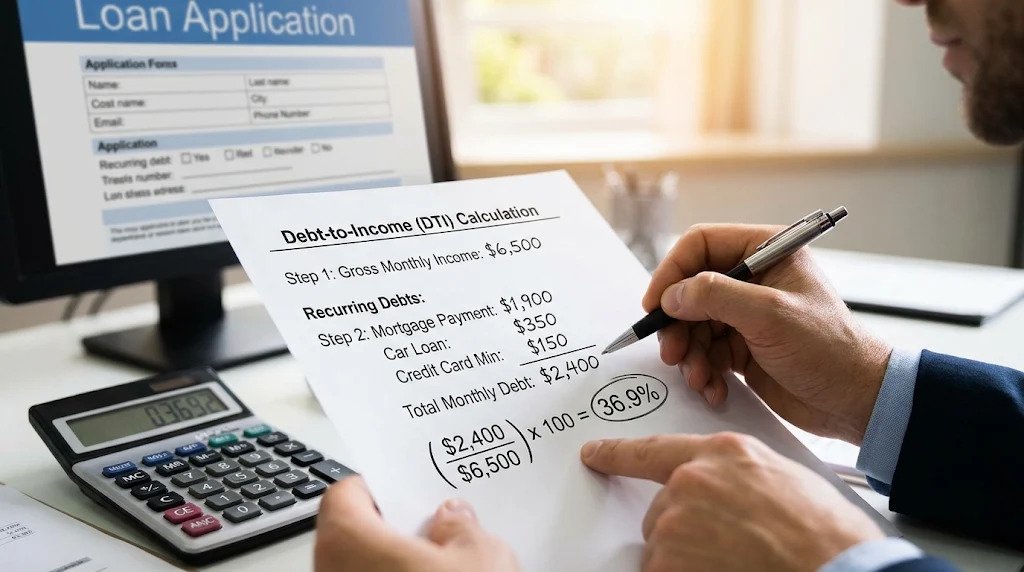
The lender adds up your eligible deposits over 12 or 24 months, removes deposits that are not real income, applies an expense factor, and divides by the number of months. The result is your monthly qualifying income.
How Lenders Calculate Your Income From Bank Deposits
Not every deposit counts. The lender strips out transfers between your own accounts, loan proceeds, refunds, gifts, one-time sales, and anything it cannot identify as business revenue.
Then comes the expense factor. Money in a business account is gross revenue, not profit, so the lender applies a flat factor to approximate running costs. The standard factor is 50 percent, meaning half of eligible business deposits count as income. Some lenders use up to 70 percent for high-cost industries, while others accept 10 to 50 percent if your CPA states your actual expense ratio in a letter.
Personal statements work differently: the money has usually already passed through the business, so most programs count close to all of it. Ownership matters too: own 60 percent of the business and the lender counts 60 percent of the income, and most programs require at least 25 percent ownership, the same line Fannie Mae uses to define a self-employed borrower. Fannie Mae’s Form 1084 shows how the conventional side does this from tax returns.
Take a consultant whose business account took in $360,000 over 12 months, or $30,000 a month. At the standard 50 percent factor, the qualifying income is $15,000 a month. With a CPA letter showing a 35 percent expense ratio, the same deposits qualify at $19,500 a month instead.
Who Bank Statement Loans Suit Best
Self-employed owners are the obvious group: if your tax returns understate what you earn, this loan closes the gap between your real cash flow and your paper income. Freelancers and gig workers fit too, since their income is spread across platforms and 1099s arrive late. Seasonal earners benefit as well: a landscaper who earns most of the year’s money between March and October looks weak on a tax return and strong on a 24-month deposit average.
Bank Statement Loan Requirements in 2026
Requirements vary by lender, since no government agency sets the rules for these loans. The typical ranges across lender programs published in 2026 are:
| Requirement | Typical bank statement loan range, 2026 |
|---|---|
| Bank statements | 12 or 24 consecutive months, personal or business |
| Self-employment history | 2 years; some accept 1 year |
| Minimum credit score | 620 to 660 floor; 680+ better; 720+ best |
| Down payment, primary home | 10% at 680+ credit; 15% to 20% otherwise; second home 15% to 20%; investment 20% to 25% |
| Cash reserves after closing | 3 to 6 months typical; up to 12 months |
| Debt-to-income ratio | 43% to 50%; up to 55% at some programs |
Your credit score does more work here than in a conventional loan. A score of 620 gets you in the door, but 680 or higher brings reasonable terms, and 720 or above brings the lowest down payment and best rate.
Reserves are the cash you still have after closing, measured in months of mortgage payments: three to six months is typical, though larger loans can require up to 12 months. This money is not spent; it just has to be there. Your debt-to-income ratio is the other gate, with most programs capping it between 43 and 50 percent. That payment includes principal, interest, taxes, and insurance, the four parts known as PITI.
Bank Statement Loans vs Conventional Loans
A conventional loan is cheaper if your tax returns support the income you need. A bank statement loan costs more, but it exists for the borrower the conventional system turns away.
| Factor | Bank statement loan | Conventional loan |
|---|---|---|
| Income proof | 12 to 24 months of bank deposits, minus an expense factor | Two years of tax returns plus a cash flow analysis |
| Who it fits | Self-employed, freelancers, gig workers | Salaried borrowers and self-employed with clean tax returns |
| Minimum down payment, primary home | 10% | 3% to 5% (3% for first-time buyers and HomeReady) |
| Mortgage insurance | Usually none, even below 20% down | Required above 80% loan-to-value |
The no-mortgage-insurance point is a genuine advantage: a conventional borrower with less than 20 percent down pays private mortgage insurance every month until there is enough equity to drop it, while most bank statement programs skip it entirely. Borrowers who qualify both ways should compare a low down payment conventional option such as HomeReady or Home Possible against a bank statement loan first.
Costs and Rates: What You Will Pay
Rates typically run 0.5 to 1.5 percent above a comparable conventional rate, because Fannie Mae and Freddie Mac do not buy these loans. The premium is smaller for strong profiles with high scores and large down payments.
Fees look familiar: an origination or lender fee, an appraisal, title and escrow charges, and the usual closing costs. Prepayment penalties appear in some programs, often for the first one to three years, so ask directly whether your loan has one. A 60-day rate lock also costs more than a 30-day lock.
How to Apply for a Bank Statement Loan

First, get prequalified. A loan officer reviews your statements informally, runs the deposit math, and tells you roughly what you can borrow. Bring all 12 or 24 months, not just the good months.
Second, gather your documents: 12 or 24 months of complete bank statements with no gaps, a business license or CPA letter proving at least two years of self-employment, a profit and loss statement, and a CPA letter confirming your taxes are filed. For a lower expense factor than 50 percent, the CPA letter stating your actual expense ratio is the document that makes it happen.
Third, submit the application and let underwriting run. The underwriter will go through your statements line by line and ask for paper trails for large or unusual deposits. Answer fast and with documents: a gift deposit needs a gift letter, and a transfer from savings needs the matching withdrawal statement.
Fourth, get the appraisal, clear conditions, and close.
Risks and Who Should Avoid a Bank Statement Loan
The rate premium adds up: an extra 1 percent on a $400,000 loan is roughly $260 a month. If your tax returns will look better in a year or two, it may be cheaper to wait, or to take this loan now and refinance later. That only works if rates cooperate and your returns improve, so do not count on it. If a refinance is part of your plan, learn how a rate-and-term refinance works first.
Deposit dips can shrink your approval, because the lender averages your deposits. There is also a temptation risk: some borrowers route personal money through the business account to inflate deposits. Do not do this. Underwriters spot circular transfers, and misrepresenting your finances on a mortgage application is fraud.
Who should avoid this loan? If your tax returns already show enough income, take a conventional loan. If your credit score is below 620, work on the score first. If your business is brand new, most lenders will ask you to wait. And if your deposits are erratic, with unexplained swings or frequent overdrafts, fix the banking habits first.
Tips to Strengthen Your Application
Keep your business and personal accounts separate, and stop moving money between them without a clear paper trail. Build your reserves early, and do not move large sums around in the month before you apply. Get the CPA letter before you apply. Finally, shop more than one lender: programs differ widely, so compare guides such as Griffin Funding and JVM Lending before you choose.
Frequently Asked Questions
What is a bank statement loan?
A non-QM mortgage that qualifies you on 12 or 24 months of bank deposits instead of tax returns. The lender averages eligible deposits, applies an expense factor, and uses the result as monthly qualifying income.
Who qualifies for a bank statement loan?
Self-employed borrowers, freelancers, gig workers, and 1099 contractors whose tax returns understate real earnings. Most lenders want two years in business, though some accept one year at a higher rate.
How do lenders calculate income on a bank statement loan?
They total eligible deposits over 12 or 24 months, remove transfers, loan proceeds, and gifts, apply an expense factor, usually 50 percent, then divide by the number of months.
What is the expense factor on a bank statement loan?
The share of business deposits treated as expenses, not income. The default is 50 percent, though some use up to 70 percent, and a CPA letter can support a lower factor.
What credit score do I need for a bank statement loan?
Most lenders set the minimum at 620 to 660. A score of 680 or higher gets better pricing, and 720 or above unlocks the lowest down payment and best rates.
How much down payment does a bank statement loan need?
Usually 10 percent on a primary home with a score of 680 or higher, and 15 to 20 percent with a lower score. Second homes need 15 to 20 percent; investment properties need 20 to 25 percent.
Do bank statement loans require mortgage insurance?
Most programs do not require it, even with less than 20 percent down, unlike conventional loans above 80 percent loan-to-value.
How much higher are bank statement loan rates?
Typically 0.5 to 1.5 percent above a comparable conventional rate. Strong profiles with high scores and large down payments get the smallest premium.
Can I refinance a bank statement loan into a conventional loan later?
Yes, many borrowers do that once their tax returns show enough income, often after one or two years. Watch for a prepayment penalty, and do not assume rates will be lower.
Are bank statement loans the same as no-doc loans?
No. No-doc loans verified nothing and are effectively gone since the ability-to-repay rules took effect in 2014. A bank statement loan verifies income from bank deposits instead.