
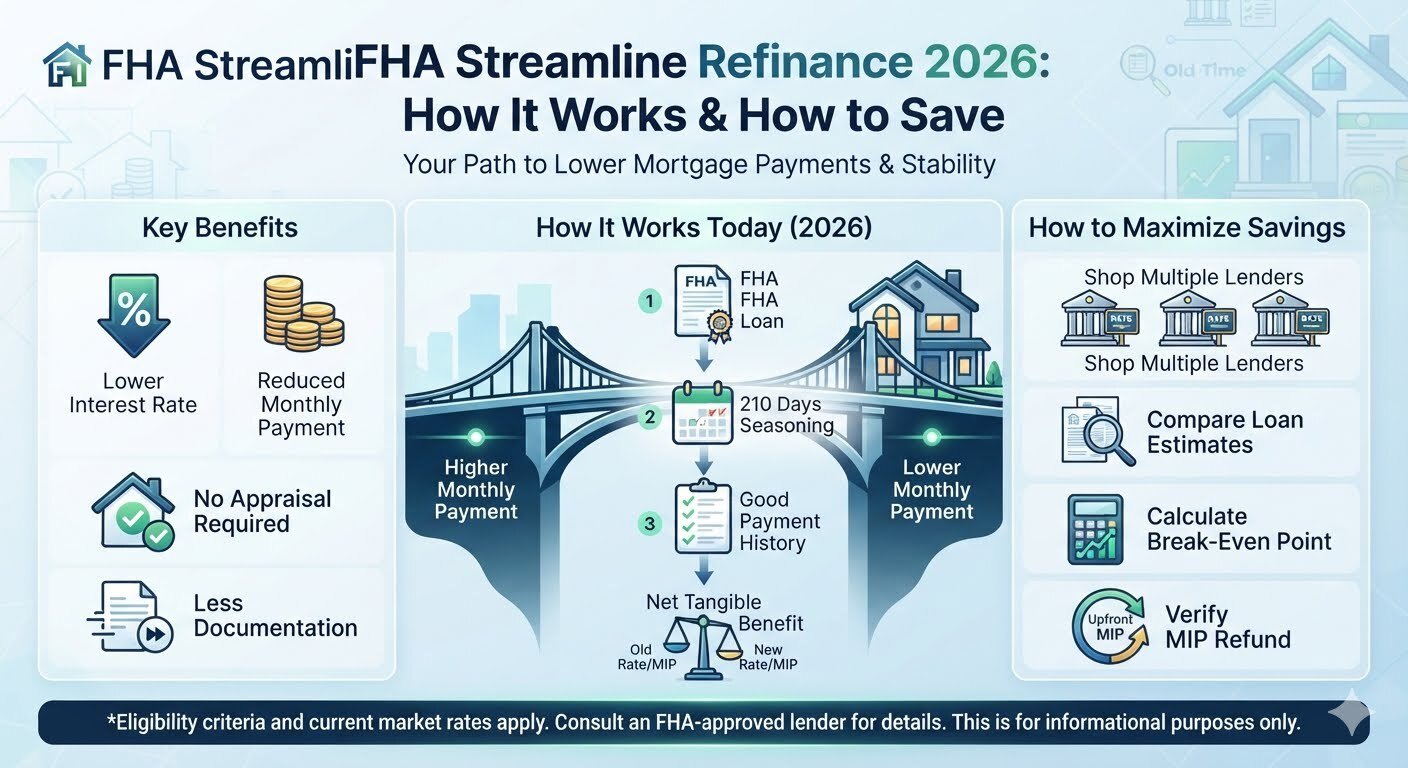
Learn how FHA Streamline Refinance works in 2026. Discover eligibility, benefits, requirements, costs, and steps to lower your monthly mortgage payment.
FHA Streamline Refinance 2026: How It Works
If you already have an FHA loan, refinancing could help you lower your monthly mortgage payment or reduce your interest rate. One of the easiest ways to refinance an existing FHA loan is through the FHA Streamline Refinance program.
This refinance option was created to simplify the process for homeowners who already have an FHA insured mortgage. In many cases, there is less paperwork, faster approval, and fewer qualification requirements than with a traditional refinance.
In this guide, you will learn how FHA Streamline Refinance works in 2026, who qualifies, its benefits, possible costs, and how to decide if it is the right choice for you.
What Is FHA Streamline Refinance?
FHA Streamline Refinance is a refinancing program for homeowners who already have an FHA insured mortgage. It allows eligible borrowers to refinance into a new FHA loan with less documentation than a standard refinance.
The purpose of this program is to help homeowners reduce their mortgage costs while making the refinancing process easier and faster.
How Does FHA Streamline Refinance Work?
Unlike many refinance programs, FHA Streamline Refinance does not usually require a full income verification or a new home appraisal in many situations.
Instead, lenders focus on your current FHA loan and determine whether refinancing provides a financial benefit.
The basic process includes:
Review Your Current FHA Loan
Confirm that your current mortgage is an FHA loan and that it meets lender requirements.
Compare Mortgage Rates
Speak with several lenders to compare available interest rates and estimated monthly payments.
Submit Your Application
Complete a refinance application and provide any required documents requested by the lender.
Loan Review
The lender reviews your eligibility and confirms that the refinance creates a clear financial benefit.
Close the Loan
After approval, you sign the final documents and your new FHA mortgage replaces the previous loan.
FHA Streamline Refinance Eligibility
Although lender requirements may vary, borrowers generally must meet several common guidelines.
Existing FHA Loan
The mortgage being refinanced must already be an FHA insured loan.
Payment History
Lenders generally expect borrowers to have a good payment history with few or no recent late payments.
Financial Benefit
The refinance should provide a meaningful financial benefit, such as a lower interest rate or reduced monthly payment.
Occupancy Rules
Some lenders may have occupancy requirements depending on when your original FHA loan was obtained.
Benefits of FHA Streamline Refinance
Many homeowners choose this program because of its convenience and potential savings.
Some advantages include:
- Faster approval process
- Less paperwork
- Competitive mortgage rates
- Lower monthly mortgage payments
- No full income verification in many cases
- Home appraisal may not be required in certain situations
- Easier qualification than many traditional refinance programs
Possible Costs to Consider
Even though the process is simpler, refinancing still involves costs.
These may include:
- Closing costs
- Lender fees
- FHA mortgage insurance premiums
- Recording fees
- Interest charges
Before refinancing, compare your total savings with the costs involved.
When Should You Consider FHA Streamline Refinance?
Refinancing may be a smart choice if:
Interest Rates Have Dropped
Lower rates may reduce your monthly payment and total interest over time.
You Want Lower Monthly Payments
Reducing your monthly payment can improve your household budget.
You Plan to Stay in Your Home
The longer you stay in your home, the more likely you are to recover your refinancing costs through monthly savings.
When FHA Streamline Refinance May Not Be the Best Choice
Refinancing is not always the right decision.
You may want to wait if:
- Current mortgage rates are similar to your existing rate.
- Closing costs outweigh potential savings.
- You plan to sell your home soon.
- Your financial goals have changed.
Documents You May Need
Although documentation is often reduced, lenders may still request:
Personal Identification
Government issued identification.
Mortgage Information
Information about your current FHA mortgage.
Income Information
Some lenders may request limited income documents depending on the loan.
Property Information
Basic details about your home and mortgage.
Tips for Getting the Best FHA Streamline Refinance
Compare Multiple Lenders
Different lenders may offer different interest rates and fees.
Review Closing Costs
Do not focus only on the interest rate. Review the total cost of refinancing.
Improve Your Credit
Although FHA loans offer flexible credit guidelines, stronger credit may help you qualify for better loan terms.
Ask Questions
Understand every fee, payment, and loan term before signing your refinance documents.
Conclusion
FHA Streamline Refinance continues to be one of the simplest ways for eligible homeowners to lower their mortgage payments in 2026. With reduced paperwork, faster processing, and competitive mortgage rates, it can provide valuable savings for borrowers who already have an FHA loan.
Before refinancing, compare several lenders, review all loan costs, and calculate your long term savings. A little research today can help you make a confident financial decision that benefits you for years to come.
Frequently Asked Questions
What is FHA Streamline Refinance?
It is a refinance program designed for homeowners who already have an FHA insured mortgage and want to lower their mortgage costs.
Do I need a new home appraisal?
Many FHA Streamline Refinance loans do not require a new appraisal, although lender requirements can vary.
Can I refinance if I have late payments?
Lenders usually review your recent payment history. A strong payment record improves your chances of approval.
Will refinancing lower my monthly payment?
It may lower your payment if you qualify for a lower interest rate or better loan terms.
Can I refinance with a different lender?
Yes. Many homeowners compare several lenders to find better rates and lower fees.
Does FHA Streamline Refinance require income verification?
Many loans require less income documentation than a traditional refinance, although lender requirements may differ.
How long does the refinance process take?
The timeline depends on the lender, but many FHA Streamline Refinance loans close faster than standard refinance loans.






