Biweekly Mortgage Payments: Do They Really Save You Money?
Biweekly mortgage payments sound like a small scheduling trick. Instead of paying your mortgage once a month, you pay half of it every two weeks. The amount per paycheck feels smaller, the timing lines up nicely if you are paid every two weeks, and the pitch is tempting: pay off your home years early and save tens of thousands in interest.
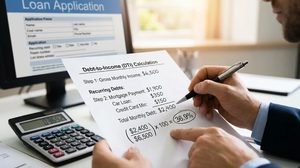
Do they really save you money? Yes, but not for the reason most ads suggest. The saving does not come from magic or from paying every two weeks instead of every month. It comes from simple calendar math. There are 52 weeks in a year, so paying every two weeks means you make 26 half payments. That equals 13 full monthly payments a year instead of 12. That one extra payment a year goes straight to principal, and over 20 or 30 years, that adds up to real money.
The key question is not whether biweekly payments work. The math does work. The key question is whether you should pay a company to set it up for you, whether your servicer will apply the money the way you expect, and whether there is a free way to get the exact same result. For most homeowners, there is.
How Do Biweekly Mortgage Payments Work?
Take your normal monthly principal and interest payment and cut it in half. Pay that half amount every two weeks instead of paying the full amount once a month. That is the whole system.
Because a year has 52 weeks, you will make 26 half payments. Two half payments equal one full payment, so 26 halves equal 13 full payments. A normal monthly schedule gives you only 12 full payments a year. The difference is one extra full payment every year, without you ever having to find a large lump sum at once.
That extra payment is powerful because it goes to principal. On a normal payment, part goes to interest and part goes to principal. On that 13th payment, almost all of it cuts your balance directly. A lower balance means less interest charged the next month, and less interest the month after that. The effect compounds quietly, year after year.
Here is a simple example. If your monthly principal and interest payment is $2,000, your biweekly payment is $1,000 every two weeks. Over a year, you pay $26,000 instead of $24,000. That extra $2,000 is the one extra payment. You never wrote a $2,000 check at once, you just paid $1,000 a little more often.
Do not confuse biweekly with semimonthly. Semimonthly means twice a month, on fixed dates like the 1st and 15th. That is only 24 half payments a year, which equals 12 full payments. There is no extra payment, and no extra saving. Biweekly means every two weeks, which is 26 payments, and that is where the benefit comes from.
A Worked Example With a $400,000 Loan
Let us use a realistic example so you can see the actual dollars. All rates here are examples for illustration, and your servicer may apply payments on a slightly different timetable.
Suppose you borrow $400,000 on a 30 year fixed loan at an example rate of 6.5 percent. Your monthly principal and interest payment would be about $2,528. Your biweekly payment would be half of that, about $1,264 every two weeks.
On a monthly schedule, you pay $30,336 a year, which is 12 times $2,528. On a biweekly schedule, you pay $32,864 a year, which is 26 times $1,264. The difference is $2,528, exactly one extra monthly payment per year.
What does that buy you? If every half payment were applied promptly to principal and interest, the loan would be paid off in about 24 years and 2 months instead of 30 years, or about 5 years and 10 months early. Total interest would fall from about $510,000 on the monthly schedule to about $395,000 on the biweekly schedule, a saving of roughly $115,000 over the life of the loan.
Those figures are approximate, because servicers differ in when they credit half payments. Some apply each half as it arrives. Others hold the money until a full payment has accumulated. That delay reduces the benefit slightly, but the core saving from the extra annual payment remains.
A second verified example shows the same pattern on a smaller loan. On a $300,000, 30 year loan at 6 percent, the monthly payment is about $1,799 and the biweekly payment is about $899. Biweekly payments pay that loan off in about 24 years and 7 months and save roughly $73,000 in interest, according to MonitorBankRates’ biweekly payment guide. The pattern is consistent: one extra payment a year cuts about five to six years off a 30 year loan.
The saving is bigger when your balance is bigger, your rate is higher, or you start early in the loan. Early in a 30 year loan, most of each payment goes to interest. Cutting principal early has the biggest effect then. If you start biweekly payments in year 20, you will still save money, but far less, because most of the interest has already been paid.
True Biweekly vs a Lender Biweekly Program
There are two ways to go biweekly, and they are not the same. The first is a true biweekly plan run by your servicer or a third party company. You authorize automatic withdrawals every two weeks, and the company forwards the money to your servicer. The second is a do it yourself version, where you simply pay extra principal each month on your own.
Many third party biweekly programs charge fees. Some charge a setup fee, some charge a monthly processing fee, and some charge both. You should be very careful here. If you pay $300 to enroll and $5 a month for 25 years, you have spent $1,800 in fees for a result you could have created for free.
Some servicers also hold your half payments in a non interest bearing suspense account until they have a full monthly amount. That means your first half payment sits idle for two weeks before it is applied. It does not destroy the saving, but it delays it. Ask your servicer in writing: do you apply each half payment when it arrives, or do you hold it until a full payment is collected?
Bankrate explains this clearly in its guide to biweekly mortgage payments, including the Bankrate example of a $410,000 home where biweekly payments save more than $33,000 in interest in the first 10 years alone. The lesson is the same: confirm how the extra money is applied to principal before you commit.
If your servicer offers a free biweekly program and applies payments promptly, it can be a good fit, especially if you are paid biweekly and want the payment to match your paychecks. If the program charges fees, or if your servicer holds funds, the do it yourself method below is usually better.
The Free Alternative That Gets the Same Result
You can get almost the exact same saving without enrolling in any program and without paying any fee. Divide your monthly payment by 12 and add that amount to each monthly payment as extra principal.
On our $400,000 example, the monthly payment is $2,528. Divide that by 12 and you get about $211 a month. Pay $2,528 plus $211, or $2,739, each month, and mark the extra $211 as principal only. Over a year, you will have paid 12 times $211, which is $2,532, or about one extra monthly payment. That is the same as the biweekly plan.
On a $300,000 loan at 6 percent, the math is $1,799 divided by 12, or about $150 extra a month. Pay $1,949 a month instead of $1,799, and you get the same one extra payment a year.
This method has three advantages. First, it is free. Second, you control it. If money is tight one month, you can skip the extra $211 and just pay the normal amount. A biweekly auto draft does not give you that flexibility. Third, the extra money is applied as principal right away, with no suspense account delay.
Another free option is to make one extra full payment a year from a bonus, tax refund, or other windfall, and mark it as principal only. That also equals the biweekly result, as long as you do it every year. The biweekly habit works mainly because it is automatic. If you are disciplined, the manual version works just as well.
For a broader payoff plan, read our guide on how to pay off your mortgage early in 2026. If you have a lump sum rather than a monthly extra, a recast may also be worth comparing, and our companion guide on how to assume a mortgage in 2026 covers another way some buyers keep a low rate.
Risks, Fees, and Downsides to Watch
Biweekly payments are not right for everyone. The first risk is cash flow. You pay more in the months with three biweekly paydays. In a normal year, there are two months with three biweekly payments instead of two. If your budget is already tight, those months can be stressful. Make sure you can handle the months with an extra half payment.
The second risk is fees. Never pay a large enrollment fee for a biweekly plan when the free method above gives the same result. If a company pressures you to sign up quickly or claims only its program can save you interest, walk away. The math is public, and you can do it yourself.
The third risk is how your servicer applies the money. If the extra payment is not marked as principal, or if it is applied to future payments or escrow instead, you lose the benefit. Always write principal only on any extra payment, and check your statement the next month to confirm the balance fell by the amount you expected.
Check for a prepayment penalty, too. Most modern mortgages in the US do not have one, but some older loans or non standard loans do. The Consumer Financial Protection Bureau notes in its Regulation Z rules that prepayment terms must be disclosed, so review your closing documents or ask your servicer directly.
Finally, remember that biweekly payments do not lower your required monthly payment. Your required payment stays the same. If your income drops, you still owe the full monthly amount, even though you have been paying extra. That is different from a recast, which does lower the required payment. If cash flow flexibility is your main goal, a recast or a refinance may fit better than biweekly payments.
Who Benefits Most, and Who Should Skip It
Biweekly payments benefit most the homeowner who is paid every two weeks, has a stable budget with a little slack, is early in a 30 year loan, and wants a set it and forget it way to pay off the home early. For that person, the automatic extra payment builds wealth quietly without requiring willpower every month.
They also help if you struggle to save a lump sum. Finding $2,500 once a year feels hard. Paying $1,264 every two weeks instead of $2,528 once a month feels easier, even though the total is higher. The psychology matters, and biweekly payments use it well.
You should probably skip biweekly payments if your budget has no slack, if you have credit card debt above 15 percent interest, or if you have no emergency fund. Pay the high interest debt first and build three to six months of expenses in savings before you send extra money to a 6 percent mortgage.
You should also skip a paid biweekly program if your servicer offers no free option. Use the free monthly add on instead. And if you plan to sell in two or three years, the interest saving will be small. You might prefer to keep that extra cash for moving costs or your next down payment.
A useful test is to ask yourself: if I pay $211 extra a month for a year, will I miss it? If the answer is no, biweekly or its free equivalent is a good fit. If the answer is yes, focus on your emergency fund first. You can always start biweekly payments later.
How to Set Up Biweekly Payments the Right Way
Start by calling your servicer. Ask three questions: do you offer a biweekly program, is there a fee, and how do you apply half payments? Get the answers in writing.
If the servicer program is free and applies payments promptly, you can enroll. Set the draft date to the day after your payday if you can, so the money is there when the draft hits. Check your first two statements carefully to confirm the timing and the principal balance.
If the program charges a fee, do it yourself instead. Set up a monthly automatic payment for your normal amount plus one twelfth extra, and add a memo or online instruction that the extra is principal only. Some servicers let you set this up online. Others require a phone call. Either way, confirm it in writing.
Whatever method you choose, review your statement every few months. Confirm that the extra money reduced your principal balance, not just your escrow or future payments. If the balance does not move as expected, call the servicer and ask for a breakdown of how the last payment was applied.
Finally, keep a simple record. Note the date you started, the extra amount per month, and your balance at the start. Once a year, compare your balance with a standard amortization schedule. You should see your balance falling faster than the schedule predicts. That is proof the plan is working.
Frequently Asked Questions
Do biweekly mortgage payments really save you money? Yes. They save money because you make 13 full payments a year instead of 12. That extra payment goes to principal, which cuts total interest and shortens the loan by about five to six years on a typical 30 year loan.
How much can I save with biweekly payments on a $400,000 loan? On a $400,000, 30 year loan at an example rate of 6.5 percent, biweekly payments could save roughly $115,000 in interest and pay the loan off in about 24 years and 2 months instead of 30 years. Exact savings depend on your rate, balance, and how your servicer applies payments.
Is biweekly the same as paying twice a month? No. Biweekly means every two weeks, or 26 half payments a year. Paying twice a month on fixed dates means only 24 half payments a year, which equals 12 full payments and gives no extra saving.
Do I need to enroll in a biweekly program? No. You can get the same result for free by dividing your monthly payment by 12 and adding that amount to each monthly payment as extra principal. That equals one extra payment a year without any program or fee.
Are there fees for biweekly mortgage payments? Some servicers offer it for free, but many third party programs charge a setup fee and a monthly fee. Avoid paying for a program when the free monthly add on gives the same result.
Will biweekly payments lower my monthly payment? No. Your required monthly payment stays the same. Biweekly payments help you pay off the loan faster, they do not reduce the amount you are required to pay each month.
Can biweekly payments hurt my credit? No, if payments are made on time. Paying more often does not hurt your score. Missing a biweekly draft because of insufficient funds, however, could lead to a late payment, so make sure the money is in the account.
What if my servicer holds half payments in suspense? Some servicers hold half payments until a full payment is collected, which delays the benefit slightly. Ask your servicer in writing how it applies half payments before you enroll.
Do biweekly payments work on a 15 year loan? Yes, but the saving is smaller in dollars and years, because a 15 year loan already pays off faster and charges less total interest. The same one extra payment a year still helps, just by less.
Can I stop biweekly payments if money gets tight? If you use the free do it yourself method, yes, you can stop the extra amount any month. If you are in a formal biweekly auto draft program, you may need to contact the servicer or company to cancel or pause it, so check the cancellation rules first.
Is there a prepayment penalty for biweekly payments? Most modern US mortgages do not have a prepayment penalty, but you should check your loan documents or ask your servicer. Never assume, especially on an older or non standard loan.
Biweekly payments or extra monthly principal, which is better? The math is almost identical. Biweekly is better if you are paid biweekly and like automation. Extra monthly principal is better if you want control, no fees, and the ability to skip a month when money is tight.