
What Is an Escrow Account? How It Works in Mortgage Loans is one of the most common questions asked by first-time homebuyers. When purchasing a home, many borrowers hear the word “escrow” during the mortgage process but do not fully understand what it means or why lenders require it.
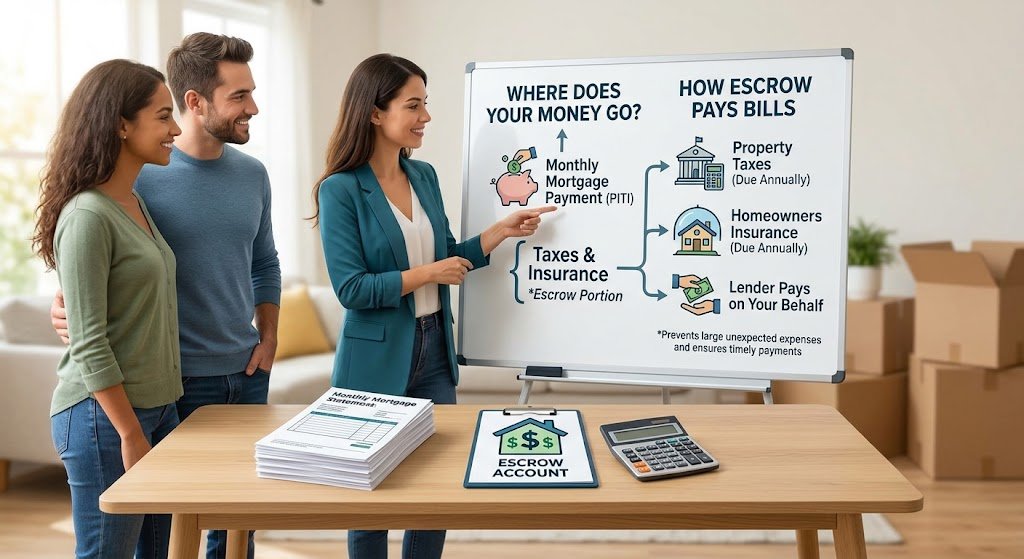
An escrow account is a special account managed by a mortgage lender or loan servicer to collect and pay important home-related expenses, mainly property taxes and homeowners insurance. Instead of paying large bills separately once or twice a year, homeowners make smaller monthly payments that are stored in the escrow account.
For many homeowners, escrow makes managing mortgage payments easier because it helps avoid unexpected expenses. However, understanding how escrow works can help you review your monthly mortgage payment, avoid shortages, and make better financial decisions.
What Is an Escrow Account? How Does It Work in Mortgage Loans?
An escrow account is a financial account created by a mortgage lender to hold money for future property expenses. The lender collects a portion of your taxes and insurance costs every month along with your mortgage payment.
The collected money is kept in the escrow account until your bills become due. Then, the mortgage servicer uses those funds to pay your property taxes and homeowners insurance on your behalf.
Simply explained:
An escrow account allows homeowners to pay yearly property expenses through smaller monthly mortgage payments instead of handling large bills separately.
For example, imagine your annual property taxes are $4,800 and your homeowners insurance costs $1,200 per year.
Your lender may divide these costs:
- Property taxes: $400 per month
- Insurance: $100 per month
Your escrow portion would be around $500 added to your monthly mortgage payment.
Instead of paying $6,000 at once, you gradually save throughout the year.
How Does a Mortgage Escrow Account Work?
A mortgage escrow account works by combining your principal, interest, taxes, and insurance into one monthly payment.
Most mortgage payments include four parts:
Principal
The principal is the amount of money you borrowed from the lender. Each payment reduces your remaining loan balance.
Interest
Interest is the cost charged by the lender for providing the mortgage loan.
Property Taxes
Local governments use property taxes to fund services such as schools, roads, and public programs.
Homeowners Insurance
Homeowners insurance protects your property against covered events like fire, storms, theft, and other damages.
Together, these costs are often called PITI:
- Principal
- Interest
- Taxes
- Insurance
Why Do Lenders Require Escrow Accounts?
Many lenders require escrow accounts because property taxes and insurance directly protect the property that secures the mortgage.
If a homeowner fails to pay property taxes, the government may place a tax lien on the property. If insurance coverage expires, the lender’s investment becomes more vulnerable.
An escrow account helps reduce these risks by ensuring important bills are paid on time.
Common Reasons Lenders Use Escrow
Protect the Property
The home is collateral for the mortgage loan. Keeping insurance active protects both the homeowner and lender.
Prevent Missed Tax Payments
Property taxes can create serious financial problems if ignored. Escrow helps prevent missed deadlines.
Make Payments Easier
Instead of saving thousands of dollars separately, homeowners can spread costs over monthly payments.
What Expenses Are Paid Through an Escrow Account?
An escrow account usually covers two major expenses:
Property Taxes
Property taxes are paid to local government authorities. The amount depends on factors such as:
- Home value
- Local tax rates
- County rules
Tax amounts can change every year, which means your escrow payment may increase or decrease.
Homeowners Insurance
Insurance protects your home from unexpected damage.
Your escrow account may pay:
- Homeowners insurance premiums
- Flood insurance (if required)
- Other property-related insurance policies
Other Possible Escrow Expenses
Depending on your mortgage agreement, escrow may also cover:
- Private mortgage insurance (PMI)
- Special assessments
- Certain homeowner association fees







