
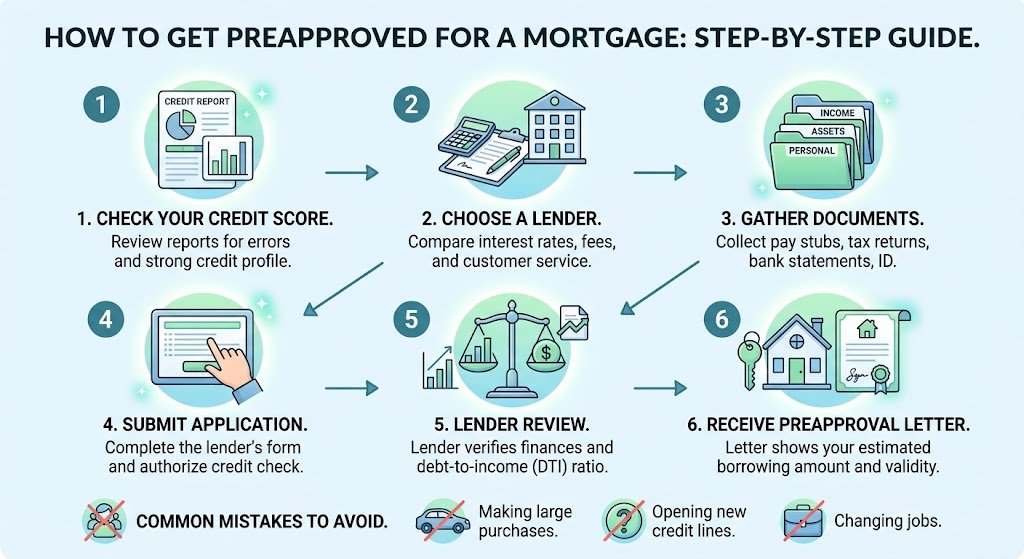
How to Get Preapproved for a Mortgage: Step-by-Step Guide is one of the first things buyers search when they are planning to purchase a home. A mortgage preapproval helps you understand how much you may be able to borrow, shows sellers that you are a serious buyer, and makes the home-buying process easier.
A mortgage preapproval is a lender’s review of your financial information to estimate the loan amount you may qualify for. Unlike a simple online calculator, preapproval requires real documentation such as income details, credit history, debts, and assets.
The process may feel complicated, especially for first-time buyers. Many people are unsure about what documents they need, how their credit score affects approval, or how long the process takes. This guide explains the complete mortgage preapproval process, what lenders look for, common mistakes to avoid, and practical steps to improve your chances.
In simple terms: To get preapproved for a mortgage, you need to choose a lender, submit financial documents, allow a credit check, and receive a preapproval letter showing your estimated borrowing amount.
What Does Mortgage Preapproval Mean?
A mortgage preapproval is a written statement from a lender showing that you may qualify for a specific home loan amount based on your current financial situation.
During preapproval, lenders review:
- Your credit score and credit history
- Income and employment stability
- Monthly debts
- Savings and assets
- Debt-to-income ratio (DTI)
- Loan type and down payment amount
A preapproval is different from prequalification. Prequalification usually uses self-reported information and provides a rough estimate. Preapproval involves deeper financial verification and carries more weight when making an offer on a home.
According to the Consumer Financial Protection Bureau, understanding your finances before applying for a mortgage can help you make better borrowing decisions.
How to Get Preapproved for a Mortgage: Step-by-Step Process
Getting mortgage preapproval does not have to be stressful. Following a clear process can help you prepare better and avoid delays.
Check Your Credit Score Before Applying
Your credit score plays an important role in mortgage approval. Lenders use your credit history to understand how you manage borrowed money.
Before applying:
- Review your credit reports
- Check for incorrect information
- Pay down high credit card balances
- Avoid opening unnecessary new accounts
Most conventional mortgage lenders prefer stronger credit profiles, but requirements vary depending on the loan program.
A higher credit score may help you qualify for better interest rates, while a lower score could limit your options or increase borrowing costs.
Choose the Right Mortgage Lender
The lender you choose can affect your experience, loan options, and costs.
You can compare:
- Banks
- Credit unions
- Online mortgage lenders
- Mortgage brokers
When comparing lenders, look at:
- Interest rates
- Loan fees
- Customer service
- Available mortgage programs
- Closing costs
Do not focus only on the lowest advertised rate. A lender with better communication and transparency may save you time and problems later.
Complete guide to choosing the right mortgage lender
Gather Required Documents
One of the biggest reasons mortgage applications get delayed is missing paperwork.
Most lenders ask for documents such as:
Income Documents
Examples include:
- Recent pay stubs
- W-2 forms
- Tax returns
- Employment verification
- Business income records (for self-employed buyers)
Asset Documents
You may need:
- Bank statements
- Investment account statements
- Retirement account records
- Gift letter documentation if receiving financial help
Personal Information
Common requirements include:
- Driver’s license or government ID
- Social Security number
- Current address history
- Rental information if applicable
Preparing these documents before applying can make the process much faster.
Submit Your Mortgage Application
After choosing a lender and preparing documents, you will complete a mortgage application.
The lender will ask about:
- Desired loan amount
- Property type
- Employment history
- Income sources
- Existing debts
- Down payment amount
The lender then reviews your information and performs a credit check.
This stage helps determine whether you qualify and how much you may be able to borrow.
Understand Your Debt-to-Income Ratio
Your debt-to-income ratio, commonly called DTI, compares your monthly debt payments with your gross monthly income.
The formula is:
Monthly Debt Payments ÷ Gross Monthly Income = DTI Ratio
For example:
- Monthly income: $7,000
- Monthly debts: $2,100
Your DTI ratio would be 30%.
Lenders use DTI to measure whether your income can comfortably support mortgage payments.
Common debts considered include:
- Car loans
- Student loans
- Credit card payments
- Personal loans
- Existing mortgages
Reducing unnecessary debt before applying may improve your mortgage approval chances.
What Documents Are Needed for Mortgage Preapproval?
Many buyers ask, “What do I need for mortgage preapproval?”
While requirements differ by lender, most applicants should prepare:
Employment Verification
Lenders want to confirm stable income.
You may provide:
- Two years of W-2 forms
- Recent paychecks
- Employer contact information
Self-employed applicants may need additional documents, including:
- Business tax returns
- Profit and loss statements
- Business bank statements
Bank Statements
Bank statements help lenders verify:
- Down payment funds
- Closing costs
- Financial reserves
Avoid unexplained large deposits because lenders may ask where the money came from.
Credit Information
Your lender will review:
- Payment history
- Credit utilization
- Existing accounts
- Recent inquiries
How Long Does Mortgage Preapproval Take?
The timeline depends on your lender and how quickly you provide documents.
Generally:
- Simple applications may take a few days
- More detailed applications may take one to two weeks
Factors that can slow down approval include:
- Missing documents
- Self-employment income verification
- Credit issues
- Multiple income sources
A useful tip from mortgage professionals is to organize your financial documents before contacting lenders. This small step can reduce unnecessary back-and-forth communication.
How Much Mortgage Can You Get Preapproved For?
A lender estimates your borrowing ability based on several factors:
Income
Higher stable income usually supports a larger loan amount.
Credit Score
Credit history affects loan eligibility and interest rates.
Existing Debt
Large monthly payments reduce borrowing capacity.
Down Payment
A larger down payment may reduce the amount you need to borrow.
Loan Program
Different mortgage programs have different requirements.
Examples include:
- Conventional loans
- FHA loans
- VA loans
- USDA loans
Remember, the amount you are approved for is not always the amount you should spend. Your personal budget, lifestyle, and future goals should also guide your decision.
Common Mortgage Preapproval Mistakes to Avoid
Many buyers make mistakes after receiving preapproval.
Making Large Purchases
Avoid buying expensive items such as:
- New vehicles
- Furniture
- Luxury purchases
Large purchases can increase your debt ratio and affect approval.
Changing Jobs During the Process
Stable employment is important. Changing jobs may require additional income verification.
Applying for New Credit
New credit cards or loans can impact your credit score and lender review.
Ignoring Interest Rates
Your preapproval amount does not lock your final mortgage rate. Rates can change before closing.

How Long Does a Mortgage Preapproval Letter Last?
Most mortgage preapproval letters are valid for around 60 to 90 days, although the exact period depends on the lender.
If your home search takes longer, you may need to update:
- Income information
- Credit review
- Employment verification
Keeping your financial situation stable during this period is important.
Tips to Improve Your Mortgage Preapproval Chances
Before applying, consider these practical steps:
Improve Your Credit Profile
- Pay bills on time
- Reduce credit card balances
- Avoid unnecessary credit applications
Save More Money
Having additional savings can help cover:
- Down payment
- Closing costs
- Emergency expenses
Keep Financial Records Organized
Create a folder containing:
- Tax documents
- Bank statements
- Income records
- Identification documents
Compare Multiple Lenders
Getting quotes from different lenders may help you understand available options.
Final Thoughts: Start Your Mortgage Preapproval Journey
Learning how to get preapproved for a mortgage is an important step before buying a home. A preapproval letter gives you a clearer picture of your budget and helps you approach sellers with confidence.
The process becomes much easier when you prepare your credit, organize documents, compare lenders, and understand what lenders evaluate.
Whether you are a first-time buyer or purchasing another property, taking time to complete the mortgage preapproval process correctly can save you stress and help you make smarter decisions.
Start by reviewing your financial position, collecting your documents, and contacting trusted lenders to begin your home-buying journey.
First-time home buyer mortgage checklis
FAQ Section
How long does it take to get preapproved for a mortgage?
Most mortgage preapprovals take a few days to one or two weeks depending on the lender, your financial situation, and how quickly you provide required documents.
What credit score is needed for mortgage preapproval?
Credit requirements vary by lender and loan program. Many conventional loans prefer stronger credit profiles, while some government-backed programs may allow different requirements.
Can I get mortgage preapproval without a large down payment?
Yes. Some mortgage programs allow lower down payment options. The amount required depends on the loan type and lender requirements.
Does mortgage preapproval guarantee a home loan?
No. Preapproval means you meet initial lender requirements. Final approval depends on additional factors, including property evaluation and final financial review.
Should I get preapproved before looking for a house?
Yes. Getting preapproved before house hunting helps you understand your budget and shows sellers that you are a serious buyer.






