What Credit Score Do I Need to Get a Mortgage? For most U.S. homebuyers, a credit score of 620 or higher is a common benchmark for a conventional mortgage, but you may qualify with a lower score through certain government-backed programs. Your exact requirement depends on the loan type, lender, down payment, debt-to-income ratio (DTI), income, and overall financial profile.
The good news is that you do not necessarily need a 700 or 800 credit score to buy a home. FHA financing can allow qualifying borrowers to obtain a mortgage with a score as low as 500 when they meet the applicable down-payment requirement. VA and USDA programs do not impose a universal government minimum score, although individual lenders may set their own standards.
If you\’re asking, What Credit Score Do I Need to Get a Mortgage?, the better question is also: Which mortgage program fits my financial situation? A 620 score might be enough for one loan, while a borrower with a 580 score could have another path through FHA financing.
Complete Guide to Mortgage Pre-Approva
What Credit Score Do I Need to Get a Mortgage?

There is no single credit score that guarantees mortgage approval. Mortgage lenders consider your credit history together with income, debts, assets, down payment, employment history, and the property you want to purchase.
Here is a practical 2026 guide to common mortgage score requirements:
| Mortgage Type | Common Minimum Credit Score | Down Payment Consideration |
|---|---|---|
| Conventional | 620 is a common benchmark | Some programs allow as little as 3% |
| FHA | 580 for 3.5% down; 500–579 generally requires 10% down | 3.5% or 10% depending on score |
| VA | No VA-set minimum | Often 0% for eligible borrowers |
| USDA | No USDA-set minimum | Often 0% for eligible borrowers |
| Jumbo | Usually 700+ with many lenders | Varies by lender and loan size |
These are not universal approval guarantees. Lenders can impose additional requirements, and automated underwriting systems may evaluate the entire application rather than relying on a single score threshold. Fannie Mae\’s current guidance, for example, lists a 620 minimum for certain manually underwritten fixed-rate loans, while some Desktop Underwriter casefiles do not have a stated minimum score and are evaluated using broader risk factors.
That distinction matters because two borrowers with the same credit score can receive different decisions.
Conventional mortgage credit score requirements
Conventional mortgages are not insured by the Federal Housing Administration. They are commonly used by borrowers with established credit and can offer competitive pricing when the overall application is strong.
A 620 credit score is a common minimum benchmark, but meeting 620 does not automatically mean you will receive the best rate or even an approval. Fannie Mae notes that credit score requirements can vary according to underwriting method and other loan characteristics.
A stronger score can improve your position because lenders generally view a borrower with a history of responsible credit management as lower risk.
FHA mortgage credit score requirements
FHA loans are designed to provide an alternative for borrowers who may not qualify for conventional financing.
For FHA financing, borrowers with a qualifying score of 580 or higher can generally be eligible for the 3.5% minimum required investment. Borrowers with scores from 500 to 579 generally need at least a 10% investment. Scores below 500 are not eligible for FHA-insured financing under the standard FHA framework.
However, a lender may apply additional requirements. This is why an FHA minimum should be treated as a starting point rather than a guaranteed approval.
VA mortgage credit score requirements
If you are eligible for a VA-backed home loan, the Department of Veterans Affairs itself does not require a minimum credit score.
However, the private lender providing the loan can establish its own credit requirements. The VA specifically advises borrowers that lenders may have their own minimum-score standards.
This is an important distinction when researching What Credit Score Do I Need to Get a Mortgage? A government program may have one rule while the lender actually underwriting your loan has another.
USDA mortgage credit score requirements
USDA-backed mortgages can be attractive to eligible borrowers purchasing homes in qualifying rural areas.
The USDA does not establish one universal minimum credit score for every borrower. In practice, lenders frequently use their own credit standards, and 640 is a commonly cited benchmark for streamlined or automated processing. Requirements can vary according to the borrower\’s circumstances and lender.
Jumbo mortgage credit requirements
Jumbo loans finance properties or loan amounts above applicable conforming limits. Because these loans involve greater balances and lender risk, lenders commonly expect stronger credit and financial reserves.
A score around 700 or higher is common among jumbo lenders, but the exact minimum varies. Other factors, including income, assets, debt, property type, loan amount, and down payment, can be especially important.
Why Does Your Credit Score Matter for a Mortgage?
Your credit score helps a lender estimate how you have managed borrowed money in the past.
A higher score does not guarantee approval, but it can make you a more attractive borrower and may help you qualify for better pricing.
Mortgage lenders may consider:
- Payment history
- Credit utilization
- Length of credit history
- Recent credit applications
- Types of credit accounts
- Outstanding debts
- Collections or serious delinquencies
- Bankruptcy or foreclosure history
- Overall credit profile
Your credit score is only one piece of the application.
For example, someone with a 680 score, stable income, manageable debt and a substantial down payment may have a stronger application than someone with a 760 score but very high monthly debt obligations.
That is why simply asking What Credit Score Do I Need to Get a Mortgage? does not tell the entire story.
Your credit score can affect your mortgage rate
The biggest financial difference between credit-score tiers may not be whether you qualify. It can be how much the mortgage costs you.
Bankrate\’s July 2026 examples for a $300,000 30-year fixed mortgage show how rates varied across FICO score ranges. Its example showed an estimated payment of $2,089 at 620–639 compared with $1,950 at 740–759.
That is a difference of about $139 per month in principal and interest in that example.
Over many years, relatively small rate differences can become substantial amounts of money.
The actual rate you receive will depend on market conditions, lender pricing, loan characteristics and your complete application, so these figures should be treated as an illustration rather than a quote.
What Other Factors Do Mortgage Lenders Consider?
If your credit score is below your target, don\’t assume that buying a home is automatically impossible.
Lenders typically evaluate your entire financial picture.
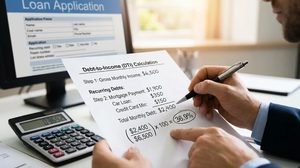
Debt-to-income ratio
Your debt-to-income ratio compares your recurring monthly debt payments with your gross monthly income.
For example, suppose you earn $7,000 per month before taxes and have $2,100 in qualifying monthly debt obligations.
Your DTI would be:
$2,100 ÷ $7,000 = 30%
A lower DTI can make an application stronger because less of your income is already committed to debt.
Different loan programs and lenders have different DTI rules, and compensating factors can matter.
Down payment
A larger down payment can reduce the amount you need to borrow.
For example:
- 3% down on a $300,000 home = $9,000
- 5% down = $15,000
- 10% down = $30,000
- 20% down = $60,000
A larger down payment can also reduce your loan-to-value ratio and, depending on the mortgage, may reduce mortgage insurance costs.
Chase notes that many buyers use down payments between 3% and 20%, depending on the mortgage program and their financial circumstances.
Income and employment
Mortgage lenders want evidence that you can make the proposed payment.
They may review:
- Pay stubs
- W-2 forms
- Tax returns
- Bank statements
- Employment history
- Self-employment income
- Bonuses and commissions
- Other qualifying income
A good credit score cannot compensate for income that is insufficient to support the requested mortgage.
Cash reserves and assets
Your lender may also want to know whether you have enough money for the down payment, closing costs and potentially additional reserves.
Assets can include:
- Checking and savings accounts
- Retirement accounts
- Investments
- Eligible gift funds
- Proceeds from another property
- Other documented sources of funds
Chase notes that lenders can review assets to evaluate whether borrowers can cover upfront costs and remain financially prepared after purchasing the home.
Property and loan characteristics
The property itself can affect underwriting.
Lenders may consider:
- Purchase price
- Appraised value
- Property type
- Primary residence versus investment property
- Number of units
- Loan amount
- Loan-to-value ratio
This is another reason What Credit Score Do I Need to Get a Mortgage? should never be answered with a single number alone.
What Credit Score Is Considered Good for Buying a House?
A FICO score of 670 to 739 is generally categorized as good, while 740 and above falls into the very good range.
For mortgage planning, you can think about your score in practical tiers:
- Below 580: Financing may be difficult, but some FHA options may exist depending on the complete application.
- 580–619: FHA may be more accessible than conventional financing for some borrowers.
- 620–679: Conventional financing may be possible, but pricing and approval depend heavily on the rest of the file.
- 680–739: A stronger position, although not necessarily the best available pricing.
- 740+: Generally a strong credit profile for mortgage shopping.
- 760–780+: May provide access to particularly competitive pricing in some circumstances, although lender pricing varies.
There is no magic score that guarantees the lowest mortgage rate.
The goal should not simply be to reach a particular number. Your objective is to build the strongest overall financial profile you can before applying.
How Can I Improve My Credit Score Before Applying for a Mortgage?
If you are not buying immediately, you may have time to improve your credit profile.
1. Pay every bill on time
Payment history is one of the most important parts of your credit profile.
Set up automatic payments or reminders so you do not accidentally miss a due date.
2. Reduce credit card balances
Credit utilization can influence your score.
If your credit card has a $10,000 limit and you owe $6,000, your utilization on that card is 60%.
Reducing the balance can lower your utilization and may improve your credit profile.
Do not assume that carrying a balance is required to build good credit. Responsible, on-time use and keeping balances manageable are more important.
3. Avoid unnecessary new credit
Applying for several new credit cards, personal loans or auto loans shortly before applying for a mortgage can create additional inquiries and change your debt profile.
If you are preparing for a mortgage, consider delaying unnecessary borrowing until after you understand your lender\’s requirements.
4. Check your credit reports for errors
Before applying, review your reports from the major credit reporting agencies.
Look for:
- Accounts that do not belong to you
- Incorrect late payments
- Incorrect balances
- Duplicate accounts
- Incorrect personal information
- Accounts that should have been removed
You can obtain your federally authorized free credit reports through AnnualCreditReport.com.
5. Do not close old accounts without considering the consequences
Closing an old credit card may reduce available credit and can affect the overall profile lenders see.
If an account has no annual fee and is otherwise manageable, ask yourself whether closing it is actually necessary.
6. Give yourself time
Credit improvement is usually not an overnight process.
If your score is 600 and you hope to qualify for a conventional mortgage, rushing into an application may not be the best strategy.
You could instead spend several months reducing revolving debt, correcting errors and building a consistent payment record.
Can You Get a Mortgage With a Low Credit Score?
A low score can reduce your options, increase the interest rate you are offered, increase mortgage insurance costs or require a larger down payment. But it does not automatically mean you cannot buy a home.
FHA financing is one of the clearest examples. A borrower with a qualifying score between 500 and 579 may be eligible for FHA financing with a 10% down payment, while 580 or higher can generally qualify for the 3.5% minimum investment requirement, subject to FHA and lender underwriting rules.
You may also have other options depending on your eligibility, including VA or USDA financing.
What if you have no credit score?
Having no traditional credit score is different from having a poor score.
A person who has never used credit may have a limited credit history rather than a history of missed payments.
Some mortgage programs and underwriting systems may allow alternative methods of evaluating creditworthiness, but documentation requirements can be more involved.
If you have little or no credit history, ask lenders specifically whether they offer manual underwriting or programs designed for borrowers with limited credit.
What Credit Score Do I Need to Get a Mortgage If I\’m a First-Time Buyer?
Being a first-time buyer does not automatically give you a separate universal credit-score requirement.
Your minimum score generally depends on the mortgage program you choose and the lender providing the loan.
However, first-time buyers may have access to:
- FHA financing
- Conventional low-down-payment programs
- State and local down-payment assistance
- Homebuyer education programs
- Certain income-based assistance programs
For example, Fannie Mae\’s HomeReady program lists a minimum credit score of 620 and can allow eligible borrowers to purchase with as little as 3% down.
The key is to compare the total cost of the mortgage rather than focusing only on the minimum score.
What Should You Do Before Applying for a Mortgage?
If you\’re serious about buying a home, use this checklist before submitting a full mortgage application:
- Check all three credit reports.
- Review your credit scores.
- Correct inaccurate information.
- Pay down high credit-card balances.
- Avoid unnecessary new credit.
- Calculate your monthly debt-to-income ratio.
- Save for your down payment.
- Budget for closing costs.
- Keep additional emergency savings.
- Gather income and asset documents.
- Compare mortgage programs.
- Get preapproved before seriously shopping for homes.
A mortgage preapproval can help you understand how much you may be able to borrow and can make your offer more credible to sellers. Chase and Fidelity both emphasize preapproval as an important part of preparing for the homebuying process.
An important 2026 reality check
One of the biggest mistakes homebuyers make is treating the minimum credit score as the target.
For example, imagine two borrowers shopping for the same $300,000 home. Borrower A has a 620 score, while Borrower B has a 740 score. Both might technically qualify for a mortgage, but their pricing could be very different.
Bankrate\’s July 2026 example illustrates the potential scale of that difference: its $300,000 30-year example showed $2,089 in principal-and-interest payments for the 620–639 tier versus $1,950 for 740–759.
That means the question is not only What Credit Score Do I Need to Get a Mortgage? It is also What score can help me borrow at a cost I can comfortably afford?
That is a much more useful way to approach mortgage preparation.
What Credit Score Do I Need to Get a Mortgage? The Bottom Line
For many conventional mortgages, 620 is a common minimum benchmark. FHA financing can potentially work with scores as low as 500, depending on the down payment and underwriting. VA and USDA programs do not impose one universal government minimum score, although lenders can establish their own requirements.
A higher credit score can improve your chances of approval and may help you qualify for more competitive mortgage pricing, but it is only one part of the application.
Before applying, focus on the complete financial picture: credit, income, DTI, down payment, assets, employment history and the type of mortgage you choose.
If your score is not where you want it to be, you may not need to give up on homeownership. Compare loan programs, improve your credit where possible and speak with multiple qualified lenders to understand your actual options.
For authoritative mortgage information, you can also review guidance from Fannie Mae, HUD/FHA and VA home loans.
What Are the Closing Costs When Buying a Home
Frequently Asked Questions
What Credit Score Do I Need to Get a Mortgage?
For many conventional mortgages, 620 is a common minimum benchmark. However, FHA, VA, USDA and jumbo loans can have different requirements. Your lender also considers income, debt, assets, down payment and other factors.
Can I get a mortgage with a 500 credit score?
Potentially. FHA guidelines allow qualifying borrowers with scores from 500 to 579 to use the FHA program with a 10% minimum down payment. Approval is still subject to underwriting and lender requirements.
Is 620 a good credit score to buy a house?
A 620 score can be sufficient for some conventional mortgage programs, but it is closer to a minimum qualification benchmark than an ideal target. A higher score may provide access to better pricing and more mortgage options.
Is 700 a good credit score for a mortgage?
Yes. A 700 score is generally considered a good FICO score and can put a borrower in a stronger position than someone near the minimum qualifying threshold. However, the mortgage rate still depends on the lender, loan type, market conditions and other financial factors.
Can I get a mortgage with no credit score?
Possibly. Some borrowers with limited or no traditional credit history may qualify through alternative or manual underwriting, depending on the mortgage program and lender. The process may require additional documentation to establish a history of responsible financial payments.
Does a higher credit score lower my mortgage rate?
It can. Mortgage pricing often improves as credit risk decreases, but your score is not the only factor. Loan type, down payment, DTI, loan amount, property and market conditions can also affect your rate.