The short answer to the question can you use a personal loan for a mortgage down payment is, in almost every case, no. For a conventional loan and for an FHA loan, the down payment must come from your own funds, from an acceptable gift, or from an approved down payment assistance program. A personal loan is borrowed money, and lenders do not accept borrowed money as a down payment, because it is not really your money. It is a debt you must repay, and it changes the risk of the mortgage in ways lenders are not willing to accept. That rule surprises many first time buyers who are short on savings. This article explains why lenders say no, how they find out, what sources do count, and which alternatives can help you buy sooner.
Can You Use a Personal Loan for a Mortgage Down Payment? Why Lenders Say No
A mortgage lender is not only lending you money to buy a home. It is also judging whether you can afford to keep paying that mortgage for years, even when life gets difficult. The down payment is part of that judgement. When you put your own savings into a home, you have a real stake in it, and you are less likely to walk away if the home loses value, because you would lose your own money first. When the down payment comes from a personal loan, that stake is not real. You have no savings in the home, and you have two monthly payments instead of one, the mortgage and the personal loan. For conventional loans, Fannie Mae and Freddie Mac require the down payment to come from acceptable sources, and they do not allow it to be borrowed from an unsecured loan. FHA rules are similar. The Consumer Financial Protection Bureau home buying resources explain that lenders must verify the source of your funds, and the Fannie Mae home buying guidance sets out the same principle. A personal loan also has a short term, often three to five years, and a high rate, so a 20,000 dollar loan could add several hundred dollars to your monthly debts.
How Lenders Find Out About Borrowed Down Payment Funds
Some buyers wonder whether they can take a personal loan, deposit it in their bank account, wait a few weeks, and then show a bank statement that looks like savings. Lenders are prepared for that. They ask for two months of bank statements, and they look for large deposits that do not match your normal income. A deposit of 15,000 or 20,000 dollars from a personal loan will stand out, and the underwriter will ask where it came from. You will be asked to provide a paper trail for every large deposit, with a letter explaining the source and documents to support it. Lenders also pull your credit report during the application, and again before closing in many cases. A new personal loan will appear on your credit report, with its balance and monthly payment, and it will be counted in your debts. Even if you take the loan after preapproval, a credit refresh before closing can reveal it. Hiding a loan is serious: a mortgage application is a signed statement, and false information can be treated as mortgage fraud. It is never worth the risk, and the paper trail is too clear.
How a Personal Loan Affects Your Debt to Income Ratio
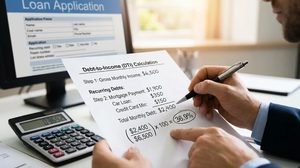
Even if a personal loan could be used for a down payment, which it cannot for a standard mortgage, it would still hurt your application through your debt to income ratio, known as DTI. DTI compares your total monthly debt payments to your gross monthly income, and most lenders want total DTI at or below 45 percent for a conventional loan, with many preferring 43 percent or lower. For example, a buyer earning 6,000 dollars a month with 750 dollars of debts and a 1,900 dollar mortgage payment has a DTI of about 44 percent, near the limit. Add a personal loan payment of 450 dollars and DTI rises to about 52 percent, above the limit for most lenders. See the guide to what PITI is and how it makes up your mortgage payment.
What Counts as an Acceptable Down Payment Source
Your own savings are the simplest source, including money in checking or savings, and in some cases a retirement account, although early withdrawal can trigger taxes and penalties. Lenders usually want the money seasoned in your account for at least two months. Gift funds from a family member can be used for a conventional or FHA loan, but the donor must write a gift letter stating it is a gift, not a loan. Down payment assistance programs are a third source, often the best option for a buyer short on savings: many states, cities and counties offer grants or low interest second loans to first time buyers. The sale of an asset can also count, with proof of the sale. All of these share one thing: the money is yours, or a genuine gift or approved grant, and it creates no new monthly debt.
| Down payment source | Usually accepted? | Notes |
|---|---|---|
| Own savings, seasoned 2 months | Yes | Simplest source, must be documented |
| Gift funds from family | Yes, with a gift letter | Donor must state it is not a loan |
| Down payment assistance grant | Yes, if program is approved | Lender must approve the program |
| Down payment assistance loan | Sometimes | Must meet loan program rules |
| Sale of an asset | Yes, with proof of sale | Must show the paper trail |
| Personal loan | No | Borrowed money, creates new debt |
| Credit card cash advance | No | Borrowed money, very high cost |
Down Payment Assistance and Gift Funds Explained
Each state has a housing finance agency that runs first time buyer programs, and many cities and counties add their own grants. These programs often cover 3 to 5 percent of the home price, enough for the minimum down payment on a conventional or FHA loan. Some require a short homebuyer education course. Gift funds also need care: if your parents give you 20,000 dollars and expect repayment, that is a loan, not a gift, and it will not be accepted. The guide to HomeReady and Home Possible loans (https://mortgageguiderhub.com/how-to-assume-a-mortgage-in-2026/) explains two conventional options that allow as little as 3 percent down for qualified buyers, and an FHA loan allows 3.5 percent down for many buyers.
Alternatives to Borrowing Your Down Payment
If you do not have enough savings yet, wait and save, or use an approved program, rather than borrowing the down payment. An automatic transfer to a separate home fund on payday helps savings grow, and a tax refund, work bonus or sale of a vehicle can also count if documented. Another alternative is to buy a less expensive home: 3 percent down on a 250,000 dollar home is 7,500 dollars, against 12,000 dollars on a 400,000 dollar home. You can also ask the seller for help with closing costs, known as seller concessions, although that applies to closing costs, not the down payment. See the guide on how to pay off your mortgage early. A personal loan can be reasonable to pay off high interest credit card debt, which can improve your score and lower DTI, but pay it off several months before you apply, not during the application.
What to Do If You Already Took a Personal Loan
If you have already taken a personal loan, do not hide it. Tell your lender at the start and ask how it affects your application. In many cases the best step is to delay the purchase until the loan is paid off, or until the payment no longer pushes your DTI over the limit. That delay is frustrating, but it is better than a denial after you have made an offer and paid for an appraisal and inspection. The Freddie Mac home buying resources include guides on preparing your finances before you apply.
The Bottom Line for Buyers
A personal loan cannot be used for a mortgage down payment on a conventional or FHA loan, and trying to use one can delay or end your application and hurt your debt to income ratio. The down payment must come from your own savings, a documented gift, or an approved assistance program. If you are short on savings, save for a smaller down payment through a low down payment program, use gift funds or assistance if you qualify, or buy a less expensive home. Talk to your lender early and build your plan around the rules, not a shortcut lenders will find.
#PersonalLoan #MortgageDownPayment #DownPaymentAssistance #FirstTimeHomeBuyer #MortgageApproval #HomeBuying