
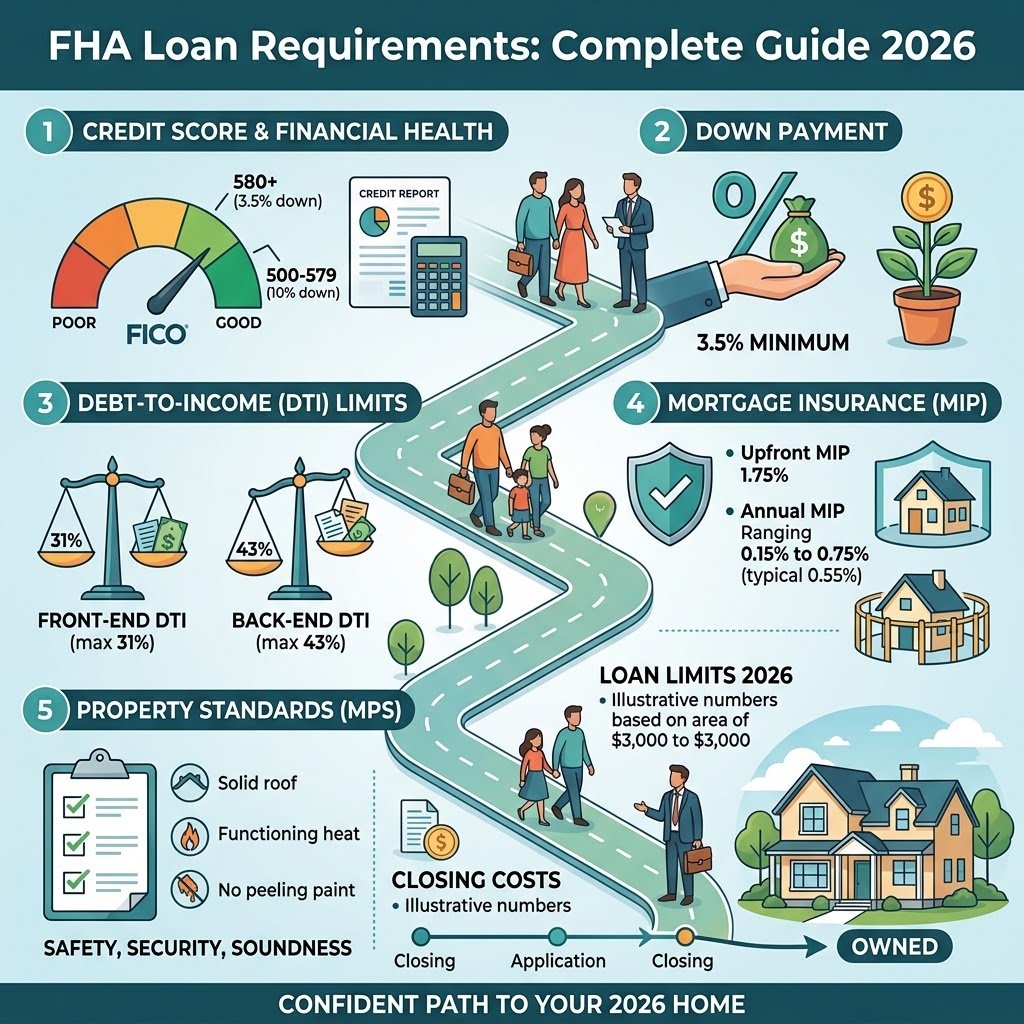
Buying a home can feel overwhelming, especially when you are unsure about mortgage rules, credit requirements, and upfront costs. FHA Loan Requirements: Complete Guide 2026 explains everything buyers need to know before applying for an FHA-insured mortgage.
An FHA loan is a government-backed mortgage designed to make homeownership more accessible, especially for first-time buyers and borrowers who may not qualify for traditional financing. The main requirements include a qualifying credit score, minimum down payment, stable income, acceptable debt levels, and an FHA-approved property appraisal.
In 2026, many buyers are looking for flexible mortgage options because saving for a large down payment and meeting strict conventional loan standards can be challenging. Understanding FHA guidelines before applying can help you avoid delays, improve your approval chances, and prepare financially.
This guide covers FHA eligibility rules, credit score requirements, down payment details, income verification, application steps, common mistakes, and important factors every buyer should understand before starting the mortgage process.
What Are FHA Loan Requirements in 2026?
FHA loan requirements are the financial and property standards borrowers must meet to qualify for an FHA-insured mortgage. These rules are established by the Federal Housing Administration and followed by FHA-approved lenders.
Unlike some conventional loans that require stronger credit profiles, FHA financing is designed to support a wider range of borrowers. However, approval is still based on factors such as credit history, income stability, debt obligations, and the ability to repay the mortgage.
The basic FHA loan requirements in 2026 include:
- Minimum credit score requirements
- Down payment availability
- Stable employment and income
- Acceptable debt-to-income ratio
- FHA-approved property standards
- Mortgage insurance requirements
According to FHA guidelines, borrowers with stronger credit profiles may receive better terms, while buyers with lower credit scores may need additional financial preparation.
[INTERNAL LINK: FHA Loan Basics Guide]
How FHA Loans Work for First-Time Home Buyers
FHA loans are popular among first-time home buyers because they allow lower down payments compared with many conventional mortgage options.
A qualified borrower may be able to purchase a home with a down payment as low as 3.5% when meeting FHA credit requirements. This makes FHA financing attractive for buyers who have reliable income but limited savings.
For example, if a home costs $300,000, a buyer who qualifies for the minimum down payment could potentially need around $10,500 upfront instead of saving for a much larger conventional loan deposit.
However, buyers should remember that the down payment is not the only cost. Closing expenses, mortgage insurance premiums, taxes, and property-related fees should also be included in the overall budget.
Why Buyers Choose FHA Financing Over Conventional Loans
Many buyers consider FHA loans because of their flexible qualification standards.
Some common reasons include:
- Lower minimum down payment options
- More flexible credit requirements
- Possibility of using approved gift funds
- Support for first-time buyers
- Availability through many FHA-approved lenders
However, FHA loans also include mortgage insurance requirements, which can increase monthly costs. Buyers should compare different mortgage options based on their financial situation.
FHA vs Conventional Loan Comparison
FHA Loan Requirements: Complete Eligibility Rules for 2026
Understanding eligibility requirements is one of the most important steps before applying for an FHA mortgage.
While FHA loans provide more flexibility than some traditional mortgages, lenders still review your complete financial profile to determine whether you can manage monthly payments.
Minimum Credit Score Requirements
Credit score is one of the biggest factors in FHA mortgage approval.
Generally:
- A credit score of 580 or higher may qualify borrowers for the 3.5% minimum down payment option.
- Borrowers with credit scores between 500 and 579 may still qualify but usually need a higher down payment.
Your credit score affects not only eligibility but also how lenders evaluate your overall financial risk.
Before applying, review your credit report for:
- Incorrect information
- Late payment records
- High credit card balances
- Outstanding collections
Improving your credit profile before submitting an application may help you receive better loan terms.
FHA Down Payment Requirements
The FHA down payment requirement is one of the main reasons buyers choose this mortgage option.
For eligible borrowers:
- 580+ credit score: Minimum 3.5% down payment
- 500–579 credit score: Usually 10% down payment
The money used for a down payment can sometimes come from approved sources such as:
- Personal savings
- Gift funds from eligible donors
- Down payment assistance programs
Buyers should keep documentation showing where their funds came from because lenders must verify the source of money used during the mortgage processFHA Loan Requirements: Complete Guide 2026
FHA Loan Requirements: Complete Eligibility Rules for 2026 (Continued)
Debt-to-Income Ratio (DTI) Guidelines
Your debt-to-income ratio (DTI) is another important factor lenders review when you apply for an FHA mortgage. DTI compares your monthly debt payments with your gross monthly income.
The formula is simple:
Monthly debt payments ÷ Gross monthly income = Debt-to-income ratio
For example, if your monthly income is $6,000 and your total monthly debts are $2,400, your DTI ratio is 40%.
FHA lenders generally prefer borrowers to have manageable debt levels. While many lenders look for a DTI ratio around 43% or lower, borrowers with strong credit, savings, or other financial strengths may sometimes qualify with higher ratios.
Common debts included in DTI calculations include:
- Car loans
- Student loans
- Credit card payments
- Personal loans
- Existing mortgage payments
- Child support or alimony obligations
Before applying, review your monthly obligations and consider paying down high-interest debts. A lower DTI ratio can improve your financial profile and make the mortgage process smoother.
Employment and Income Verification Rules
Stable income is a key requirement for FHA mortgage approval. Lenders want to confirm that you have enough reliable income to manage monthly mortgage payments.
During the application process, lenders usually review:
- Employment history
- Income records
- Tax documents
- Bank statements
- Recent pay stubs
Many lenders prefer to see consistent employment history, although FHA guidelines can allow flexibility for borrowers who have changed jobs, switched careers, or have alternative income sources.
Accepted income may include:
- Salary income
- Hourly wages
- Self-employment income
- Commission income
- Retirement income
- Certain government benefits
Self-employed buyers may need additional documentation, such as business tax returns and profit-and-loss statements.
A practical example: A self-employed buyer earning $85,000 annually may qualify differently from a salaried employee earning the same amount because lenders must verify business stability and income consistency.
FHA Property Requirements and Appraisal Rules
FHA approval is not only about the borrower. The property itself must also meet FHA standards.
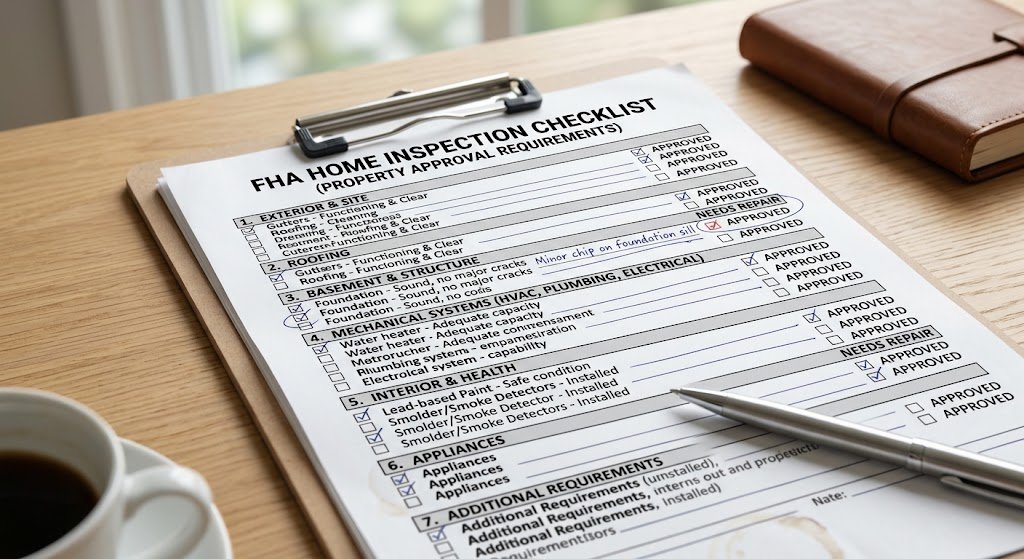
Before approving the loan, an FHA-approved appraiser checks whether the home meets minimum property requirements.
The appraisal reviews:
- Safety conditions
- Structural issues
- Basic habitability
- Property value
- Required repairs
Common issues that may delay approval include:
- Roof damage
- Electrical problems
- Plumbing concerns
- Safety hazards
- Major structural problems
The goal is to ensure that buyers are purchasing a safe and suitable home while protecting the lender’s investment.
What Credit Score Do You Need for an FHA Loan in 2026?
Credit score is one of the first things most buyers check when considering FHA financing.
The FHA credit score requirements for 2026 generally work like this:
| Credit Score | Typical Down Payment Requirement |
|---|---|
| 580 or above | 3.5% minimum down payment |
| 500–579 | 10% minimum down payment |
A higher credit score can make the mortgage process easier because lenders may view you as a lower-risk borrower.
However, credit score is only one part of approval. A borrower with a lower score but strong income, low debt, and good payment history may still have opportunities.
Can You Get an FHA Loan With Bad Credit?
Yes, some borrowers with lower credit scores may still qualify for FHA financing.
The FHA program was created partly to help borrowers who may face challenges obtaining traditional mortgages. However, lenders will still review:
- Payment history
- Recent credit activity
- Existing debts
- Income stability
Steps that may improve your approval chances include:
- Paying bills on time
- Reducing credit card balances
- Avoiding new debt before applying
- Reviewing your credit report for errors
Improving your credit before applying can also help you receive better mortgage terms.
How Much Down Payment Is Needed for an FHA Loan?
The FHA down payment requirement is one of the biggest advantages of this mortgage program.
For many qualified borrowers, the minimum down payment is 3.5% of the home’s purchase price.
For example:
Home price: $250,000
3.5% down payment: $8,750
However, buyers should prepare for additional expenses, including:
- Closing costs
- Mortgage insurance premiums
- Property taxes
- Homeowners insurance
A complete budget helps prevent financial stress after purchasing the home.
Down Payment Assistance Options for FHA Buyers
Many first-time buyers struggle with saving enough money for upfront costs. FHA borrowers may have access to assistance programs depending on location and eligibility.
Possible sources include:
- State housing programs
- Local government assistance
- Employer assistance programs
- Approved gift funds
Each program has different rules, income limits, and requirements.
Buyers should research available options in their state before starting the mortgage application.
First Time Home Buyer Programs
FHA Loan Requirements vs Conventional Loan Requirements
Choosing between FHA and conventional financing depends on your financial situation, goals, and long-term plans.
FHA Loan Benefits
FHA loans may be suitable for buyers who want:
- Lower down payment options
- More flexible credit standards
- Easier qualification requirements
- Support with limited savings
FHA Loan Limitations
Although FHA loans provide flexibility, they also have some disadvantages:
- Mortgage insurance requirements
- FHA property standards
- Loan limits based on location
- Additional approval steps
FHA vs Conventional Loan Comparison
| Feature | FHA Loan | Conventional Loan |
|---|---|---|
| Minimum Down Payment | Often 3.5% | Often 3% or higher |
| Credit Flexibility | More flexible | Usually stricter |
| Mortgage Insurance | Required | Depends on down payment |
| Property Rules | FHA appraisal required | Standard appraisal |
The right choice depends on your income, credit profile, savings, and homeownership goals.
Mortgage Broker Guide
FHA Loan Requirements: Complete Guide 2026
FHA Loan Application Process Step by Step
Understanding the FHA mortgage process before applying can save time and prevent unexpected problems. While every lender may have slightly different procedures, most FHA applications follow a similar path.
Check Your Financial Eligibility
Before contacting a lender, review your financial situation.
Start by checking:
- Credit score
- Monthly income
- Existing debts
- Savings amount
- Employment history
A simple financial review helps you understand whether you meet basic FHA Loan Requirements before submitting an application.
You should also collect important documents, including:
- Government-issued identification
- Recent pay stubs
- Tax returns
- Bank statements
- Employment records
- Credit information
Being prepared can make the approval process faster and reduce unnecessary delays.
Get FHA Loan Pre-Approval
FHA pre-approval gives you an estimate of how much you may be able to borrow.
During pre-approval, a lender reviews:
- Income
- Credit history
- Debt obligations
- Available assets
A pre-approval letter can also help buyers understand their realistic home price range before making offers.
For example, a buyer earning $75,000 per year with manageable debt may qualify for a different loan amount compared with someone earning the same income but carrying large monthly obligations.
Pre-approval is not a final loan approval, but it is an important step toward purchasing a home.
Submit Your Mortgage Application and Documents
After choosing a lender and property, you will complete the official mortgage application.
The lender will verify:
- Your identity
- Income sources
- Employment status
- Credit history
- Financial documents
During this stage, avoid making major financial changes such as:
- Opening new credit accounts
- Taking large loans
- Changing jobs without discussing it with your lender
These actions may affect your approval decision.
Complete FHA Home Appraisal
An FHA-approved appraiser evaluates the property before the loan can move forward.
The appraisal confirms:
- The home’s market value
- Property condition
- Safety requirements
- Necessary repairs
Unlike a basic home inspection, an FHA appraisal focuses on whether the property meets FHA minimum standards.
If major issues are discovered, repairs may need to be completed before closing.
Final Approval and Closing
After underwriting is complete and all requirements are satisfied, the lender provides final loan approval.
Before closing, buyers review:
- Loan terms
- Monthly payment details
- Closing costs
- Required paperwork
At closing, ownership documents are signed, funds are transferred, and the buyer officially becomes the homeowner.
Mortgage Closing Process Guide
Common FHA Loan Mistakes Buyers Should Avoid
Even qualified buyers can experience delays if they make mistakes during the mortgage process.
Avoiding these common problems can make your FHA application smoother.
Ignoring Credit Improvement Before Applying
Some buyers apply immediately without reviewing their credit profile.
Small improvements can make a difference, such as:
- Paying down credit card balances
- Correcting credit report errors
- Avoiding missed payments
A few months of responsible financial management may strengthen your application.
Underestimating Total Home Buying Costs
Many buyers focus only on the down payment and forget about other expenses.
Additional costs may include:
- Closing fees
- Home insurance
- Property taxes
- Moving expenses
- Maintenance costs
A realistic budget should include both upfront and ongoing expenses.
Not Comparing FHA Lenders
FHA loans follow federal guidelines, but lenders may offer different rates, fees, and customer experiences.
Before choosing a lender, compare:
- Interest rates
- Closing costs
- Customer service
- Experience with FHA borrowers
Working with an FHA-approved lender who understands your situation can make the process easier.
Making Large Financial Changes During Approval
Once you begin the mortgage process, consistency matters.
Avoid:
- Changing jobs without guidance
- Depositing unexplained large amounts of money
- Financing expensive purchases
- Missing payments
Lenders review your finances again before closing, so maintaining stability is important.
Final Thoughts on FHA Loan Requirements in 2026
FHA Loan Requirements: Complete Guide 2026 shows that qualifying for an FHA mortgage depends on more than just having a good credit score. Buyers need to understand down payment rules, income verification, debt limits, property standards, and the complete approval process.
FHA loans remain a popular option for many Americans because they provide flexible qualification paths and lower upfront costs compared with some traditional mortgage options.
Before applying, review your credit, organize your documents, calculate your budget, and compare FHA-approved lenders. A prepared buyer has a better understanding of the process and can make more confident decisions.
If you are planning to purchase a home in 2026, start by checking your eligibility and creating a realistic financial plan.
Frequently Asked Questions (FAQ)
What is the minimum credit score for an FHA loan in 2026?
The minimum credit score depends on the borrower’s financial profile. Generally, borrowers with a credit score of 580 or higher may qualify for a 3.5% down payment option, while borrowers with scores between 500 and 579 may require a larger down payment.
How much down payment is required for an FHA loan?
Many qualified FHA borrowers can purchase a home with a minimum down payment of 3.5% when they have a credit score of 580 or above. Buyers with lower scores may need a higher down payment.
Can first-time buyers qualify for FHA loans?
Yes. FHA loans are commonly used by first-time home buyers because they offer flexible credit requirements and lower down payment options compared with many conventional mortgages.
Are FHA loans harder to get than conventional loans?
FHA loans are often designed to be more flexible for borrowers with limited savings or lower credit scores. However, borrowers still need to meet income, debt, credit, and property requirements.
What income is needed to qualify for an FHA mortgage?
There is no single income amount required for an FHA loan. Lenders evaluate whether your income is stable and sufficient to cover your mortgage payment and other financial obligations.






