If you are shopping for a home loan, you will hear the same advice from almost everyone: get quotes from more than one lender. What people often forget to say is that the type of lender matters just as much as the quote. A credit union vs bank mortgage comparison is not a small detail. The two kinds of institution are built differently, they price loans differently, and they treat borrowers differently when an application is not straightforward. In 2026, with mortgage rates still high by recent standards, the gap between them can be worth tens of thousands of dollars over the life of a loan, or it can be worth nothing at all if you pick the wrong one for your situation.
Credit Union vs Bank Mortgage at a Glance
The simplest way to understand the difference is to look at who owns the institution. A bank is owned by its shareholders, and its job is to earn a profit for them. A credit union is owned by its members, and it is run as a not-for-profit cooperative. Profits at a credit union are returned to members as lower loan rates, higher savings yields and lower fees, rather than paid out to shareholders. That structural difference shows up in the pricing data year after year.
That does not mean a credit union wins on every point. Banks are usually bigger, with more branches, more technology, and a wider range of loan products. Some borrowers will get a better deal or a loan product their local credit union does not offer from a bank. The table below gives the short version.
| Factor | Credit union | Bank |
|---|---|---|
| Ownership | Member owned, not-for-profit cooperative | Shareholder owned, for-profit company |
| 30-year fixed rate, national average | 6.26 percent (NCUA, Dec 26, 2025) | 6.50 percent (NCUA, Dec 26, 2025) |
| 15-year fixed rate, national average | 5.76 percent (NCUA, Dec 26, 2025) | 6.07 percent (NCUA, Dec 26, 2025) |
| Fees | Usually lower origination and application fees | Vary widely, often higher at large national banks |
| Service | Local, often the same person from start to finish | Can be excellent, but often passed between departments |
| Approval flexibility | More willing to look at the whole file | More likely to follow a strict automated checklist |
| Membership | Must be eligible to join | Open to anyone |
| Branches and technology | Fewer branches, apps vary | Large networks, usually strong apps |
| Loan range | Solid on standard loans, thinner on niche products | Wide range, including jumbo and construction |
| Deposit insurance | NCUA, up to $250,000 per depositor | FDIC, up to $250,000 per depositor |
Rates: Where Credit Unions Usually Win
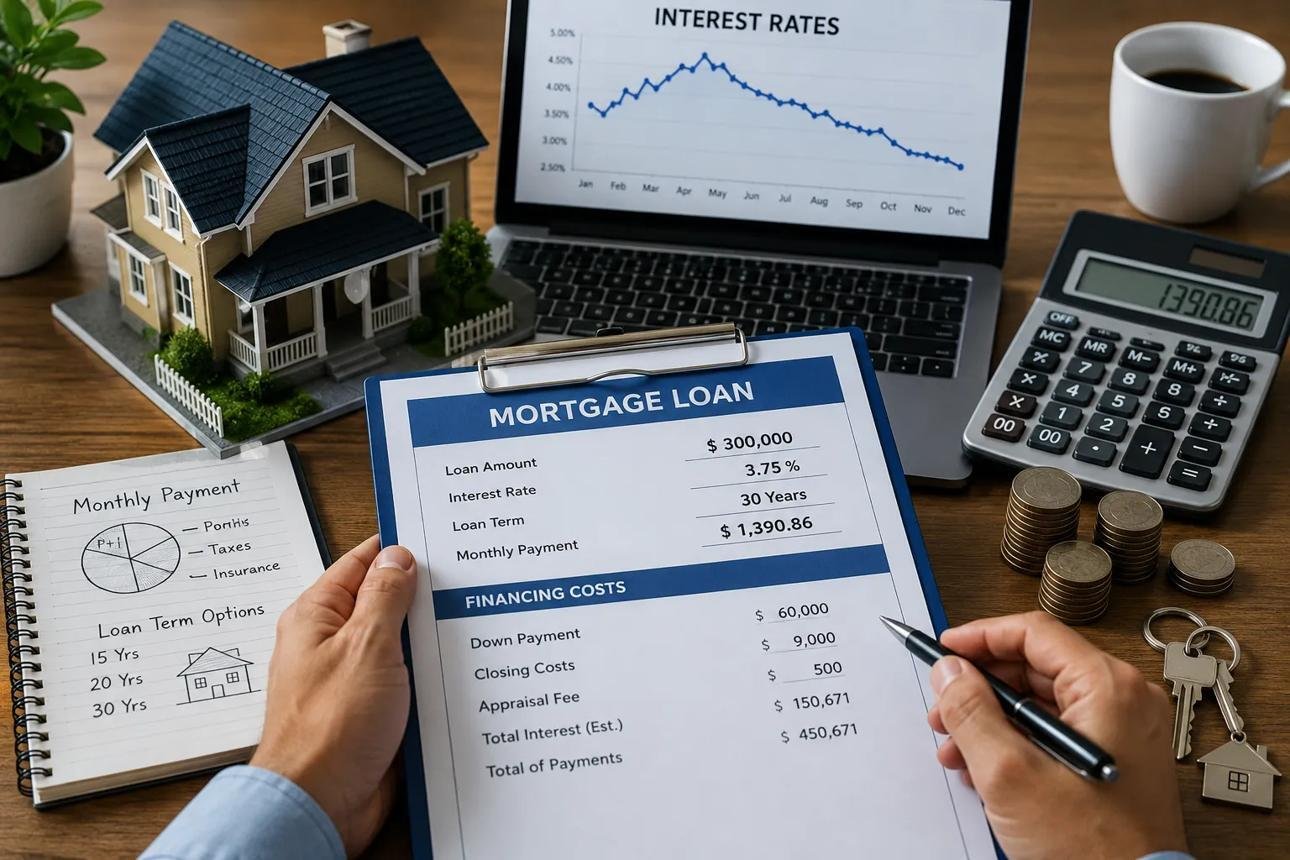
Rates are where credit unions have the clearest edge, and the data is public. The National Credit Union Administration publishes a quarterly comparison of average loan rates at credit unions and banks. Its most recent release covers rates reported for December 26, 2025. Credit unions averaged 6.26 percent on a 30-year fixed mortgage against 6.50 percent at banks. On a 15-year fixed mortgage the gap was 5.76 percent against 6.07 percent, and on a 5-year adjustable-rate mortgage it was 5.73 percent against 6.55 percent.
Those are national averages, not quotes for a particular buyer. Your own rate will depend on your credit score, down payment, loan size and location. For a benchmark, Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed rate at 6.76 percent and the 15-year at 6.09 percent as of September 10, 2026.
What does a quarter point save you? On a $400,000 loan, the 0.24 point gap in the NCUA averages is worth about $63 a month, or roughly $22,800 in interest over 30 years before fees. That is an estimate from the published averages, not a promise about your loan.
Fees and Closing Costs
Rates get the attention, but fees decide a large part of what you pay to close. Origination, application, processing, underwriting and appraisal charges vary far more between lenders than headline rates do. Median total loan costs reached about $6,700 on a home purchase loan in 2023, according to CFPB data.
Credit unions usually charge less. Many charge no application fee, lower origination fees than large banks, and lower fees for rate locks or document preparation. Some offer lender credits toward closing costs, or first-time buyer programs with reduced fees.
The only reliable way to compare fees is the Loan Estimate. Every lender must give you one within three business days of your application, listing the same cost categories in the same format. Put two Loan Estimates side by side and compare origination charges, services you cannot shop for, and cash to close.
Service and Approval Flexibility
Service is harder to measure than rates, but it matters most when something goes wrong. Credit unions are often praised for personal service. You are more likely to deal with the same loan officer from application to closing and to get a straight answer rather than a transfer. Their staff often know the local market and the local appraisers.
Banks have a different strength, which is scale. A large bank can process a high volume of loans, invest heavily in online tools, and offer fully digital applications and 24 hour customer service. If you value a polished app and the ability to do everything from your phone, a large bank will usually beat a small credit union.
Approval flexibility follows a similar pattern. Both types must follow the same agency rules for loans sold to Fannie Mae, Freddie Mac, FHA or VA. Where they differ is in files that do not fit neatly into the automated system. Credit unions are more likely to consider compensating factors, such as a long membership history or a strong savings record, and they may keep some loans in their own portfolio, giving them more freedom to make exceptions. Large banks rely more on automated underwriting and stricter overlays. If you are a borderline case, a credit union is often the better place to start.
Membership Requirements: The One Real Hurdle
The main drawback of a credit union is that you have to be eligible to join it. Credit unions serve a defined field of membership, which might be the employees of a particular company, the members of a union or association, or the residents of a particular county. You cannot simply walk into any credit union and open an account, the way you can with a bank.
In practice this is much less of a barrier than it sounds. Many credit unions now serve a whole community, so living or working in their area is enough to join. Others let you join through a partner association, and some are open to family members of existing members. The NCUA reported about 144.7 million members and 4,287 federally insured credit unions in the fourth quarter of 2025.
Joining is usually simple and cheap. You open a share savings account, often with a deposit of $5 to $25, and that deposit makes you a member and part owner. You will need identification and proof of eligibility, such as a pay stub or a utility bill. Banks have no such hurdle, which is a real advantage if you need a loan quickly.
Which Lender Suits You Best, and How to Compare
Choose a credit union first if you want the lowest rate and fees on a standard loan, you value personal service and a single point of contact, your file is slightly unusual and might benefit from a human review, and you already belong to a credit union or can easily join one. First-time buyers often do well at credit unions.
Choose a bank first if you need a loan product your local credit union does not offer, such as a jumbo loan or a construction loan, you want a fully digital application and a large branch network, or you are buying where no credit union serves you.
Whatever you lean toward, compare quotes the same way every time. Get at least three Loan Estimates, including at least one credit union and at least one bank, within the same short period. Multiple mortgage inquiries in a short window are generally treated as one inquiry for credit scoring, as our guide to mortgage rate shopping windows explains. Compare the rate and the APR together, the origination charges, the cash to close, and the monthly payment including taxes and insurance, which our guide to what PITI includes explains. If you plan to stay for many years, the lowest rate usually wins; if you plan to move soon, the lowest fees usually win, so read our guide to rate-and-term refinancing before you need it.
Frequently Asked Questions
Is a credit union mortgage cheaper than a bank mortgage?
On average, yes. NCUA data for December 26, 2025, show credit unions averaged 6.26 percent on a 30-year fixed mortgage against 6.50 percent at banks. Compare Loan Estimates for your own loan.
What is the difference between a credit union and a bank?
A credit union is a member-owned, not-for-profit cooperative that returns profits to members through better rates and lower fees. A bank is a shareholder-owned, for-profit company.
Do I need to be a member to get a credit union mortgage?
Yes, you need to be eligible to join, usually through where you live or work, your employer, or an association. Joining usually means opening a small share savings account.
Are credit union mortgage rates lower in 2026?
The latest NCUA comparison, covering December 26, 2025, shows credit unions lower than banks on 30-year fixed, 15-year fixed and 5-year adjustable mortgages. Freddie Mac put the 30-year fixed rate at 6.76 percent in September 2026.
Can a credit union approve a mortgage a bank would deny?
Sometimes. Both must follow the same agency rules for loans they sell, but credit unions are often more willing to look at compensating factors and to keep a loan in their own portfolio.
Do banks offer more mortgage products than credit unions?
Usually, yes. Large banks tend to offer a wider range, including jumbo loans, construction loans and portfolio products that a small credit union may not carry.
Are credit union mortgages slower to close?
Not necessarily. A small credit union can be slower with limited staff, but it can also be faster because you deal with one person and decisions are made locally.
Is my money safe at a credit union?
Yes, if it is federally insured. Deposits at federally insured credit unions are covered by the NCUA Share Insurance Fund up to $250,000 per depositor, just as bank deposits are covered by the FDIC.
Should I get quotes from both a credit union and a bank?
Yes. Get at least three Loan Estimates, including at least one credit union and at least one bank, within the same short period. Compare the rate, the APR, origination charges, and cash to close.
Do credit unions charge lower closing costs?
They usually do, with lower origination and application fees and sometimes lender credits toward closing costs. The only reliable comparison is the Loan Estimate, which lists the same cost categories for every lender.
Can I get an FHA or VA loan from a credit union?
Yes, most larger credit unions offer FHA, VA and USDA loans as well as conventional loans. Smaller credit unions may offer a narrower range, so ask about the specific program you need.
Which is better for a first-time buyer, a credit union or a bank?
A credit union is often a good first stop for a first-time buyer, because of lower rates and fees and more personal guidance. But compare at least one of each before you choose.
#mortgageguiderhub #creditunionmortgage #bankmortgage #mortgagerates2026 #homeloan #firsttimehomebuyer