
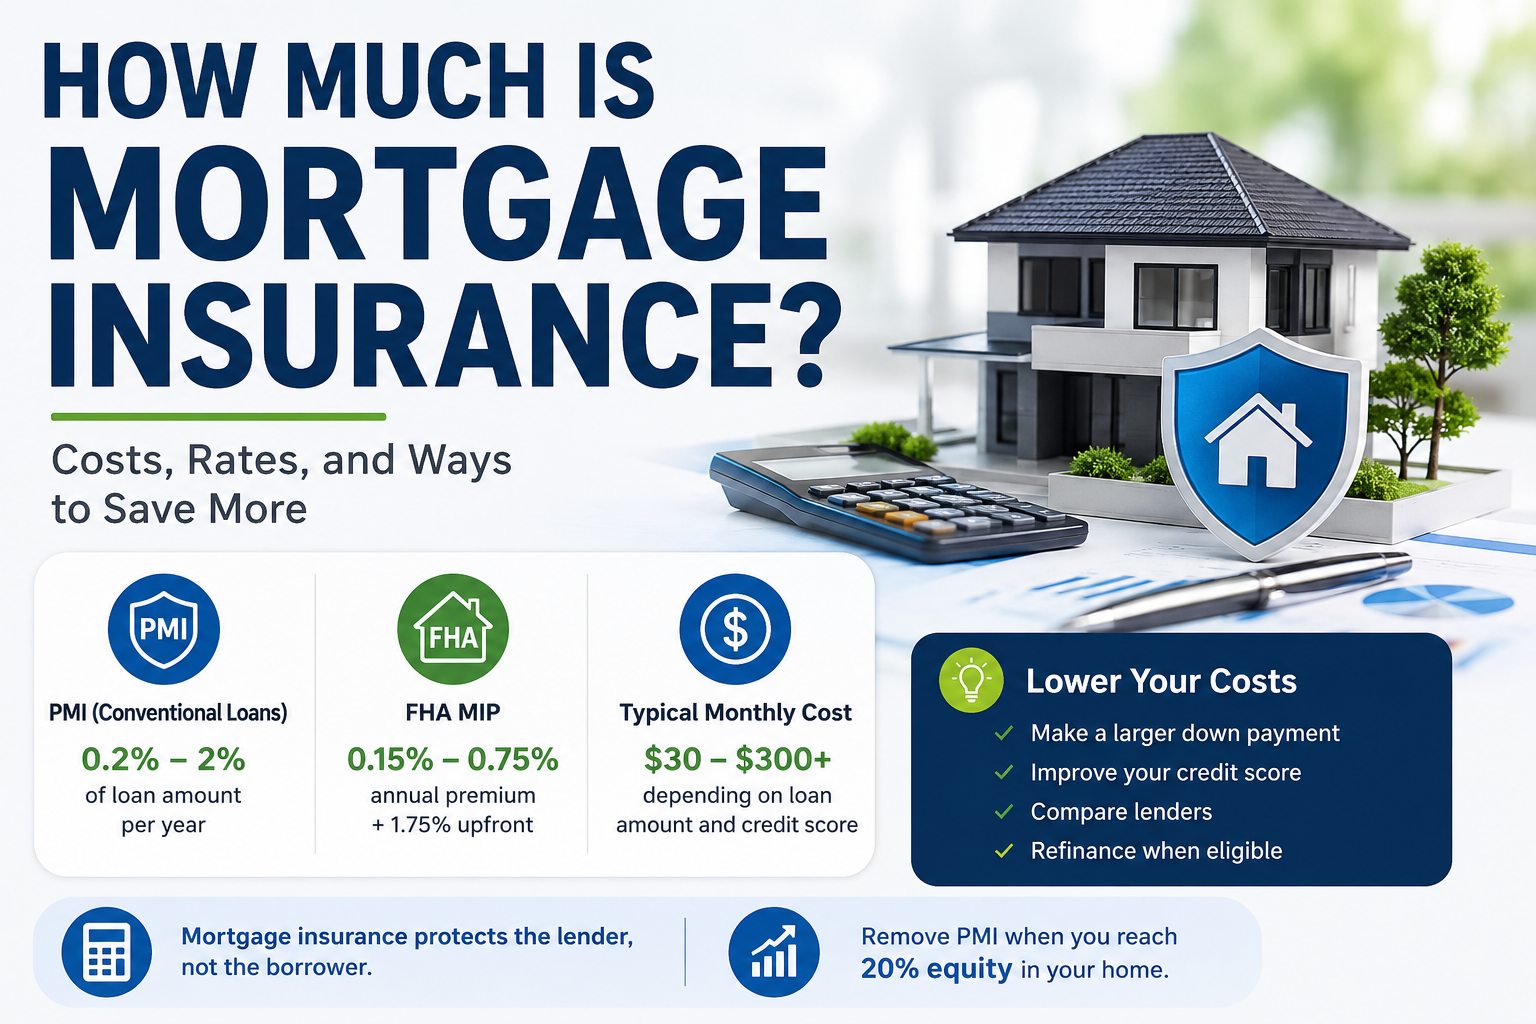
Buying a home often requires mortgage insurance, especially if your down payment is less than 20%. Understanding how much mortgage insurance costs can help you plan your monthly housing budget and avoid surprises during the home-buying process.
What Is Mortgage Insurance?
Mortgage insurance protects the lender if a borrower fails to make mortgage payments. It is commonly required for conventional loans with less than a 20% down payment and for most FHA loans.
There are two main types:
- Private Mortgage Insurance (PMI) for conventional loans
- Mortgage Insurance Premium (MIP) for FHA loans
How Much Does Mortgage Insurance Cost?
The cost of mortgage insurance varies based on factors such as loan amount, credit score, loan term, and down payment.
Private Mortgage Insurance (PMI)
PMI typically costs between 0.2% and 2% of the original loan amount per year.
Example:
- Loan Amount: $300,000
- PMI Rate: 0.5%
- Annual PMI Cost: $1,500
- Monthly PMI Cost: $125
Borrowers with higher credit scores usually qualify for lower PMI rates.
FHA Mortgage Insurance Premium (MIP)
FHA loans generally require:
- An upfront MIP of 1.75% of the loan amount
- An annual MIP ranging from 0.15% to 0.75%
For a $300,000 FHA loan, annual MIP may cost between $450 and $2,250 per year.
Factors That Affect Mortgage Insurance Costs
1. Down Payment Size
A larger down payment reduces risk and can lower mortgage insurance costs.
2. Credit Score
Higher credit scores often lead to lower PMI premiums.
3. Loan Amount
Larger loans typically result in higher insurance payments.
4. Loan Type
Conventional and FHA loans use different insurance structures.
5. Loan Term
Longer loan terms may have different premium rates.
Can Mortgage Insurance Be Removed?
For conventional loans, PMI can usually be removed once you reach 20% equity in your home. Many lenders automatically cancel PMI when your loan balance reaches 78% of the home’s original value.
For FHA loans, MIP removal depends on the loan origination date and down payment amount.
Ways to Lower Mortgage Insurance Costs
- Make a larger down payment.
- Improve your credit score before applying.
- Consider lender-paid mortgage insurance options.
- Refinance once you build enough home equity.
- Compare loan offers from multiple lenders.
Conclusion
Mortgage insurance typically costs between 0.2% and 2% of your loan amount annually for conventional loans, while FHA loans have both upfront and annual insurance premiums. Understanding these costs can help you choose the best mortgage and manage your homeownership expenses effectively.
FAQs
How much is mortgage insurance per month?
Mortgage insurance often ranges from $30 to several hundred dollars per month depending on your loan amount, credit score, and down payment.
Is mortgage insurance required?
It is usually required when a conventional loan has less than a 20% down payment or when using an FHA loan.
Can I avoid mortgage insurance?
Yes. Making a down payment of at least 20% on a conventional mortgage can help you avoid PMI.
Does mortgage insurance protect the homeowner?
No. Mortgage insurance protects the lender, not the borrower.
When does PMI go away?
PMI can typically be removed when you reach 20% equity in your home and is often automatically canceled at 22% equity.
Is FHA mortgage insurance permanent?
Not always. The duration depends on your down payment and FHA loan terms.






