
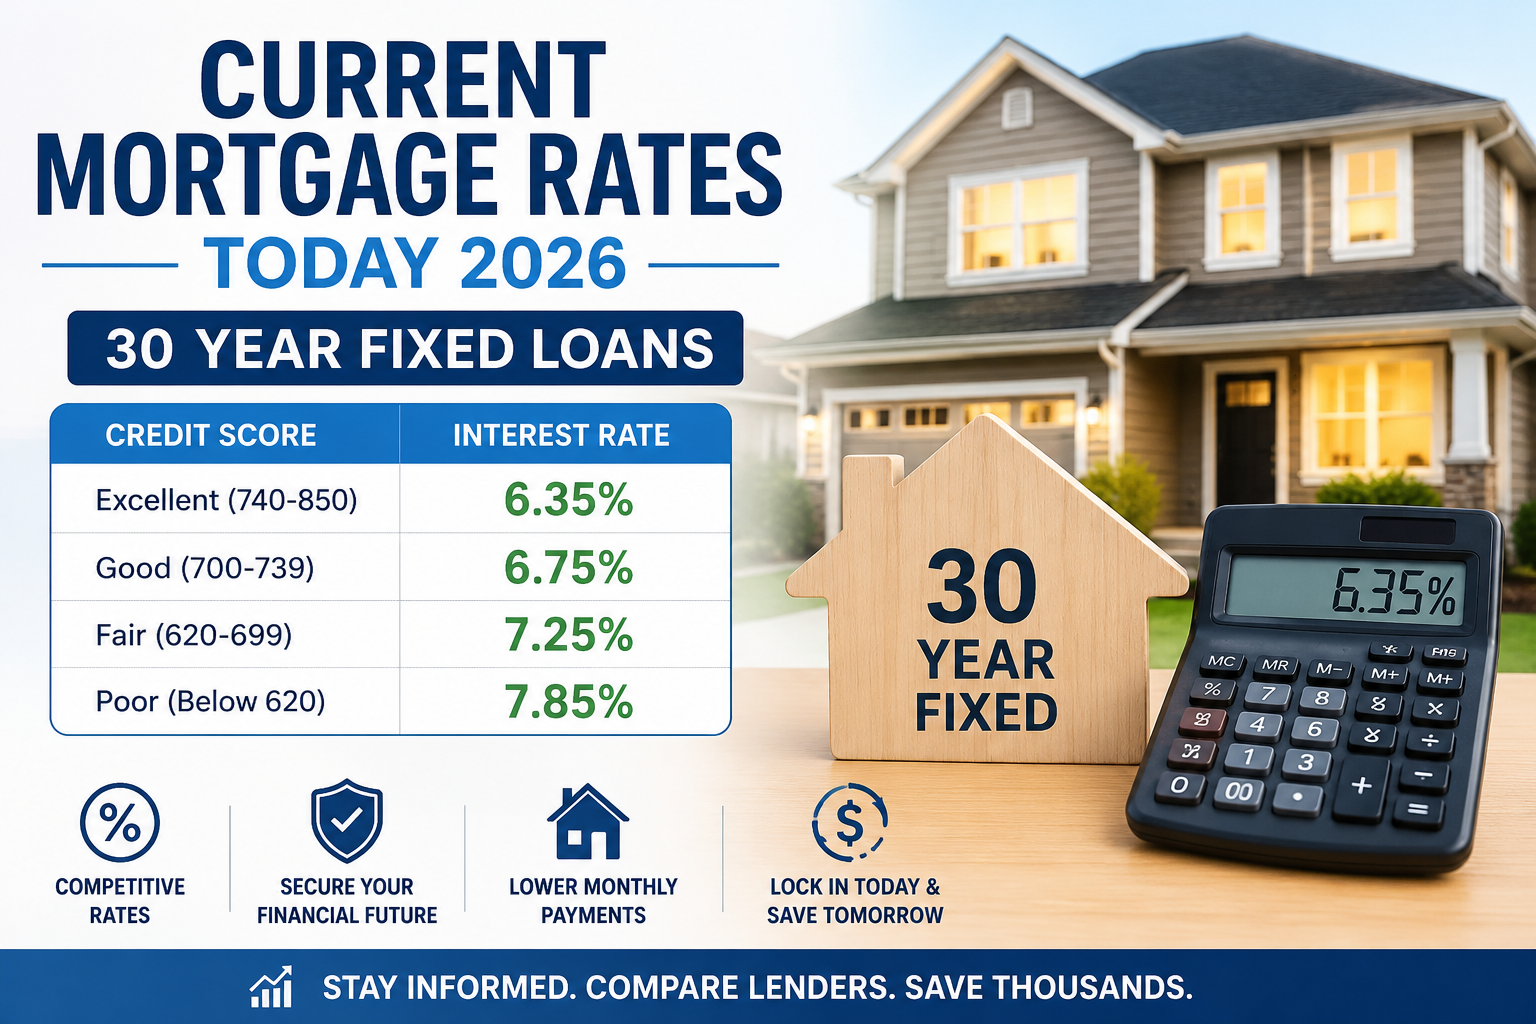
Understanding current mortgage rates today 2026 is essential if you are buying a home, refinancing, or planning your long-term finances. The 30 year fixed mortgage continues to be the most popular loan because it offers stable monthly payments over a long period.
Even small changes in rates can affect your monthly payments and the total cost of your home. This guide explains today’s 30 year fixed mortgage rates, trends, and how to make smart decisions.
What Are Current Mortgage Rates Today 2026
Mortgage rates today 2026 reflect the interest rates lenders are offering. They are influenced by bond markets, inflation, Federal Reserve policies, and lender demand.
The 30 year fixed mortgage gives borrowers predictable payments for the full term, making it ideal for budget planning. Current rates are generally in the mid 6 percent range, but your personal rate may vary depending on credit score, down payment, and location.
Why the 30 Year Fixed Mortgage Is Popular
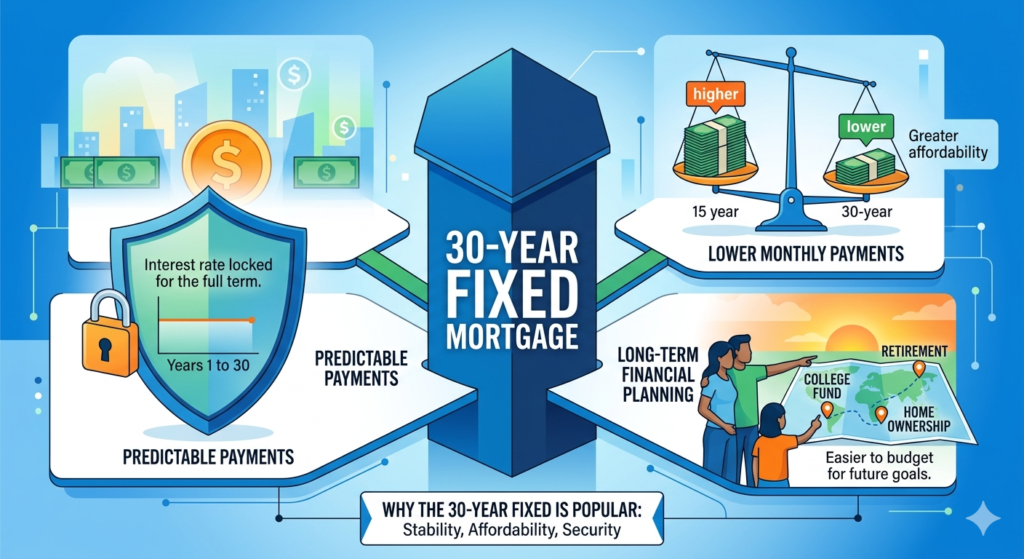
The 30 year fixed mortgage is popular because:
- Stable Payments: Your monthly principal and interest remain the same.
- Lower Monthly Payment: Compared to a 15 year mortgage, the payments are smaller.
- Budget Flexibility: It allows more room for other expenses or savings.
While the tradeoff is higher total interest over the life of the loan, many buyers value the predictability and flexibility.
Factors That Affect Mortgage Rates
Mortgage rates respond to both market and personal factors:
- Inflation: Higher inflation usually leads to higher rates.
- Bond Market: Rates often track the 10 year Treasury yield.
- Federal Reserve Policy: Fed actions influence overall borrowing costs.
- Credit Score and Debt: Better credit and lower debt improve your chances of a lower rate.
- Down Payment: Larger down payments reduce lender risk and may lead to better rates.
2026 Trends for 30 Year Fixed Mortgages
Rates in 2026 have generally remained above the lows seen in prior years. Buyers FHA mortgage brokers should shop around because even a small difference in rate can save thousands over the life of a loan.
Buying a Home When Rates Are High
High rates may feel challenging, but home purchases can still make sense:
- Focus on affordability, not predictions.
- Ensure monthly payments fit comfortably within your budget.
- Consider long-term plans and homeownership goals.
Refinancing in 2026
Refinancing can make sense if:
- Your current rate is higher than today’s rates.
- You want to switch to a fixed rate or shorten your loan term.
- You plan to remove mortgage insurance or access equity.
Always compare closing costs with expected savings before making a decision.
How to Get the Best Rate
- Compare multiple lenders.
- Check both interest rate and annual percentage rate (APR).
- Improve credit score and reduce debt.
- Consider a larger down payment.
- Ask about discount points and rate lock options.
30 Year vs 15 Year Fixed
- 30 Year Fixed: Lower monthly payment, predictable, flexible.
- 15 Year Fixed: Higher monthly payment, lower interest over time.
Choose based on your budget, goals, and comfort level.
Conclusion
Current mortgage rates in 2026 for 30-year fixed loans remain a key factor for homebuyers and refinancers looking to secure affordable financing. While rates may fluctuate based on inflation, market trends, and economic conditions, staying updated helps borrowers make smarter financial decisions. Whether you’re planning to buy a new home or refinance an existing mortgage, comparing lenders and locking in the right rate at the right time can lead to significant long-term savings.
FAQs
1. What are current mortgage rates today 2026 for 30 year fixed loans?
Generally mid 6 percent, depending on credit, down payment, and lender.
2. Should I wait for rates to drop before buying?
Rates may fall, but home prices and inventory may also change. Focus on affordability.
3. Is refinancing worth it?
Refinance if it lowers your payment, removes insurance, or fits your financial goals.
4. How can I get a lower mortgage rate?
Improve credit score, save for a larger down payment, and compare lenders.
5. Do mortgage rates change daily?
Yes, rates fluctuate based on market conditions and economic news.
6. What is the difference between interest rate and APR?
The interest rate is the loan cost, while APR includes certain fees for comparison.
7. Is a 30 year fixed mortgage still a good choice in 2026?
Yes, if you want stable payments and long-term budget flexibility.






