What Is a Non-QM Mortgage and Who Might Benefit From One? A Non-QM mortgage is a home loan that does not meet the specific requirements for a Qualified Mortgage (QM). That does not automatically mean the loan is unsafe or that the borrower cannot afford it. Instead, Non-QM loans are designed for borrowers whose financial situations may not fit neatly into conventional underwriting rules.
For example, a self-employed business owner may have strong cash flow and substantial assets but show less qualifying income on a traditional tax return because of legitimate business deductions. A real estate investor, retiree, or borrower with substantial assets but unusual income may face a similar problem.
The Consumer Financial Protection Bureau (CFPB) explains that lenders generally must make a reasonable, good-faith determination that a borrower can repay a mortgage. Non-QM loans can be used when a mortgage has characteristics that make it ineligible to be a Qualified Mortgage.

What Is a Non-QM Mortgage?
A Non-QM Mortgage is a residential mortgage that does not satisfy the requirements used to classify a loan as a Qualified Mortgage.
The important distinction is that Non-QM does not mean “no rules.” Lenders still need to evaluate whether the borrower has the ability to repay the loan under applicable federal requirements and their own underwriting standards. The CFPB states that the Ability-to-Repay rule generally requires creditors to make a reasonable and good-faith determination of a consumer\’s ability to repay.
A traditional mortgage application often emphasizes standardized documentation such as:
- W-2 income
- Recent pay stubs
- Tax returns
- Employment history
- Credit history
- Monthly debt obligations
- Bank and investment assets
That system works well for many employees with predictable salaries. But it can become complicated when income is seasonal, business-related, commission-based, investment-driven, or otherwise difficult to document using conventional methods.
A Non-QM mortgage may give the lender additional ways to evaluate the borrower\’s financial strength.
How Is a Non-QM Loan Different From a QM Loan?
A Qualified Mortgage is a loan that meets specific regulatory requirements and receives certain legal protections for the creditor. The CFPB notes that QM loans are generally associated with less risky loan features and requirements intended to make repayment more manageable.
A Non-QM loan falls outside those QM criteria.
That difference can give lenders more flexibility, but it may also mean:
- Higher interest rates
- Higher fees
- Larger down-payment requirements
- More extensive asset documentation
- Stricter lender-specific requirements
- Fewer available lenders or loan products
The exact terms vary considerably by lender and borrower.
[ Guide to Mortgage Qualification Requirements]
How Does a Non-QM Mortgage Work?
The basic process looks similar to other mortgage applications, but the underwriting approach can be different.
Instead of relying only on conventional income documentation, a Non-QM lender may examine a broader picture of the borrower\’s financial position.
1. The Lender Reviews Your Financial Profile
The lender may review:
- Income
- Assets
- Credit score and credit history
- Existing debts
- Property type
- Down payment
- Reserves
- Employment or business history
- Investment or rental income
The lender\’s goal is to determine whether the proposed mortgage payment is reasonably supported by the borrower\’s financial circumstances.
Federal rules specifically require creditors making an ability-to-repay determination to consider factors such as income or assets, debt obligations, and other relevant financial information.
2. The Lender Uses an Alternative Documentation Method
One of the biggest differences is how income or financial strength may be documented.
Depending on the loan program, a lender might consider:
- Bank statements
- Business bank statements
- Investment account assets
- Rental income
- Real estate cash flow
- Retirement assets
- Other documented sources of funds
This does not mean borrowers can simply state an income number without evidence. Non-QM underwriting still involves documentation and lender-specific verification.
3. The Property Is Evaluated
The lender will also consider the property securing the loan.
Factors can include:
- Property value
- Loan-to-value ratio
- Property type
- Occupancy
- Location
- Condition
- Marketability
An appraisal or other acceptable valuation method may be required depending on the loan.
4. The Loan Is Priced According to Risk
Because Non-QM mortgages can involve borrowers or situations that do not fit standardized underwriting models, pricing may be different from a conventional mortgage.
A borrower with excellent credit, substantial reserves, and a large down payment may receive substantially different terms from a borrower with weaker credit and limited reserves.
This is why comparing several offers matters.
Who Might Benefit From a Non-QM Mortgage?
A Non-QM mortgage may be useful for borrowers with strong financial resources who do not fit traditional underwriting requirements.
Self-Employed Borrowers
Self-employed borrowers are one of the groups that may explore Non-QM financing.
A business owner can have significant money flowing through a company while reporting lower taxable income after legitimate business deductions.
For example, imagine a business owner earns substantial gross revenue but has considerable deductible expenses. A conventional underwriting process may focus heavily on the income shown on tax documents. A Non-QM program may offer an alternative way to document cash flow, depending on the lender and product.
That does not guarantee approval. The lender will still evaluate the business, bank activity, credit, assets, and overall ability to repay.
Real Estate Investors
Real estate investors may have income from multiple properties rather than one traditional employer.
Their financial profile can include:
- Rental income
- Multiple mortgages
- Property expenses
- Investment accounts
- Business income
- Equity in existing properties
Some Non-QM programs are structured to evaluate investment-property cash flow rather than relying exclusively on traditional employment income.
Retirees and Asset-Rich Borrowers
Someone who is retired may have substantial investments and savings but little or no traditional employment income.
A borrower might receive money from:
- Retirement accounts
- Investment portfolios
- Social Security
- Pensions
- Rental properties
- Other documented assets
Depending on the program, a lender may consider assets or alternative income calculations when evaluating repayment ability.
Borrowers With Nontraditional Income
Some people earn income that does not fit neatly into a standard W-2 employment model.
Examples include:
- Freelancers
- Consultants
- Commission-based workers
- Business owners
- Contractors
- Entrepreneurs
- Investors
For these borrowers, the issue may not be a lack of money. The challenge can be documenting stable qualifying income using a conventional formula.
Borrowers With Unique Financial Circumstances
Non-QM financing may also be considered when a borrower\’s circumstances are outside typical underwriting parameters.
However, flexibility should never be confused with guaranteed approval. A lender still has to determine that the loan is appropriate under its underwriting and applicable legal requirements.
The CFPB\’s own assessment of the ATR/QM rule has identified borrowers with irregular income, certain self-employed borrowers, and borrowers with limited credit history among groups that may have difficulty fitting standard mortgage channels.
[
What Types of Non-QM Mortgages Are Available?
“Non-QM” describes a category rather than one single mortgage product.
Different lenders offer different programs, and availability can change.
Bank Statement Loans
Bank statement programs may allow qualifying income to be evaluated using deposits shown in personal or business bank accounts.
These loans can be particularly relevant to self-employed borrowers whose tax returns do not fully reflect their available cash flow under conventional underwriting formulas.
However, lenders may analyze deposits carefully and may exclude certain transfers or deposits that do not represent qualifying income.
Asset-Based Loans
An asset-based mortgage may use eligible financial assets as part of the qualification process.
This can be relevant to borrowers with significant savings or investments but limited traditional employment income.
The lender may apply a specific calculation to eligible assets rather than simply treating the entire account balance as annual income.
Debt-Service-Coverage-Ratio Loans
A DSCR loan is commonly associated with real estate investors.
Instead of focusing primarily on the borrower\’s personal employment income, the lender may evaluate whether the property\’s expected rental income can support the property\’s debt obligations.
This can be particularly useful for investors purchasing rental properties.
Interest-Only Options
Some Non-QM products may offer an interest-only payment period.
This can reduce the initial monthly payment, but it is important to understand what happens when the interest-only period ends.
The future payment may increase significantly because principal repayment begins.
Other Alternative-Documentation Programs
Depending on the lender, Non-QM products may include other approaches to evaluating income, assets, credit history, or property cash flow.
Because Non-QM lending is not one standardized product, borrowers should review the actual loan terms rather than relying on the label alone.
What Are the Benefits of a Non-QM Mortgage?
The main advantage is flexibility.
A borrower who cannot qualify through a standard mortgage program may still have a path to homeownership or real estate financing if the lender can reasonably document the borrower\’s ability to repay.
Potential benefits include:
More Flexible Income Documentation
The lender may have more ways to evaluate financial strength than a standard W-2-based application.
Options for Self-Employed Borrowers
Business owners may have access to programs designed around their actual financial circumstances.
Financing for Investment Properties
Certain programs can focus on property cash flow, which may be more relevant to an investor than a conventional employment-based calculation.
Options for Asset-Rich Borrowers
Borrowers with significant assets but unconventional income may find programs that better reflect their financial position.
Solutions When Conventional Financing Does Not Fit
The biggest practical benefit may simply be having another option.
A borrower who has been declined for a conventional mortgage should not automatically assume that every mortgage option is unavailable. However, a Non-QM alternative should be evaluated carefully for affordability and total cost.
: Conventional vs. Non-QM Mortgage Guide]
What Are the Risks and Downsides?
Non-QM mortgages are not automatically better simply because they are more flexible.
In many cases, that flexibility comes with additional cost or risk.
Higher Interest Rates
Non-QM loans may carry higher interest rates than comparable conventional mortgages.
Even a small rate difference can have a meaningful impact on the total amount paid over the life of the loan.
Higher Fees
Borrowers may encounter higher origination costs, underwriting fees, or other charges.
The CFPB notes that Qualified Mortgages have specific points-and-fees restrictions, while loans that are not QMs do not receive the same QM points-and-fees treatment.
Larger Down Payments
Some Non-QM lenders may require more equity in the property.
A larger down payment can reduce the lender\’s risk but requires more cash from the borrower.
Adjustable or Interest-Only Payments
Some products can involve features that make future payments less predictable.
A lower initial payment is not necessarily a lower long-term cost.
Limited Lender Availability
Non-QM financing is a specialized market. Not every mortgage lender offers the same programs.
That means shopping around can be especially important.
More Complex Loan Terms
A borrower may need to pay closer attention to:
- Interest-rate structure
- Prepayment provisions
- Balloon-payment risks, if applicable
- Interest-only periods
- Reserve requirements
- Documentation requirements
- Total closing costs
The right question is not simply, “Can I qualify?”
It is:
“Can I comfortably afford this loan under its current and future terms?”
Non-QM Mortgage vs. Conventional Mortgage
The difference becomes easier to understand when you compare the two approaches.
| Feature | Conventional Mortgage | Non-QM Mortgage |
|---|---|---|
| Income documentation | Usually standardized | May allow alternative documentation |
| Self-employed borrowers | Can qualify, but documentation can be complex | May offer additional options |
| Investment property | Available under specific rules | May provide specialized investor programs |
| Interest rates | Often lower for strong borrowers | May be higher |
| Fees | Generally more standardized | Can be higher depending on lender |
| Underwriting | More standardized | More flexible |
| Availability | Widely available | More specialized |
| Best fit | Borrowers who fit conventional guidelines | Borrowers with unique financial profiles |
The important point is that Non-QM should not be viewed as a replacement for conventional financing.
If you qualify comfortably for a conventional mortgage with favorable terms, that may be the simpler and less expensive choice. Non-QM financing becomes more interesting when conventional underwriting does not accurately reflect your financial situation.
How Much Does a Non-QM Mortgage Cost?
There is no single Non-QM mortgage rate or fee.
Pricing depends on factors such as:
- Credit profile
- Down payment
- Loan amount
- Property type
- Occupancy
- Loan-to-value ratio
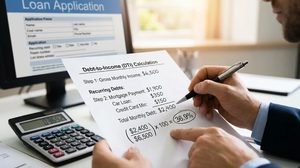
- Debt-to-income ratio
- Reserves
- Income documentation
- Loan structure
- Lender
For that reason, online rate advertisements should be treated as starting points rather than guaranteed offers.
When comparing loans, look beyond the interest rate.
Ask each lender for the:
- Interest rate
- Annual percentage rate (APR)
- Monthly principal and interest payment
- Estimated taxes and insurance
- Total closing costs
- Required cash to close
- Prepayment terms
- Future payment changes
- Reserve requirements
A lower rate with significantly higher upfront costs is not necessarily the better deal.
How to Qualify for a Non-QM Mortgage
Requirements differ from lender to lender, but borrowers can generally expect a review of their complete financial profile.
Credit
A lender will typically examine credit history and may establish minimum credit requirements.
A stronger credit profile can improve the available loan options and pricing.
Assets and Reserves
Some Non-QM programs place significant emphasis on liquid assets and reserves.
Having money left after closing can strengthen a borrower\’s application because it demonstrates additional financial capacity.
Down Payment
The required down payment depends on the specific program.
A larger down payment may improve the borrower\’s overall risk profile.
Income or Cash Flow
Alternative documentation does not mean no documentation.
The lender may examine bank statements, business records, rental income, investments, or other financial information depending on the program.
Property
The lender will assess whether the property is acceptable collateral under the program\’s guidelines.
Before applying, ask the lender for the complete eligibility criteria rather than assuming that one Non-QM program represents the entire market.
Mortgage Pre-Approval Checklist]
Is a Non-QM Mortgage Safe?
A Non-QM mortgage is not automatically unsafe, but borrowers should evaluate it more carefully because the terms can differ significantly from standard mortgages.
The CFPB explains that nonqualified mortgages can be riskier or more expensive and are generally used when a loan has characteristics that make it ineligible for a Qualified Mortgage.
Safety depends on the specific loan.
A borrower should be cautious if the loan has:
- A payment that is difficult to afford
- A rate that can increase substantially
- Large upfront costs
- An unaffordable future payment
- Unclear prepayment provisions
- Insufficient emergency reserves
Before signing, make sure you understand the payment today and the payment after any introductory or interest-only period.
When Should You Consider a Non-QM Mortgage?
A Non-QM mortgage may make sense when all three of these conditions are present:
1. You have the financial ability to repay the loan.
You should have reliable resources to cover the mortgage and your other obligations.
2. A conventional loan does not accurately fit your financial situation.
For example, your income may be difficult to document using conventional methods even though your overall finances are strong.
3. The Non-QM terms are reasonable for your situation.
Flexibility is not worth accepting a payment that puts your finances under unnecessary pressure.
A Practical Example
Consider a self-employed consultant who earns substantial business revenue but has income that appears lower on tax returns because of legitimate deductions.
The borrower has:
- Strong credit
- Significant savings
- Several years of business history
- A substantial down payment
- Consistent deposits into business accounts
A conventional lender may calculate qualifying income differently from the way the borrower\’s actual cash flow looks.
A Non-QM lender may have an alternative documentation method that better captures the borrower\’s financial capacity.
This example illustrates the central value of Non-QM lending: the goal is not to ignore underwriting, but to evaluate a borrower whose finances do not fit neatly into a standardized box.
Questions to Ask a Non-QM Lender
Before accepting an offer, ask:
- Why does this loan need to be Non-QM?
- What documentation will you use to calculate my income?
- What is the interest rate and APR?
- Can the interest rate change?
- Will my payment increase later?
- What are the total closing costs?
- Are there prepayment penalties?
- How much cash must I keep in reserves?
- What happens if my income changes?
- Is there a conventional or government-backed alternative I should compare?
These questions can reveal whether the loan solves a genuine financing problem or simply makes borrowing easier at a higher cost.
Where Can Borrowers Learn More?
Mortgage rules can be complicated, so borrowers should rely on authoritative sources as well as their lender\’s disclosures.
The CFPB\’s official resources explain the Ability-to-Repay and Qualified Mortgage framework, including applicable regulations and interpretations.
You can review the CFPB Ability-to-Repay and Qualified Mortgage resources and the CFPB guide to Qualified Mortgages before comparing loan offers.

Final Thoughts
A Non-QM Mortgage can provide an important financing option for borrowers whose financial lives do not fit traditional mortgage underwriting.
Self-employed professionals, real estate investors, retirees with substantial assets, and borrowers with unconventional income may benefit from the flexibility these loans can provide.
But flexibility has a price. Non-QM loans can come with higher rates, fees, larger down payments, or more complicated terms than conventional financing.
The smartest approach is to compare the complete cost and risk of the loan—not just whether you can get approved.
If a Non-QM mortgage is being considered, ask the lender to explain exactly how your income is calculated, why the loan is classified as Non-QM, what your payment will be over time, and whether a conventional or government-backed alternative is available.
3. FAQ Section
What is a Non-QM Mortgage?
A Non-QM Mortgage is a home loan that does not meet the regulatory requirements for a Qualified Mortgage. It may use alternative underwriting methods to evaluate borrowers with financial circumstances that do not fit standard mortgage guidelines.
Who might benefit from a Non-QM Mortgage?
Self-employed borrowers, real estate investors, retirees with substantial assets, and people with unconventional income may benefit when traditional mortgage underwriting does not accurately reflect their financial situation.
Are Non-QM mortgages more expensive?
They can be. Non-QM loans may have higher interest rates, fees, down-payment requirements, or reserve requirements than conventional mortgages. Actual pricing depends on the lender and borrower.
Can self-employed people get a Non-QM mortgage?
Yes. Some Non-QM programs are specifically designed for borrowers whose income is difficult to document through conventional W-2 and tax-return methods. Approval still depends on the lender\’s underwriting requirements.
Is a Non-QM mortgage risky?
A Non-QM mortgage is not automatically risky, but some products can have higher costs or more complex terms than standard mortgages. Borrowers should evaluate the interest rate, APR, payment structure, fees, reserves, and future payment obligations.
How do I know if a Non-QM mortgage is right for me?
Compare it with conventional and government-backed mortgage options. A Non-QM loan may be worth considering when you have the ability to repay but cannot qualify under standard guidelines or when an alternative underwriting method better reflects your finances.