
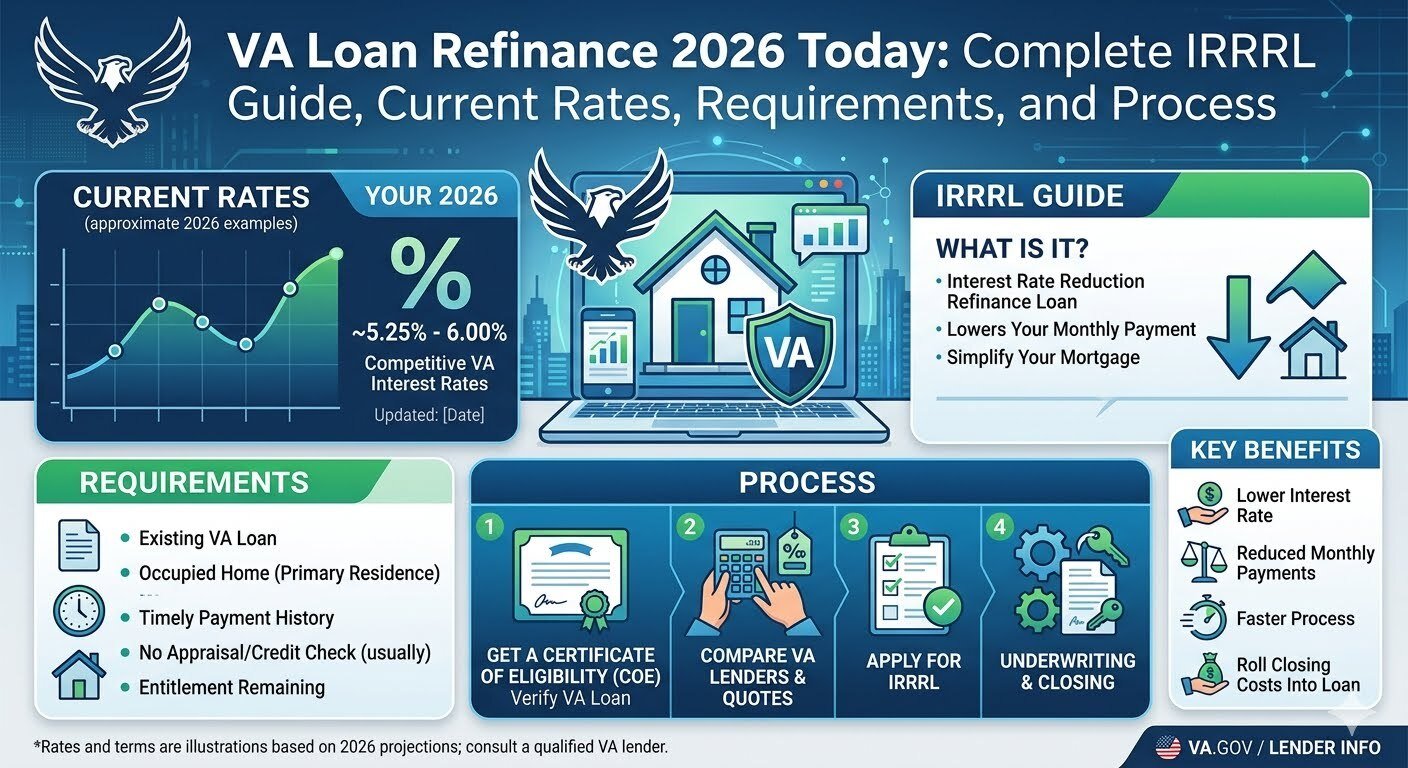
Learn everything about VA Loan Refinance 2026 including IRRRL rates, eligibility, requirements, costs, benefits, and how to refinance your VA home loan today.
VA Loan Refinance 2026: Complete IRRRL Guide and Current Rates
Refinancing a VA home loan can help eligible veterans, service members, and surviving spouses lower their monthly mortgage payment or achieve other financial goals. If you already have a VA mortgage, the VA Loan Refinance 2026 program offers valuable opportunities, especially through the Interest Rate Reduction Refinance Loan (IRRRL).
This guide explains how the VA refinance process works, who qualifies, current rate trends, closing costs, and how to decide if refinancing makes sense in 2026.
What Is a VA Loan Refinance?
A VA Loan Refinance allows qualified borrowers to replace an existing mortgage with a new loan that offers better terms. Many homeowners refinance to secure a lower interest rate, reduce monthly payments, or change the length of their loan.
The Department of Veterans Affairs guarantees VA loans, making it easier for eligible borrowers to qualify for competitive mortgage rates.
Common Reasons to Refinance
- Lower your interest rate
- Reduce your monthly payment
- Switch to a fixed interest rate
- Shorten your loan term
- Access home equity through a Cash Out Refinance
- Replace a non VA loan with a VA loan
What Is an IRRRL?
The Interest Rate Reduction Refinance Loan, also known as IRRRL, is a simplified refinance program for existing VA borrowers.
Many lenders call it the VA Streamline Refinance because the process is often faster than a traditional refinance.
Benefits of an IRRRL
- Less paperwork
- No appraisal may be required
- Lower interest rates may be available
- Reduced monthly mortgage payment
- Faster loan approval in many cases
- Limited closing costs
VA Loan Refinance Rates in 2026
Mortgage rates continue to change based on market conditions, inflation, and Federal Reserve policy. While no lender can guarantee the lowest rate, VA loans often offer lower interest rates than many conventional mortgage programs.
Your final rate depends on factors including:
- Credit score
- Loan amount
- Home value
- Loan term
- Lender pricing
- Current market conditions
Comparing several VA approved lenders can help you secure a competitive refinance rate.
Who Is Eligible for a VA Loan Refinance?
To qualify for an IRRRL, you generally must:
Have an Existing VA Loan
The current mortgage being refinanced must already be a VA loan.
Be Current on Mortgage Payments
Most lenders want to see a solid payment history with no recent late payments.
Receive a Financial Benefit
The refinance should provide a clear benefit, such as lowering your interest rate or reducing your monthly payment.
Meet Lender Requirements
Although VA guidelines are flexible, each lender may have additional requirements for income, credit, or documentation.
Steps to Refinance Your VA Loan
Step 1: Review Your Current Mortgage
Check your current interest rate, loan balance, monthly payment, and remaining loan term.
Step 2: Compare VA Refinance Rates
Request quotes from several lenders before making a decision.
Step 3: Gather Your Documents
You may need:
- Government identification
- Mortgage statement
- Income documents if required
- Homeowners insurance information
Step 4: Submit Your Application
Complete the lender application and provide any requested documentation.
Step 5: Close Your New Loan
Once approved, you will sign the closing documents and your new mortgage replaces the previous loan.
IRRRL vs Cash Out Refinance
IRRRL
- Only for existing VA loans
- Designed to lower interest rates
- Usually requires less paperwork
- Does not provide significant cash from home equity
VA Cash Out Refinance
- Available for VA and some non VA loans
- Allows homeowners to access home equity
- May require a home appraisal
- Often involves additional documentation
If your goal is simply lowering your payment, an IRRRL is often the easier choice.
VA Loan Refinance Costs
Even though VA refinancing can save money, there are still costs to consider.
Typical expenses include:
- VA funding fee when applicable
- Loan origination fee
- Title services
- Recording fees
- Interest paid before the first payment
- Other lender charges
Many borrowers choose to include eligible closing costs in the new loan instead of paying them upfront.
Is Refinancing Worth It in 2026?
A refinance may be a smart financial decision if you can:
- Lower your monthly mortgage payment
- Save money on interest over time
- Improve your long term financial goals
- Switch from a variable rate to a fixed rate
- Reduce your loan term
However, refinancing may not be the best choice if you plan to move soon or if the closing costs outweigh the potential savings.
A mortgage professional can help calculate your break even point before you refinance.
Tips for Getting the Best VA Refinance Rate
Improve Your Credit Score
A stronger credit profile may help you receive better loan pricing.
Compare Multiple Lenders
Different lenders offer different rates and closing costs.
Lock Your Interest Rate
If rates are favorable, consider locking your rate during the application process.
Review All Loan Fees
Do not focus only on the interest rate. Compare the total cost of each loan offer.
Frequently Asked Questions
Is an IRRRL only for existing VA loans?
Yes. An IRRRL is available only to borrowers who already have a VA mortgage.
Do I need a home appraisal?
Many IRRRL loans do not require an appraisal, although some lenders may request one.
Can I refinance if my credit score has changed?
Many lenders have flexible requirements, but approval depends on your complete financial profile.
How long does a VA refinance take?
Many refinance loans close within several weeks, depending on the lender and your documentation.
Can I roll closing costs into the new loan?
In many cases, eligible closing costs can be included in the refinance loan amount.
Does refinancing reset my mortgage?
Yes. Your new refinance loan replaces your existing mortgage and begins with new loan terms.
Can I refinance from a conventional loan to a VA loan?
Yes. Eligible borrowers may use a VA Cash Out Refinance to replace a conventional mortgage with a VA loan.
Conclusion
A VA Loan Refinance 2026 can help eligible homeowners reduce monthly payments, secure a better interest rate, or improve their mortgage terms. The IRRRL program remains one of the easiest ways for existing VA borrowers to refinance because it offers a simplified process and fewer documentation requirements.
Before choosing a lender, compare current VA refinance rates, review all loan costs, and calculate your potential savings. With careful planning, refinancing your VA mortgage could provide meaningful financial benefits for years to come.






