
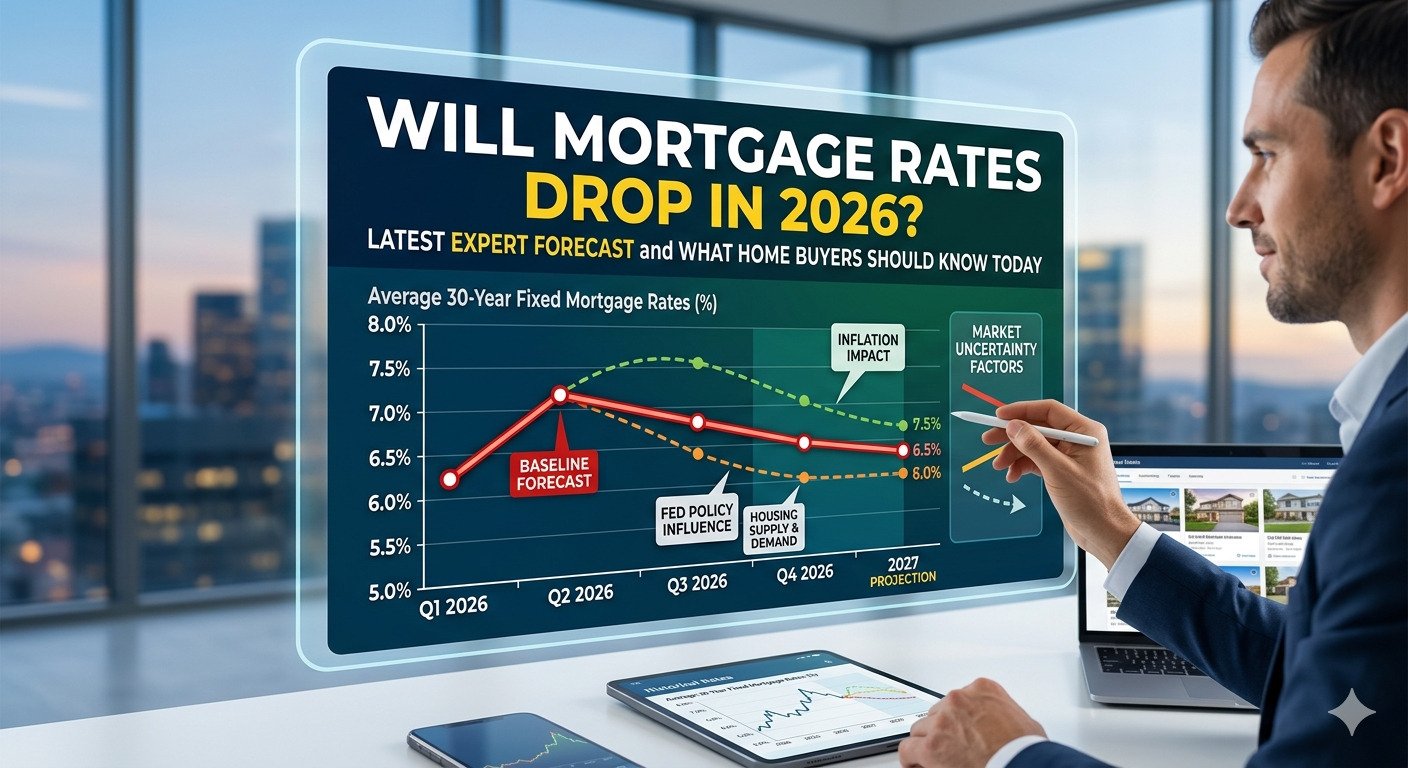
Will mortgage rates drop in 2026? Discover the latest expert forecast, market trends, and tips for home buyers and homeowners planning to buy or refinance.
Will Mortgage Rates Drop in 2026? Expert Forecast
Buying a home is one of the biggest financial decisions most people will ever make. After several years of changing interest rates, many buyers and homeowners are asking one important question: Will mortgage rates drop in 2026?
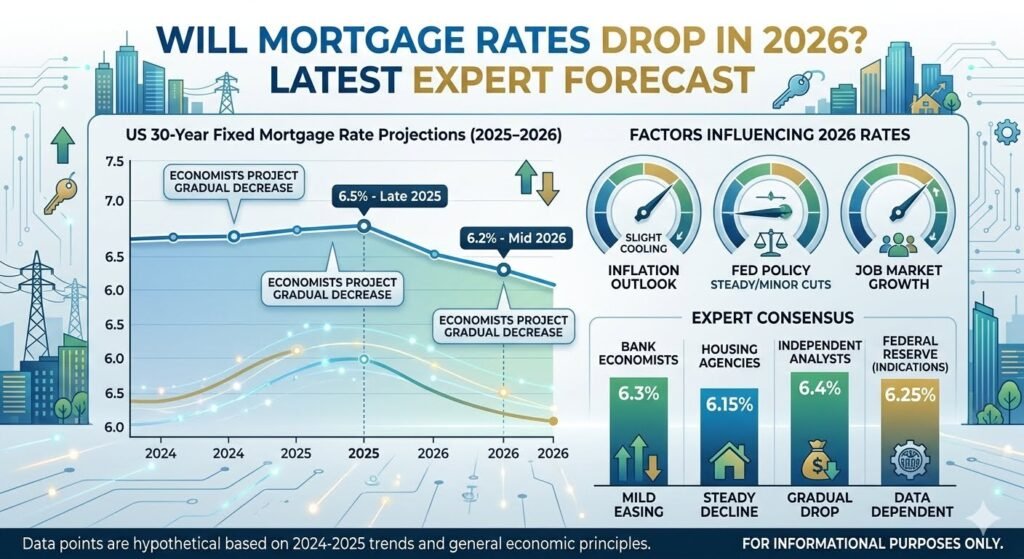
The answer is not simple because mortgage rates depend on several economic factors, including inflation, Federal Reserve policy, employment data, and the overall housing market. While no one can predict future rates with complete certainty, many housing economists believe that mortgage rates could gradually decline during 2026 if inflation continues to ease and the economy remains stable.
This guide explains what experts expect, what affects mortgage rates, and how buyers can prepare for the market.
Why Mortgage Rates Matter
Mortgage rates determine how much you pay each month for your home loan. Even a small difference in the interest rate can save or cost thousands of dollars over the life of a mortgage.
Lower mortgage rates can:
- Reduce monthly payments
- Increase buying power
- Lower the total cost of borrowing
- Make refinancing more attractive
Higher rates have the opposite effect, making homes more expensive to finance.
What Influences Mortgage Rates?
Mortgage rates change because of many economic conditions.
Inflation
Inflation is one of the biggest drivers of mortgage rates.
When inflation rises, lenders usually increase interest rates to reduce risk. When inflation slows, mortgage rates often become more affordable.
Federal Reserve Policy
Although the Federal Reserve does not directly set mortgage rates, its decisions about short term interest rates strongly influence the mortgage market.
If the Federal Reserve lowers interest rates during 2026, mortgage rates could also move lower.
Bond Market Performance
Mortgage rates generally follow the yield on the ten year Treasury bond. When Treasury yields decline, mortgage rates often follow.
Housing Market Demand
Strong demand for homes may keep mortgage activity high. Slower home sales can encourage lenders to offer more competitive mortgage rates.
Expert Forecast for Mortgage Rates in 2026
Many economists expect mortgage rates to remain relatively stable with the possibility of gradual declines during 2026.
Most forecasts suggest:
- Rates may decrease slowly instead of falling quickly.
- Inflation will remain an important factor.
- Economic growth will influence lender pricing.
- Market conditions may create temporary increases and decreases throughout the year.
Rather than expecting dramatic drops, buyers should prepare for modest improvements if economic conditions remain favorable.
Could Mortgage Rates Fall Below Six Percent?
Many home buyers hope mortgage rates will return to levels below six percent.
While this is possible, it depends on several conditions:
Lower Inflation
A steady decline in inflation would improve the chances of lower mortgage rates.
Stable Economy
A balanced economy without significant financial disruptions may support lower borrowing costs.
Federal Reserve Rate Cuts
Additional interest rate reductions by the Federal Reserve could place downward pressure on mortgage rates.
Although some analysts believe rates could eventually move below six percent, there is no guarantee this will happen during 2026.
What This Means for Home Buyers
Waiting for lower rates may not always be the best strategy.
Home prices may continue increasing in many markets, meaning buyers could pay more for the same property even if interest rates decline later.
Buying sooner may allow buyers to:
- Build home equity earlier
- Lock in today’s home prices
- Refinance later if rates fall
Every buyer should evaluate both home prices and mortgage rates together.
Should Homeowners Wait to Refinance?
Homeowners considering refinancing should compare their current mortgage with available rates.
Refinancing may make sense if it can:
- Lower monthly payments
- Reduce the loan term
- Eliminate mortgage insurance
- Provide cash for home improvements
Waiting for slightly lower rates may benefit some homeowners, but delaying too long could mean missing favorable market opportunities.
Tips for Getting the Best Mortgage Rate
Regardless of market conditions, borrowers can improve their chances of receiving competitive mortgage rates.
Improve Your Credit Score
Higher credit scores usually qualify for lower interest rates.
Save for a Larger Down Payment
More equity reduces lender risk and may lead to better loan terms.
Reduce Existing Debt
Lower debt improves your debt to income ratio.
Compare Multiple Lenders
Request loan estimates from several lenders before making a final decision.
Lock Your Interest Rate
If you find a competitive rate, consider locking it before market conditions change.
Is Now a Good Time to Buy?
The best time to buy depends on your personal finances rather than trying to predict the market perfectly.
Consider buying if:
- You have stable income.
- Your credit is in good shape.
- You have enough savings for the down payment.
- You plan to stay in the home for several years.
Trying to perfectly time mortgage rates is difficult. Buying when you are financially ready is often the better decision.
Internal Linking Suggestions
Link this article to related pages such as:
- Current Mortgage Rates Today
- Mortgage Calculator
- FHA Loan Requirements
- VA Mortgage Guide
- Conventional Loan Guide
- Home Buying Tips
- Mortgage Refinancing Guide
Frequently Asked Questions
Will mortgage rates drop in 2026?
Many experts expect gradual declines if inflation continues to improve, but no forecast is guaranteed.
What affects mortgage rates the most?
Inflation, Federal Reserve policy, Treasury bond yields, and overall economic conditions all influence mortgage rates.
Should I wait for lower mortgage rates?
Waiting could help if rates decline, but rising home prices may reduce those savings.
Can I refinance if rates fall later?
Yes. Many homeowners refinance when lower rates become available.
Will mortgage rates return to historic lows?
Most economists do not expect rates to return to the extremely low levels seen several years ago in the near future.
How can I qualify for the lowest mortgage rate?
Improve your credit score, reduce debt, increase your down payment, and compare multiple lenders.
Is refinancing worth it in 2026?
It depends on your current interest rate, closing costs, and long term financial goals.
Conclusion
The outlook for mortgage rates in 2026 is encouraging but uncertain. Most experts expect rates to move gradually lower if inflation continues to cool and the economy remains stable. However, buyers should avoid making decisions based only on predictions.
Instead, focus on improving your financial profile, comparing lenders, and choosing a mortgage that fits your budget. Whether rates fall slightly or remain stable, being financially prepared will put you in the best position to achieve your homeownership goals.






