
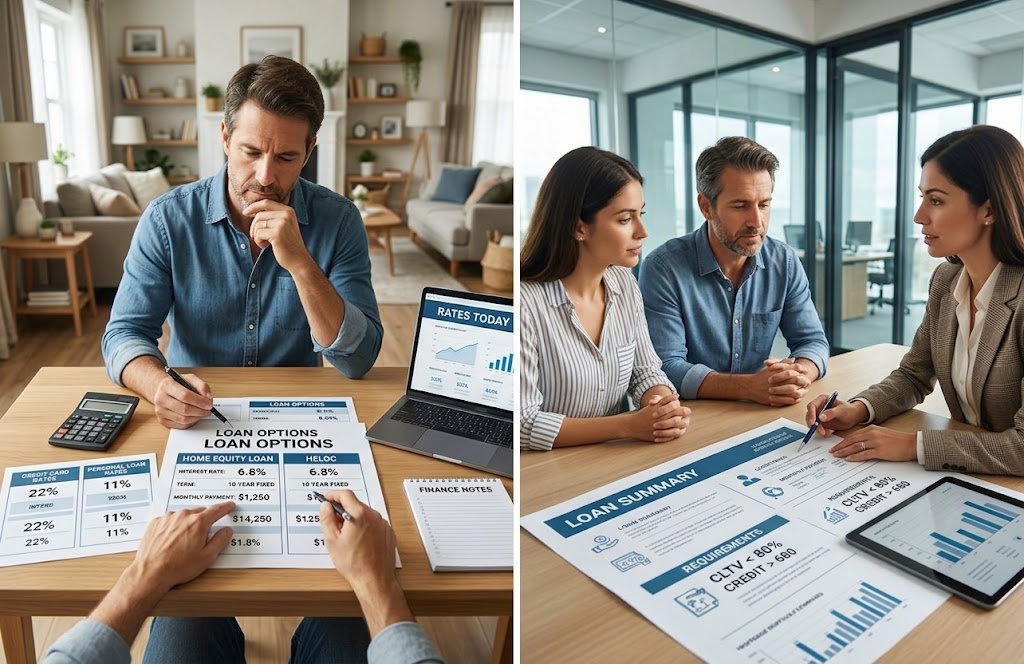
A Home Equity Loan: How It Works, Rates & Requirements guide can help homeowners understand how to access the value they have built in their property without selling it. If your home is worth more than what you still owe on your mortgage, that difference is your home equity.
A home equity loan allows you to borrow against that equity, usually receiving the money as a lump sum and repaying it through scheduled monthly payments. Unlike a HELOC, which generally works as a revolving credit line, a home equity loan is commonly structured with a fixed amount and fixed repayment term.
In simple terms, a home equity loan turns part of your home’s equity into borrowed cash, with your home serving as collateral.
That can make this type of financing useful for major home improvements, certain debt-consolidation strategies, or other planned expenses. However, because the loan is secured by your home, it also creates an important risk: failing to repay the loan can put your property at risk.
This guide explains how home equity loans work, how rates are determined, what lenders typically require, how much you may be able to borrow, and how to compare a home equity loan with alternatives.
What Is a Home Equity Loan?
A home equity loan is a secured loan that allows a homeowner to borrow against the equity in their property. It is sometimes called a second mortgage when it is taken out while an existing first mortgage remains in place.
Your equity is generally calculated by subtracting the balance owed on your mortgage and other liens from the current market value of your home.
How Home Equity Works
For example, suppose your home is currently worth $500,000 and your remaining mortgage balance is $300,000.
Your estimated equity would be:
$500,000 − $300,000 = $200,000
That does not necessarily mean you can borrow the full $200,000. Lenders normally consider the home’s value, your existing mortgage balance, credit profile, income, debt obligations, and their maximum combined loan-to-value requirements.
The FTC explains that home equity loans use the home as collateral, meaning failure to repay can result in foreclosure.
Home Equity Loan vs. HELOC
The two products are related but work differently.
A home equity loan generally provides a lump sum. You borrow a specific amount and repay it over an agreed term.
A HELOC, or home equity line of credit, works more like a revolving credit account. You receive a credit limit and can generally borrow from the available balance during the draw period.
The difference matters when deciding how predictable your borrowing needs are.
If you know exactly how much money you need for a defined project, a home equity loan may provide greater payment predictability.
If your expenses will occur gradually, a HELOC may provide more flexibility.
How Does a Home Equity Loan Work?
The process is similar in several ways to applying for other mortgage-related financing.
First, the lender evaluates your property and financial situation. Depending on the lender and circumstances, this may include an appraisal or another valuation method.
The lender then determines whether you qualify and how much it is willing to lend.
If approved, you generally receive the loan proceeds as a lump sum. You then make monthly payments according to the loan agreement.
How Much Can You Borrow?
There is no universal amount that every homeowner can borrow.
Your maximum loan amount may depend on:
- Current home value
- Existing mortgage balance
- Other liens on the property
- Credit history
- Income
- Debt-to-income ratio
- Loan-to-value requirements
- Lender-specific underwriting rules
Many lenders set a maximum combined loan-to-value ratio rather than allowing borrowers to access every dollar of available equity.
For example, if a lender allows total mortgage debt equal to 80% of a home’s $500,000 value, the maximum combined debt would be $400,000. If your first mortgage balance is $300,000, that example could leave up to $100,000 of additional borrowing capacity before considering other qualification requirements.
This is only an illustration. Actual limits vary by lender and borrower.
How You Receive the Money
Unlike a HELOC, a home equity loan generally gives you the borrowed funds upfront.
That makes the product easier to budget when you already know the amount you need.
For example, a homeowner planning a $60,000 renovation may prefer knowing the full loan amount and expected monthly payment instead of drawing money repeatedly from a credit line.
How You Repay a Home Equity Loan
Most traditional home equity loans are repaid through regular monthly installments over a fixed term.
A portion of each payment goes toward interest and another portion reduces the principal balance.
Your loan agreement should explain the interest rate, payment amount, repayment schedule, fees, and other terms.
Home Equity Loan Rates and Costs
Interest rates are one of the most important factors when comparing home equity financing.
Home equity loan rates can change over time and vary significantly between borrowers and lenders. Your rate may depend on your credit profile, loan amount, term, property, combined loan-to-value ratio, market conditions, and lender pricing.
Current market surveys show that home equity borrowing rates remain meaningfully above the exceptionally low rates many homeowners saw during 2020–2021. Because rates change, borrowers should compare current offers rather than relying on an old advertised rate.
What Determines Your Interest Rate?
Lenders may consider:
- Credit score and credit history
- Payment history
- Income and employment
- Existing debts
- Loan amount
- Loan term
- Available home equity
- Combined loan-to-value ratio
- Property type
- Overall market conditions
A stronger financial profile may help a borrower qualify for more favorable terms, but approval and pricing are always lender-specific.
Common Home Equity Loan Fees
A home equity loan can involve costs similar to other mortgage financing.
Potential expenses include:
- Application fees
- Appraisal or property valuation fees
- Credit report fees
- Title-related fees
- Recording fees
- Origination charges
- Closing costs
Some lenders advertise low- or no-closing-cost products, but that does not necessarily mean the financing has no cost. The lender may recover expenses through other pricing or terms.
Recent industry guidance indicates that home equity loan and HELOC closing costs can vary substantially by lender and transaction.
Fixed-Rate vs. Variable-Rate Borrowing
A traditional home equity loan commonly has a fixed interest rate.
That can make monthly budgeting easier because the required principal-and-interest payment generally remains stable under the loan agreement.
HELOCs are different. They commonly use variable rates, meaning payments can change as the underlying rate changes.
For homeowners who prioritize predictable payments, understanding this distinction is essential.
Home Equity Loan Requirements
There is no single nationwide checklist that guarantees approval. Each lender has its own underwriting requirements.
However, most lenders evaluate several major areas.
Credit Score Requirements
Your credit history can influence both eligibility and pricing.
There is no universal minimum credit score for every home equity loan. Some lenders may accept borrowers with lower scores, while others establish stricter standards.
Rather than focusing only on a minimum score, look at your complete credit profile.
Before applying, review your credit reports for inaccurate information and consider how recent applications or new debts could affect your profile.
Debt-to-Income Ratio
Your debt-to-income ratio, or DTI, compares your recurring monthly debt obligations with your gross monthly income.
For example, if qualifying monthly debts total $2,500 and gross monthly income is $7,500:
$2,500 ÷ $7,500 = 33.3% DTI
Lenders use DTI as one measure of repayment capacity.
The maximum acceptable DTI can differ between lenders and loan programs, so meeting one lender’s threshold does not guarantee approval elsewhere.
Home Equity Requirements
You generally need meaningful equity in the property to qualify.
A lender may calculate your combined loan-to-value ratio by comparing all secured mortgage debt against the home’s value.
For example:
First mortgage: $300,000
Home equity loan: $80,000
Home value: $500,000
Combined debt would be $380,000.
The combined loan-to-value ratio would therefore be:
$380,000 ÷ $500,000 = 76%
The lender’s maximum CLTV requirement determines whether that structure is acceptable.
Income and Employment Verification
Lenders may request documentation showing that you have sufficient income to repay the new debt.
Depending on your situation, documentation may include:
- Pay stubs
- W-2 forms
- Tax returns
- Bank statements
- Business records for self-employed borrowers
- Employment verification
The exact documentation depends on the lender and your circumstances.
Pros and Cons of a Home Equity Loan
Understanding both sides is important before using your home as collateral.
Benefits of Home Equity Loans
Potential advantages include:
- Lump-sum access to funds
- Predictable repayment structure
- Potentially lower rates than some unsecured borrowing
- Ability to finance major planned expenses
- Potentially useful for substantial home improvements
- Interest may potentially qualify for a tax deduction in certain circumstances
The tax treatment is not automatic. Federal tax rules can depend on how the borrowed money is used and other circumstances, so homeowners should consult a qualified tax professional.
Risks and Potential Drawbacks
The biggest consideration is that your home secures the debt.
If you cannot make the required payments, you could face serious consequences, including foreclosure.
Other potential disadvantages include:
- Closing costs and fees
- Additional monthly debt
- Interest costs over the life of the loan
- Reduced home equity
- Less financial flexibility if circumstances change
- Potential difficulty selling or refinancing depending on the outstanding liens
A home equity loan should therefore be evaluated as secured debt, not simply as an easy source of cash.
How to Apply for a Home Equity Loan
Applying does not have to be complicated, but preparation can make the process smoother.
Check Your Home Equity
Start with a realistic estimate of your home’s current value and subtract your outstanding mortgage and other liens.
An appraisal or lender valuation may ultimately determine the value used for underwriting.
Review Your Credit and Finances
Check your credit reports, monthly debts, income, and existing mortgage payment.
Calculate your approximate DTI before applying so you have a clearer picture of your financial position.
Compare Lenders and Loan Terms
Do not compare interest rates alone.
Review:
- APR
- Interest rate
- Loan term
- Monthly payment
- Closing costs
- Origination fees
- Prepayment provisions
- Maximum borrowing amount
- Fixed or variable rate
- Other lender-specific conditions
The FTC specifically recommends shopping around for home equity financing to compare terms and costs.
Compare Mortgage Lenders
Submit Your Application
Once you select a lender, you will generally provide financial and property information.
The lender evaluates the application and may order a valuation or appraisal.
Complete the Closing Process
Review your closing documents carefully before signing.
Confirm that the loan amount, APR, payment schedule, fees, and other important terms match what you expected.
For certain transactions secured by a borrower’s principal residence, federal law provides a three-business-day right to cancel, subject to specific exceptions. The FTC explains that the rule has detailed requirements and does not apply to every mortgage transaction.
When Should You Consider a Home Equity Loan?
The right use depends on your financial circumstances and the cost of the borrowing.
Home Improvements and Renovations
A home equity loan can provide a defined amount for a major renovation when the project has a relatively predictable budget.
For example, suppose a homeowner estimates a kitchen and bathroom renovation at $50,000. A lump-sum loan could provide the funds needed at the beginning of the project, with repayment spread over a fixed term.
Debt Consolidation
Some homeowners use home equity financing to consolidate higher-interest debt.
However, consolidation only makes financial sense if the overall cost and repayment structure work in your favor.
Remember that unsecured debt may become secured by your home when you use home equity to pay it off.
The FTC warns that consumers should carefully calculate the costs and risks of debt consolidation involving their home.
Major Planned Expenses
Other potential uses can include large, planned expenses.
The key question is not simply whether you can access the money. It is whether adding a secured monthly payment fits comfortably within your long-term budget.
Home Equity Loan vs. Other Borrowing Options
Choosing between financing options requires looking at the full structure rather than one advertised rate.
Home Equity Loan vs. HELOC
| Feature | Home Equity Loan | HELOC |
|---|---|---|
| Funding | Usually lump sum | Draw as needed |
| Rate | Commonly fixed | Commonly variable |
| Payments | Generally predictable | Can change |
| Best suited to | Known expense | Ongoing or uncertain expenses |
| Credit structure | Installment loan | Revolving credit |
A home equity loan may be easier to budget because you know the amount borrowed upfront. A HELOC may provide greater flexibility when expenses happen over time.
Home Equity Loan vs. Cash-Out Refinance
A cash-out refinance replaces your existing mortgage with a new, larger mortgage and gives you the difference in cash.
A home equity loan generally leaves your first mortgage in place and adds another lien.
This distinction can be especially important for homeowners who already have a favorable first-mortgage rate.
Replacing a low-rate mortgage with a higher-rate cash-out refinance could affect the cost of the entire mortgage balance, while a home equity loan may allow the existing first mortgage to remain unchanged.
Cash-Out Refinance Guide
Home Equity Loan vs. Personal Loan
A personal loan is generally unsecured, while a home equity loan is secured by your property.
A personal loan may not require home equity, but its rate and terms can differ substantially from secured financing.
The important comparison is the total borrowing cost, monthly payment, repayment period, and consequences of missed payments.
Frequently Asked Questions About Home Equity Loans
Is a Home Equity Loan a Good Idea?
It depends on your financial situation, the purpose of the borrowing, the loan cost, and your ability to make payments. Because your home secures the debt, it is important to consider the risk before borrowing.
How Much Can I Borrow With a Home Equity Loan?
The amount depends on your home’s value, existing mortgage balance, other liens, lender limits, credit profile, income, and debt-to-income ratio. You generally cannot assume that all of your equity is available to borrow.
Does a Home Equity Loan Have a Fixed Rate?
Many traditional home equity loans have fixed interest rates, although loan products and lender terms vary. A HELOC commonly has a variable rate.
What Credit Score Do I Need for a Home Equity Loan?
There is no single credit-score requirement across all lenders. Each lender establishes its own underwriting standards and may consider your overall credit history, income, debt, equity, and other factors.
Does a Home Equity Loan Affect My Mortgage?
Yes. A home equity loan usually creates additional debt secured by your property. If you already have a first mortgage, the home equity loan may become a second lien.
Can I Use a Home Equity Loan for Anything?
Loan-use restrictions vary by lender and product. Common uses include renovations, major expenses, and debt consolidation. If you are considering borrowing for a specific purpose, confirm the lender’s terms and consider the tax implications with a qualified professional.
Conclusion: Understanding Your Home Equity Loan Options
A Home Equity Loan: How It Works, Rates & Requirements overview comes down to three key ideas: you borrow against available home equity, you usually receive the money as a lump sum, and your property secures the debt.
Before applying, calculate your available equity, review your credit and DTI, compare multiple lenders, and look beyond the advertised interest rate. Fees, repayment terms, loan-to-value limits, and the consequences of missed payments can be just as important.
A home equity loan can be a useful financing tool for a well-defined expense, but it should not be treated as risk-free cash. Your home is valuable collateral, and borrowing against it creates a new financial obligation.
If you are considering a home equity loan, compare your options carefully and speak with a qualified mortgage professional about your specific situation.
Contact a Mortgage Professional







