
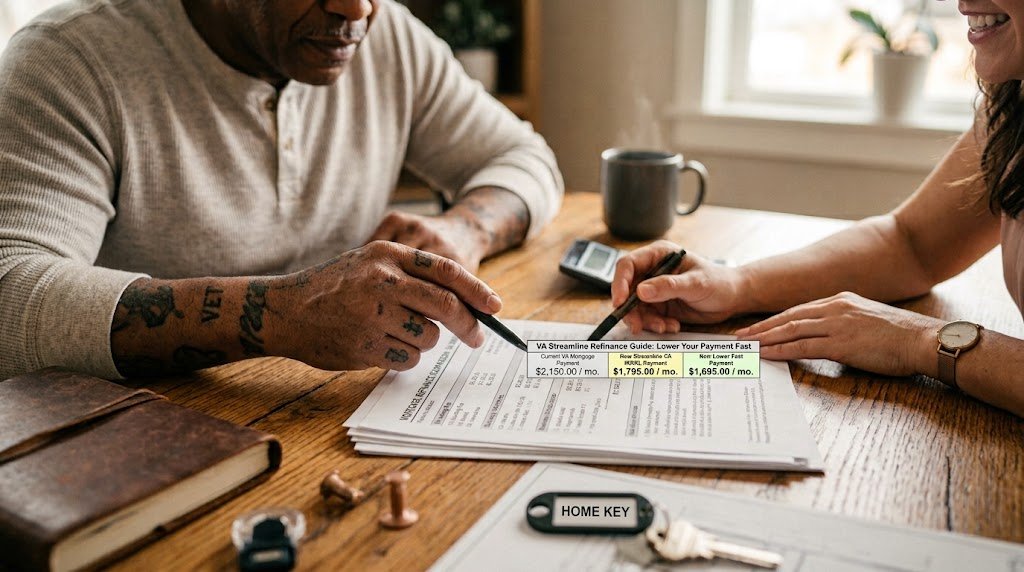
VA Streamline Refinance Guide: Lower Your Payment Fast starts with one important fact: a VA Interest Rate Reduction Refinance Loan (IRRRL) lets eligible homeowners replace an existing VA-backed mortgage with a new loan that may provide a lower rate, lower payment, or more stable payment structure. The VA also calls the IRRRL a “streamline” refinance because the process can involve less documentation than many traditional refinances.
For a homeowner with a relatively high mortgage rate, an IRRRL can be worth investigating. But a lower monthly payment does not automatically mean lower overall borrowing costs. Closing costs, the VA funding fee, the new interest rate, and the length of the replacement loan all matter.
This guide explains the VA IRRRL requirements, costs, potential savings, application process, advantages and disadvantages, and the numbers you should compare before signing.

What Is a VA Streamline Refinance?
A VA Streamline Refinance, officially called an Interest Rate Reduction Refinance Loan (IRRRL), is designed for borrowers who already have a VA-backed home loan.
Instead of keeping the existing mortgage, the borrower replaces it with a new VA-backed loan. The purpose is generally to improve the loan terms rather than take cash out of the home\’s equity. The VA says an IRRRL may help lower monthly payments through a reduced interest rate or make payments more predictable by changing an adjustable-rate loan to a fixed-rate loan.
An IRRRL is different from a VA cash-out refinance.
VA IRRRL:
- Refinances an existing VA-backed mortgage.
- Can potentially reduce the interest rate or payment.
- Can convert an adjustable-rate mortgage to a fixed-rate mortgage.
- Generally does not provide cash from home equity.
- May require less documentation than a standard refinance.
VA cash-out refinance:
- Can be used to refinance and potentially access home equity.
- Has different eligibility and underwriting requirements.
- May be more appropriate when accessing cash is the primary objective.
VA Streamline Refinance Requirements: Who Qualifies?
One of the biggest advantages of the VA IRRRL is that eligibility is tied primarily to the existing VA loan.
According to the U.S. Department of Veterans Affairs, you generally must meet these core requirements:
- You already have a VA-backed home loan.
- The IRRRL refinances that existing VA-backed loan.
- You certify that you currently live in or previously lived in the property.
- If there is a second mortgage, its holder must agree to make the new VA loan the first mortgage.
There are also seasoning requirements that borrowers should understand. Current VA refinance guidance requires the existing loan to meet specific payment and timing requirements. Lenders commonly verify that at least six consecutive monthly payments have been made and that at least 210 days have passed since the first payment due date on the mortgage being refinanced.
Do You Need a New Certificate of Eligibility?
Usually, you do not need to obtain a brand-new Certificate of Eligibility (COE) in the same way you might when initially using your VA home loan benefit. Your lender can generally verify the existing VA loan and entitlement information as part of the refinance process.
However, lender requirements can vary, so it is still smart to ask exactly what documentation will be required before submitting an application.
How Does a VA IRRRL Lower Your Mortgage Payment?
The simplest way an IRRRL can lower your payment is through a lower interest rate.
For example, imagine a borrower has:
- $300,000 remaining principal
- 30-year remaining term
- 7.00% interest rate
The principal-and-interest payment would be approximately $1,996 per month.
If the same $300,000 balance were refinanced into a new 30-year loan at 6.00%, the principal-and-interest payment would be approximately $1,799 per month.
That is roughly $197 per month in principal-and-interest savings before considering taxes, insurance, closing costs, or changes to the loan balance.
The example is intentionally simple. Actual savings depend on the borrower\’s balance, rate, remaining term, loan costs, and the rate available from the lender.
The important lesson is this:
Compare the new total loan cost—not just the new monthly payment.
A lender may advertise a lower payment, but extending the repayment period can increase the amount of interest paid over the life of the mortgage. Both the VA and major mortgage lenders warn borrowers to evaluate the long-term cost before refinancing.

VA Streamline Refinance Costs You Need to Know
“Streamline” does not mean “free.”
An IRRRL can involve a VA funding fee and other closing costs.
VA IRRRL Funding Fee
The VA IRRRL funding fee is generally 0.5% of the loan amount. Certain borrowers may qualify for an exemption, including eligible borrowers who meet VA requirements related to disability compensation.
For example, on a $300,000 loan amount, a 0.5% funding fee would equal $1,500.
The fee may be financed into the new loan rather than paid entirely upfront, subject to the applicable loan terms.
Other Closing Costs
Depending on the transaction and lender, costs can include items such as:
- Loan origination charges
- Title-related costs
- Recording fees
- Prepaid interest
- Property taxes
- Homeowners insurance
- Other lender or settlement charges
The VA specifically advises borrowers to consider closing costs when determining whether an IRRRL makes financial sense.
Can You Get a VA IRRRL With No Money Out of Pocket?
Potentially.
Some closing costs can be included in the new loan, meaning you may not have to bring the entire amount to closing. However, financing costs increases the new loan balance and can result in additional interest over time. The VA confirms that certain costs may be included in the new loan or, in some cases, offset through pricing offered by the lender.
“Zero out of pocket” therefore should never be interpreted as “zero cost.”
What Is the Break-Even Point on a VA IRRRL?
The break-even point tells you approximately how long it takes for your monthly savings to recover the refinancing costs.
Use this basic calculation:
Break-even months = Total refinance costs ÷ Monthly savings
For example:
- Closing costs: $4,000
- Monthly principal-and-interest savings: $200
- Break-even period: 20 months
If you expect to keep the mortgage substantially longer than 20 months, the refinance may have a stronger financial case.
But this calculation is only a starting point. If the closing costs are added to the new loan, interest on those costs should also be considered.
A Better Comparison
Ask your lender for these five numbers:
- Current loan balance
- New loan balance
- Current interest rate
- New interest rate
- Total refinance costs
Then compare the short-term monthly savings with the long-term total interest and finance charges.
This is one of the most useful practical checks because it prevents a lower payment from becoming the only decision-making factor.
What Are the Benefits of a VA Streamline Refinance?
A VA IRRRL can offer several advantages to eligible homeowners.
Less Documentation
Compared with many traditional refinances, an IRRRL can require less documentation. In many situations, a new appraisal, income verification, or full credit underwriting may not be required. However, lender requirements can differ.
Potentially Lower Monthly Payments
A lower interest rate can reduce principal-and-interest payments.
Convert an ARM to a Fixed Rate
If your existing VA mortgage has an adjustable rate, an IRRRL can potentially convert it into a fixed-rate loan, giving you more predictable payments.
No Private Mortgage Insurance
VA loans generally do not require monthly private mortgage insurance (PMI), which can make the structure different from many conventional mortgages.
Potentially No New Appraisal
An IRRRL generally does not require a new VA appraisal, although lenders can have their own requirements.
What Are the Disadvantages of a VA IRRRL?
A VA streamline refinance is not automatically beneficial for every borrower.
Your Total Interest Could Increase
If you restart the mortgage with a longer term, your monthly payment could decrease while the total amount of interest paid over time increases.
Closing Costs Reduce Your Savings
Even when costs are rolled into the loan, you are still paying them.
You Cannot Use an IRRRL for Cash Out
An IRRRL is intended for refinancing the existing VA loan rather than taking cash from your home\’s equity. If accessing equity is the objective, another refinance strategy may be more appropriate.
Rates and Fees Vary by Lender
The VA does not originate IRRRLs directly. Borrowers work with private banks, mortgage companies, or credit unions, and the VA recommends comparing lenders because terms and fees can vary.
How to Compare VA Mortgage Lenders
VA Streamline Refinance Guide: Step-by-Step Process
Once you believe an IRRRL may make sense, the process is relatively straightforward.
Step 1: Confirm Your Existing Loan Is VA-Backed
An IRRRL is specifically for refinancing an existing VA-backed mortgage.
Step 2: Check Your Payment and Seasoning History
Confirm that you meet the applicable VA seasoning requirements and have maintained the required payment history.
Step 3: Review Current Rates
Don\’t assume that a small rate reduction automatically produces worthwhile savings.
Ask for a personalized quote showing the interest rate, APR, loan balance, points, lender fees, and estimated closing costs.
Step 4: Compare Multiple Lenders
The VA specifically recommends contacting multiple lenders because fees and terms can differ.
Compare:
- Interest rate
- APR
- Points
- Lender fees
- Closing costs
- Funding fee
- New loan balance
- Loan term
- Estimated monthly payment
Step 5: Review the Loan Estimate
Don\’t judge the offer from a headline rate alone.
Review the Loan Estimate and ask the lender to explain any unfamiliar fees or charges.
Step 6: Calculate Your Break-Even Period
Determine how long your monthly savings will take to recover the refinancing costs.
Step 7: Close on the New Loan
After approval and closing, the new VA loan pays off the existing mortgage. You then begin making payments under the new loan terms.
Mortgage Refinance Closing Process
When Is a VA IRRRL Worth It?
A VA IRRRL may be worth considering when:
- Your current mortgage rate is meaningfully higher than the rate you can obtain.
- Your monthly payment would decrease enough to justify the costs.
- You plan to keep the mortgage long enough to reach the break-even point.
- You want to move from an adjustable rate to a fixed rate.
- Your current loan has become less attractive because market conditions have changed.
- You want a potentially simpler refinance process.
On the other hand, refinancing may be less attractive if the rate improvement is tiny, closing costs are high, or you expect to sell or pay off the home soon.
The best answer comes from comparing your own numbers—not from a generic “refinance when rates drop” rule.
How Fast Can a VA Streamline Refinance Close?
An IRRRL can move faster than many traditional refinance transactions because some conventional underwriting steps may be reduced or eliminated. But there is no universal closing time.
Your timeline can depend on:
- Lender workload
- Document collection
- Title requirements
- Loan complexity
- State requirements
- Underwriting
- Closing availability
Some lenders advertise faster processing, but borrowers should avoid assuming that every IRRRL will close within
a particular number of days.
The safest approach is to ask your lender for an estimated timeline before locking in your plans.
2026 VA IRRRL Checklist
Before applying, review this quick checklist:
I currently have a VA-backed mortgage.
I meet the applicable VA seasoning requirements.
I have made the required payments on time.
I currently live in or previously lived in the property.
I understand the new interest rate.
I know the estimated closing costs.
I checked whether I qualify for a funding-fee exemption.
I calculated my estimated break-even period.
I compared more than one lender.
I reviewed the new loan term.
I compared total interest, not just monthly payment.
I understand that an IRRRL is not a cash-out refinance.
The VA\’s official IRRRL page was updated January 7, 2026, making it the best place to verify current federal program requirements before publication or application.
Is a VA Streamline Refinance Right for You?
A VA IRRRL can be a powerful way for an eligible homeowner to improve an existing VA mortgage, particularly when a lower rate produces meaningful monthly savings or when converting an adjustable-rate mortgage to a fixed rate provides greater payment stability.
But the phrase “lower payment” should never be the entire analysis.
Look at the new rate, loan balance, closing costs, loan term, break-even period, and total interest. Then compare offers from multiple lenders.
For official eligibility information, start with the U.S. Department of Veterans Affairs IRRRL guidance.
If the numbers show meaningful savings and you expect to keep the mortgage beyond your break-even period, a VA Streamline Refinance may be worth discussing with a qualified VA lender.
CTA: Want to evaluate your potential savings? Compare your current mortgage rate, balance, payment, and estimated refinance costs with a qualified mortgage professional before deciding.
3. FAQ Section
What is a VA Streamline Refinance?
A VA Streamline Refinance is another name for a VA Interest Rate Reduction Refinance Loan (IRRRL). It allows an eligible borrower with an existing VA-backed mortgage to replace that loan with a new VA loan that may offer a lower rate, lower payment, or more stable payment terms.
What are the basic VA IRRRL requirements?
You generally must already have a VA-backed home loan, use the new loan to refinance that VA loan, and certify that you currently live in or previously lived in the property. Additional seasoning and lender requirements also apply.
Does a VA IRRRL require an appraisal?
A new appraisal is generally not required for an IRRRL, although individual lenders can have additional requirements.
Can a VA IRRRL lower my monthly mortgage payment?
Yes. If the new loan has a sufficiently lower interest rate, the principal-and-interest payment may decrease. However, closing costs and a longer repayment term can affect the overall financial benefit.
How much does a VA IRRRL cost?
Costs vary by loan and lender. An IRRRL generally has a 0.5% VA funding fee unless the borrower qualifies for an exemption, plus potentially applicable lender and settlement costs.
Can I get cash out with a VA Streamline Refinance?
No. An IRRRL is designed to refinance an existing VA loan rather than provide cash from home equity. A different VA refinance option may be more appropriate if cash out is the primary goal.






